
Ralph Lauren (RL) Faces A 90 Day Pullback, Is It Still 20% Undervalued?
Ralph Lauren (RL) has held investors’ attention after recent share price swings, with the stock last closing at US$357.16. The company reported US$8.4b in revenue and US$982.9m in net income.
Recent trading has been choppy for Ralph Lauren, with a 5.1% 7 day share price return following a period where the 90 day move is down 11%. In spite of that setback, total shareholder return of 16.9% over one year and a very large 3 and 5 year total shareholder return suggest longer term holders have still seen substantial value creation. At the same time, the latest swings hint at shifting views on how durable that performance might be.
Scan how Ralph Lauren compares with other consumer stocks showing strong long term returns and recent volatility by reviewing the hand picked 30 resilient stocks with low risk scores.
Ralph Lauren’s sharp pullback over the past quarter sits against years of strong total returns. Does that recent weakness offer a reasonable entry now, or does patience for a cheaper price make more sense before committing fresh capital?
Most Popular Narrative: 20% Undervalued
Ralph Lauren’s most followed narrative pegs fair value at about $446.71 per share, versus the latest close at $357.16. That gap reflects a view that the current price does not fully reflect the brand elevation and earnings potential analysts are building into their models.
Accelerating international expansion, especially in Asia and Greater China where sales grew over 30% and now represent 9% of company revenue (up from 3-4% a few years ago), positions Ralph Lauren to benefit from rising global wealth and middle-class growth, supporting sustained top-line revenue gains.
Strong digital adoption, including double-digit growth in direct-to-consumer (DTC) digital channels and expansion of live shopping in China, enables higher-margin online sales and greater global reach, which structurally bolsters net margins and future earnings growth.
See why 26 investors see Ralph Lauren as 20% undervalued.
The narrative uses an 8.94% discount rate and assumes steady revenue and profit expansion to arrive at the $446.71 fair value mark. That figure sits modestly above the Simply Wall St DCF estimate of $377.25, yet both reference the same underlying idea that future cash flows and earnings capacity could justify more than the current share price.
Analysts tying this story together point to a mix of levers. These include average unit retail uplift from fewer discounts, operating margin progress, and contributions from newer categories such as handbags and accessories alongside core apparel. At the same time, they flag very real pressures, including higher inventories, tariff risk, and a softer outlook in Europe, which are all baked into the margin and growth assumptions rather than ignored.
Investors weighing this narrative against the recent 11% 90 day pullback in Ralph Lauren’s share price can focus on the gap between $446.71 and $357.16, then decide whether the embedded growth and profitability path feels achievable. The fair value story is only as strong as an individual investor’s conviction in those inputs.
Result: Fair Value of $446.71 (UNDERVALUED)
Still, that fair value story can unravel quickly if European momentum slows, as management has cautioned, or if elevated inventories force heavier discounting that squeezes margins.
Find out about the key risks to this Ralph Lauren narrative.
Another View: Ralph Lauren Through Market Multiples
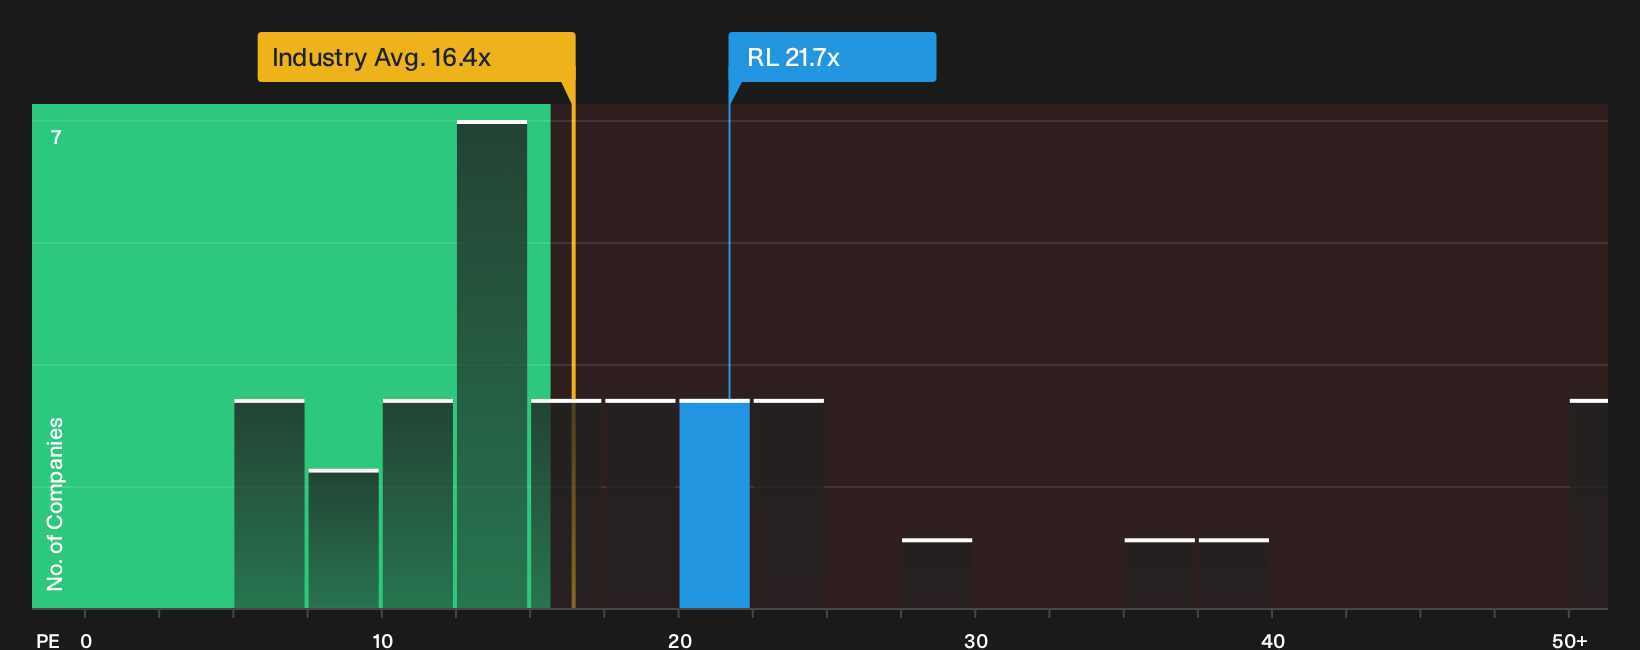
The fair value case for Ralph Lauren at $446.71 leans on projected cash flows and margin expansion. Market pricing tells a cooler story. The stock trades on a P/E of 21.7x, ahead of both the peer average at 16.4x and a fair ratio of 19x. This points to less obvious upside and more valuation risk if growth expectations soften.
That richer P/E relative to both the sector and the fair ratio suggests investors already pay a premium for Ralph Lauren. The real question is whether the earnings path described in the narrative is strong enough to keep that premium intact or even stretch it further.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Ralph Lauren’s valuation and risk profile can feel messy, so move quickly, review the data, and weigh both sides yourself with 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Ralph Lauren?
If Ralph Lauren has sharpened your focus on quality, do not stop here. Broaden your watchlist with other opportunities that could fit your style of investing.
- Explore potential long-term compounding by scanning for companies with stronger fundamentals and attractive entry points using the 32 high quality undervalued stocks.
- Consider your income objectives by reviewing the 6 dividend fortresses with generous yields and resilient cash flows.
- Focus on downside protection by filtering for resilient businesses through the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com