
Is SK Hynix (KOSE:A000660) Still Undervalued On Its Earnings?
SK hynix has seen a powerful run in recent years, which puts a sharp spotlight on whether the current share price lines up with the earnings that underpin it. With that kind of move already on the table, the key issue for you is what those profits really justify today.
- Over the past 5 years the stock has delivered a total return of about 1,801.8%, which raises a direct question about how much of that shift is supported by the underlying earnings power of the business.
- For a memory chip producer like SK hynix, swings in pricing, capacity plans and capital spending can all affect how much of its revenue ultimately turns into sustainable earnings.
- The analysts covering SK hynix have run their own numbers. See what analysts think SK hynix's shares could be worth.
The issue now is whether the current market value of SK hynix is properly explained by the earnings it is generating today and is expected to produce in the future.
If you are weighing SK hynix on its earnings, it can help to compare it with other chip related opportunities by scanning 88 AI infrastructure stocks.
Is SK hynix Still Cheap on Earnings?
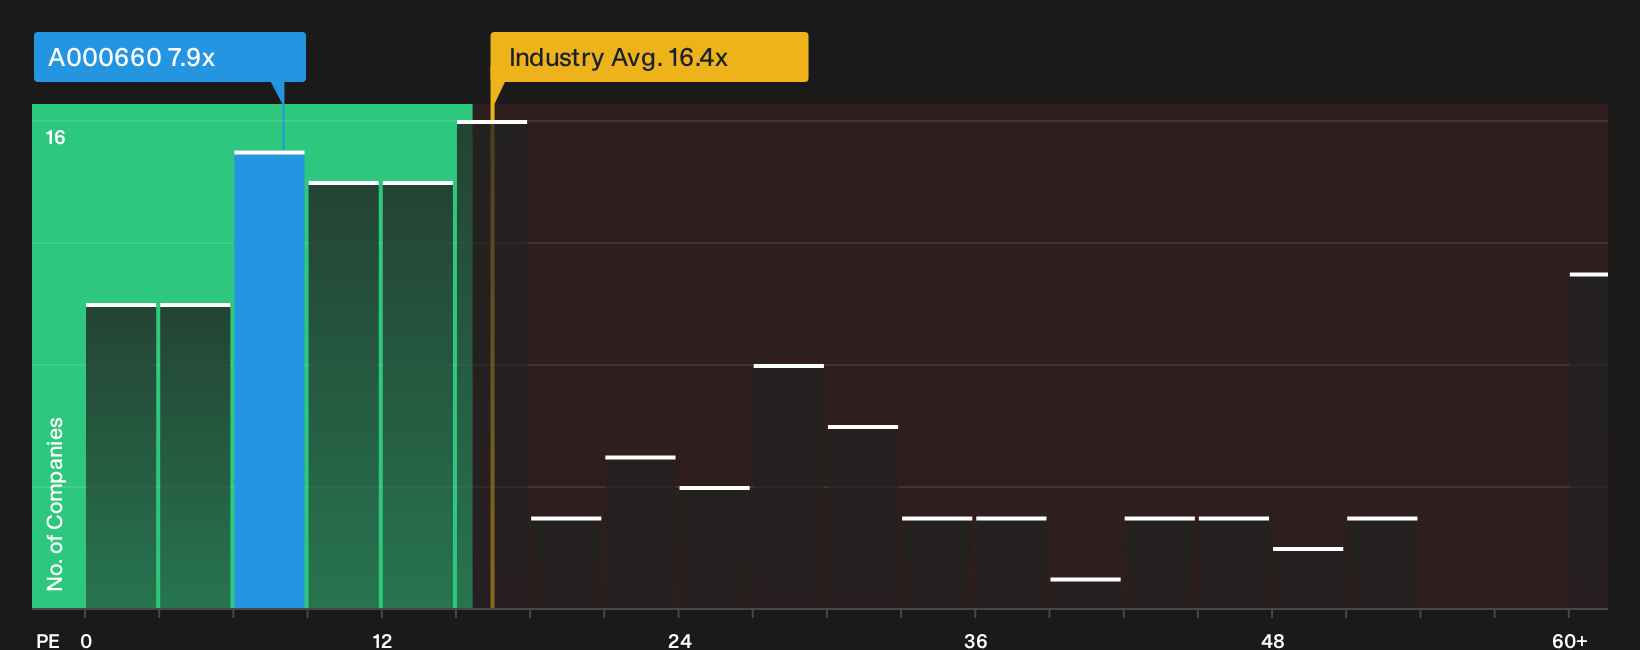
The P/E ratio is a useful lens for SK hynix because earnings tend to drive how investors think about memory chip producers over a full cycle. Right now the stock trades on about 7.9x earnings, which is less than half the broader semiconductor industry average of roughly 16.4x and also well below peers at around 16.6x. That is a wide gap for a large, established player in the sector.
The fair multiple implied by SK hynix's own profile is higher than where the shares trade today, so the current P/E screens as undervalued on this framework rather than stretched. For you as an investor, that means the market is attaching a lower price tag to each ₩ of earnings than both the tailored fair benchmark and the broader chip group. The key judgement is whether the business can sustain the earnings base that ratio is built on. Explore the numbers behind SK hynix's P/E valuation.
The SK hynix Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for SK hynix leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the stock to be worth materially more or less than it is today. Each narrative links its number to a specific view on how SK hynix's growth, margins and key risks might evolve, giving you a reference point you can come back to as fresh information appears.
Community views on SK hynix are split between one group that sees meaningful upside and another that thinks expectations already look full.
Bull case: 44% undervalued
"Leadership in advanced memory and storage technologies for AI underpins premium pricing, margin expansion, and future-proofed revenue growth…"
Discover why this Narrative puts SK hynix at 44% undervalued.
Bear case: 10% overvalued
"Intensifying geopolitical tensions, including tightening US export controls on China and persistent trade frictions, could severely restrict SK hynix's access to key international markets…"
Explore why this Narrative puts SK hynix at 10% overvalued.
One more SK hynix check that belongs next to the earnings multiple
Price ratios tell you what the market is willing to pay for SK hynix today. Analyst roadmaps for profits a few years out show what others think that price is lining up against. Explore where analysts expect SK hynix to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com