
Pegasystems (PEGA) Stock Looks To Trade At A Discount To Fair Value
Pegasystems has had a rough spell lately, with the stock down sharply over the past year, which puts fresh focus on whether the current share price lines up with what its earnings can support. After a move like this, the question for you is whether recent results and profit power justify where the market now values the business.
- Over the past 3 years the Pegasystems share price has gained 55.2%, which makes it important to check if earnings progress can carry that kind of long term return.
- The company’s focus on software and recurring contracts can influence how consistently profits convert into cash, which matters a lot when you are assessing what its earnings are really worth.
- Your read on Pegasystems is one view; the desks covering it have another. See what analysts think Pegasystems's shares could be worth.
The issue now is whether Pegasystems’ current market price is justified by the earnings the business is generating today.
If you want a broader earnings check alongside Pegasystems, a focused starting point is a list of 32 high quality undervalued stocks.
Is Pegasystems a Bargain on Earnings?
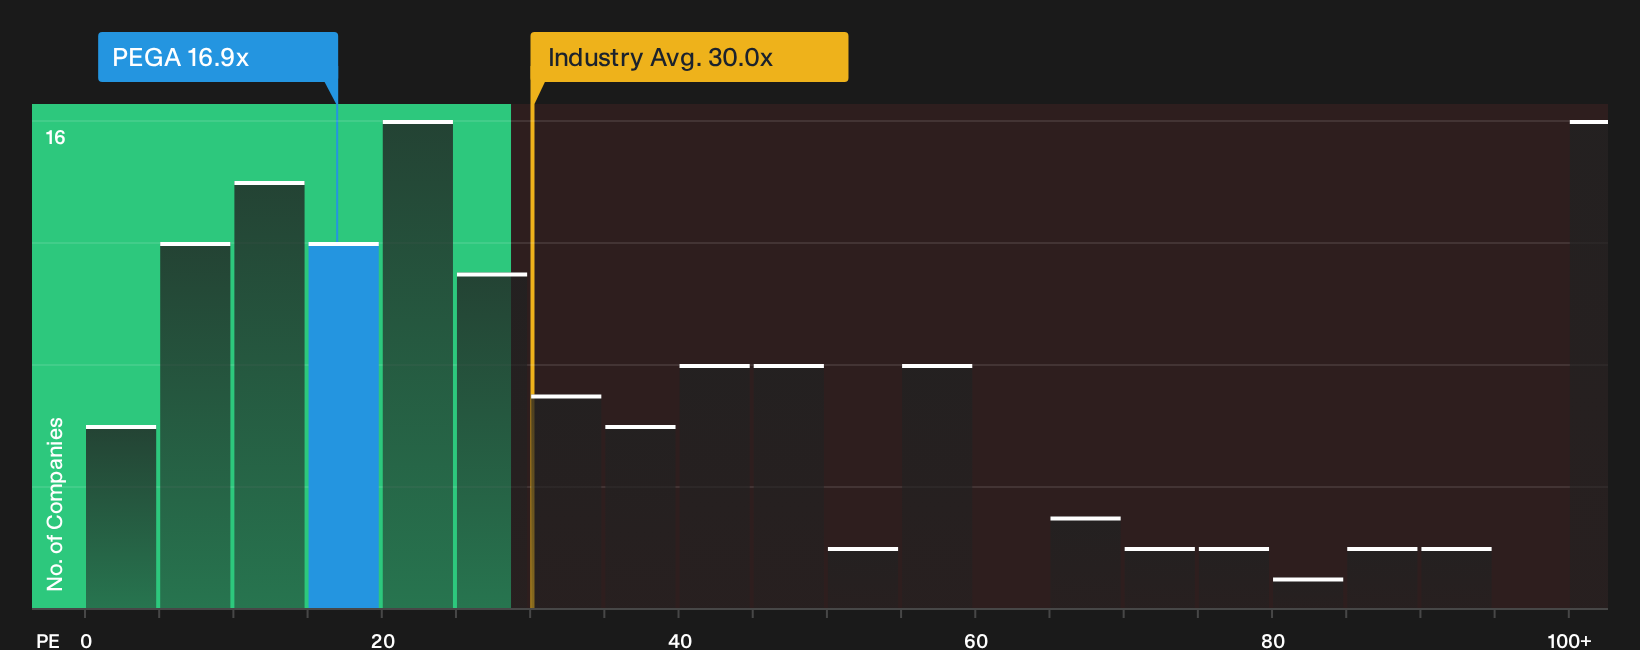
The P/E ratio fits Pegasystems because earnings are a central way investors evaluate mature software platforms with recurring revenue. On this measure, the stock trades on about 16.9x earnings, which is well below the wider Software sector average of roughly 30.0x. Compared with direct peers around 29.0x, the current tag also reflects a clear discount.
A tailored fair P/E that factors in Pegasystems’ own growth profile, profitability and risk sits above where the shares change hands today. This framework points to the stock appearing undervalued on earnings. For you as a shareholder or prospective buyer, that gap raises the question of whether the market is underestimating the durability and quality of Pegasystems’ profit stream or correctly pricing in business risks and execution questions. Explore the numbers behind Pegasystems's P/E valuation.
The Pegasystems Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle leaves off for Pegasystems, by spelling out which paths for revenue growth, profit margins and earnings would need to play out for the stock to be worth much more or much less than today’s quote on Simply Wall St’s Community page. Each storyline ties a fair value to a particular mix of potential catalysts and risks, so you can track which version of Pegasystems' future is actually unfolding over time.
Community views on Pegasystems are split between those who think recent AI deal delays have created an opportunity and those who see execution risk as the bigger story.
Bull case: 45% undervalued
"Analyst consensus anticipates Pega's AI-driven Blueprint to accelerate digital and legacy transformation, but given unprecedented adoption by both clients and major global systems integrators…"
Discover why this Narrative puts Pegasystems at 45% undervalued.
Bear case: 33% overvalued
"Management now expects 2026 ACV growth closer to 10% rather than the earlier 15% ambition, combined with Q2 2026 revenue that fell short of analyst expectations and lagged automation peers…"
Explore why this Narrative puts Pegasystems at 33% overvalued.
Before you decide on Pegasystems, there is one more check to run
Pegasystems’ valuation story only goes so far without understanding the specific business risks that recent checks have highlighted, which could reshape how you view the entire opportunity. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com