
Live Nation Entertainment (LYV) On International Expansion Hopes And Venue Growth Looks Undervalued
Live Nation Entertainment (LYV) has drawn fresh attention after recent trading left the share price at $171.89, with returns mixed across different time frames, including gains over the past year alongside a decline in the past month.
Recent trading in Live Nation Entertainment suggests momentum has cooled in the short term, with the 30-day share price return down 5.37%, even as the year-to-date share price return sits at 18.29% and the 3-year total shareholder return reaches 103.64%.
Compare Live Nation Entertainment's recent momentum shift with other potential breakouts by scanning our hand picked list of 32 high quality undervalued stocks.
Live Nation Entertainment has cooled after a strong run, with short term returns slipping even as longer term holders remain well ahead. Is this a moment to step in now, or to wait for a cheaper opportunity to participate in the same story?
Most Popular Narrative: 15% Undervalued
Live Nation Entertainment’s most followed valuation story pegs fair value at $201.96 per share, a premium to the recent $171.89 close that hinges on what its venues, Ticketmaster platform and sponsorship deals can earn over time.
Expansion of Live Nation Entertainment into underpenetrated international markets, where Latin America activity is reported at one tenth of U.S. levels and Japan and Western Europe show meaningful headroom, is cited as a potential driver of long term ticket volumes and concert revenue as fan activity in these regions moves closer to U.S. levels.
Ongoing buildout of Venue Nation arenas, including over 20 projects in construction or fully permitted and a planned 15 million fan capacity addition across 2026 and 2027, is described as a way to increase owned infrastructure exposure and on-site spending opportunities that could support higher revenue and improved net margins once these venues are fully contributing.
See why 21 investors see Live Nation Entertainment as 15% undervalued.
Result: Fair Value of $201.96 (UNDERVALUED)
Still, Live Nation Entertainment faces active antitrust scrutiny around Ticketmaster, and a recent US$450 million legal accrual that could reshape contracts, costs and long term profitability.
Find out about the key risks to this Live Nation Entertainment narrative.
Another View: What Multiples Say About Live Nation Entertainment
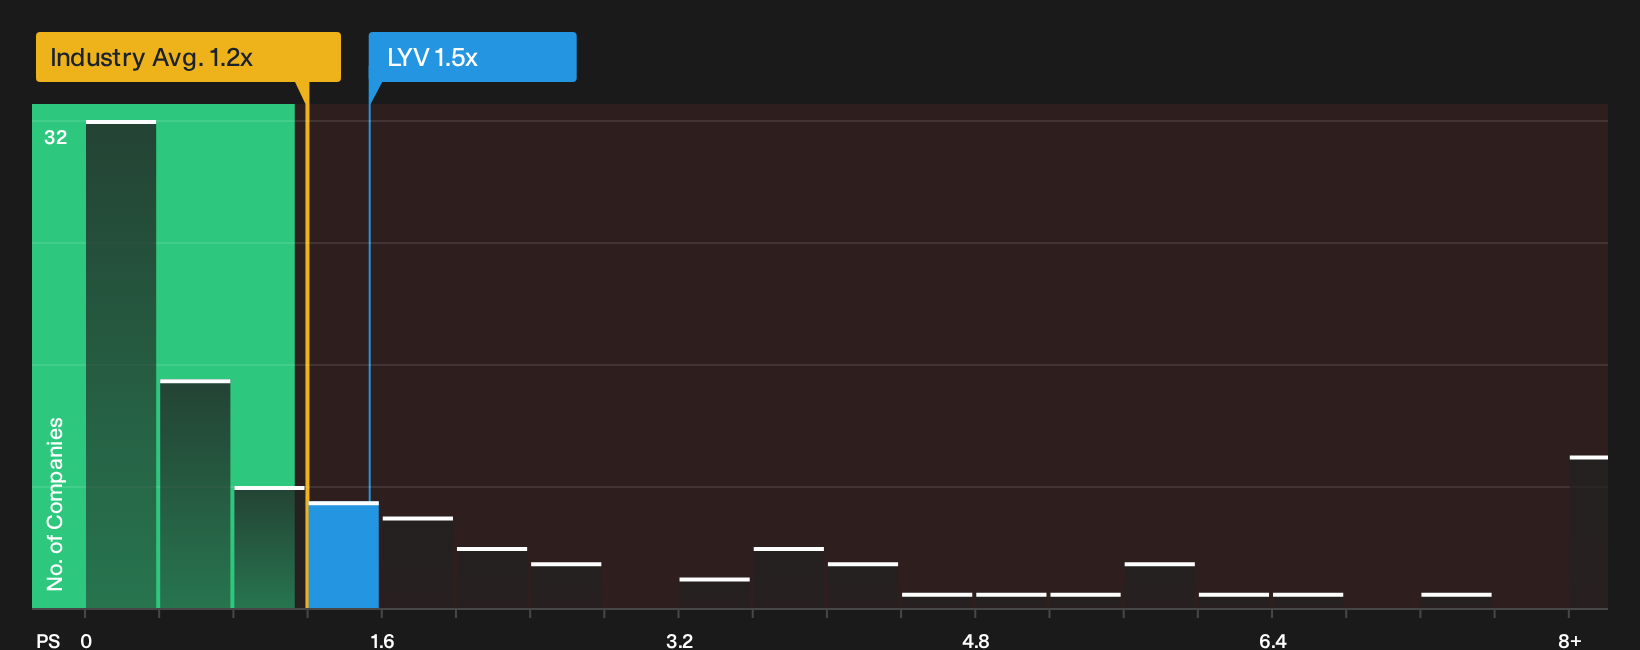
There is a different read on Live Nation Entertainment once price-to-sales comes into focus. The stock trades on a P/S of 1.5x compared with 1.2x for the broader US Entertainment group, yet the fair ratio for Live Nation is estimated at 2.3x. That mix of slight premium to the sector but sizeable gap to the fair ratio may indicate valuation headroom or mispriced risk. Which side of that trade do you think is closer to reality?
For a closer look at how this pricing stacks up against fundamentals, review the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Here is how Live Nation Entertainment’s valuation multiple compares with peers in visual form
Next Steps
If the mixed tone on Live Nation Entertainment leaves you unsure, consider acting promptly and stress test the upside yourself by reviewing the 2 key rewards.
Looking for more investment ideas beyond Live Nation Entertainment?
If Live Nation Entertainment has your attention but you want broader context, use the Simply Wall Street Screener to pressure test your next move across different angles.
- Target resilient balance sheets and steady fundamentals by screening a curated list of solid balance sheet and fundamentals (25 results) that can help you anchor a more defensive core portfolio.
- Hunt for mispriced potential by scanning the 32 high quality undervalued stocks that combine strong underlying metrics with prices that may not fully reflect them yet.
- Build a watchlist of under-the-radar opportunities by reviewing the 16 high quality undiscovered gems before the crowd starts paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com