
Waste Connections (WCN), What Is Drawing Fresh Attention Now?
Waste Connections (WCN) has been trading under pressure, with the share price down about 6% over the past month and roughly 6% in the past 3 months, prompting fresh attention from investors.
Set against a longer track record, the recent weakness in Waste Connections’ share price looks more like fading momentum than a sharp break in sentiment. While the stock’s year to date share price return is down 10.31%, the 3 year total shareholder return of 20.51% and 5 year total shareholder return of 30.34% indicate that investors who stayed in over multiple years have still seen positive outcomes despite the pullback from the current US$156.16 level.
Contrast Waste Connections’ recent pullback with a curated group of resilient operators by scanning our 30 resilient stocks with low risk scores that have also been tested by choppy share price action.
For Waste Connections, the recent slide could hint at investors rethinking sentiment rather than a sudden change in the underlying business. Does the current valuation reflect that gap or exaggerate it?
Most Popular Narrative: 23% Undervalued
On the most followed narrative, Waste Connections is framed as undervalued, with a fair value of $203.92 compared with the last close at $156.16, which puts the current share price at a meaningful discount to those assumptions.
Robust acquisition activity, with annualized revenues closed already over $125 million, and a strong balance sheet position Waste Connections well for continued growth and successful integration of acquisitions, supporting future revenue and earnings growth.
See why 19 investors see Waste Connections as 23% undervalued.
Result: Fair Value of $203.92 (UNDERVALUED)
Still, the Waste Connections story can be knocked off course if acquisition integrations squeeze margins, or if commodity linked recycling revenue turns more volatile than expected.
Find out about the key risks to this Waste Connections narrative.
Another View: Waste Connections Looks Expensive On Earnings
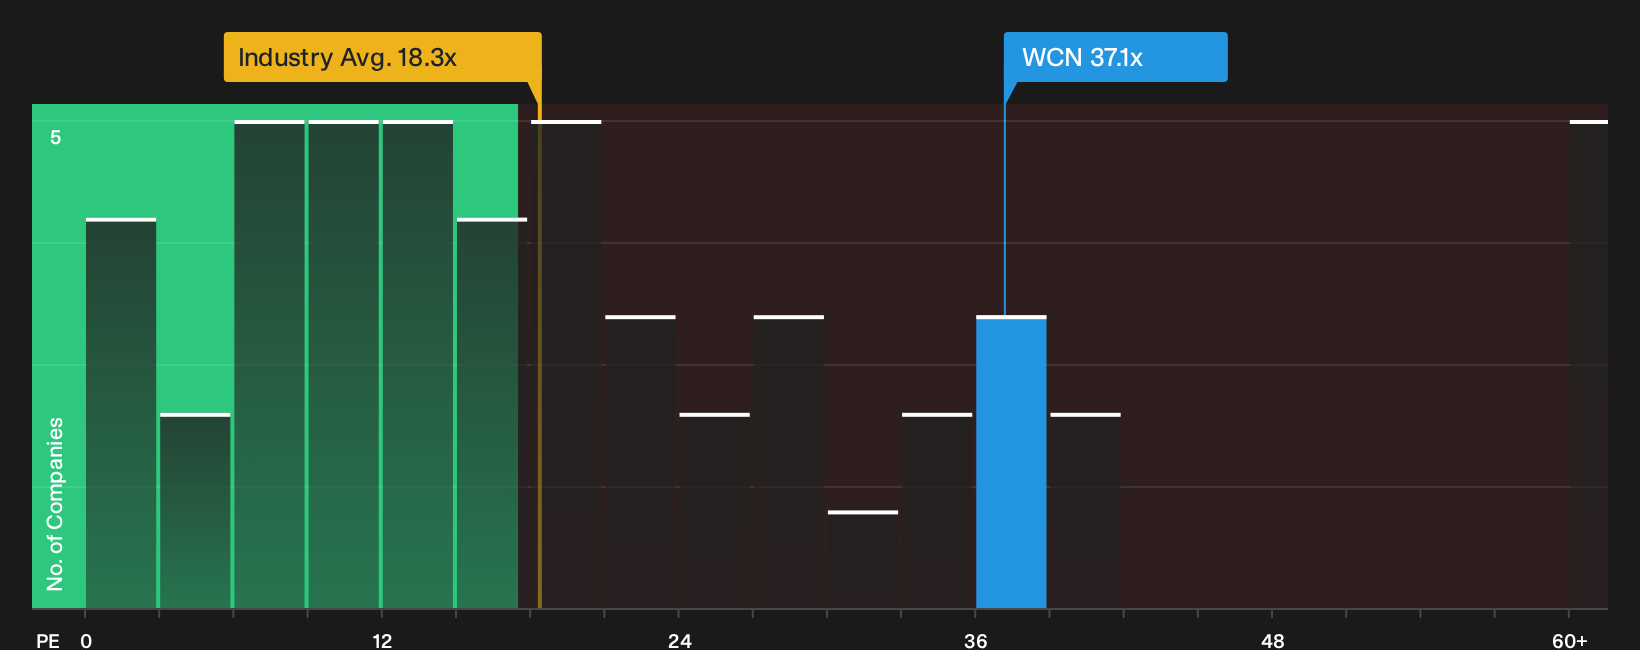
Look at Waste Connections through a simple P/E lens and the story shifts. The stock trades on 37.1x earnings compared with a fair ratio of 26.2x, the US Commercial Services industry at 17.5x, and peers at 30x. That premium suggests less margin for error if expectations slip. Is that extra multiple something you are comfortable paying for?
To stress test this richer pricing against the underlying numbers, review the valuation breakdown via the See what the numbers say about this price — find out in our valuation breakdown..
Put the current earnings multiple in context next to sector levels with the latest comparison chart:
Next Steps
Mixed views on Waste Connections so far. If you want your own take, move quickly and weigh both sides by checking the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Waste Connections?
Do not stop with Waste Connections. Use the Simply Wall St Screener to spot fresh opportunities that match your style before other investors move first.
- Target reliable cash generators by scanning companies with a track record of strong payouts through the 6 dividend fortresses.
- Hunt for quality at a discount by reviewing the 16 high quality undiscovered gems that pair solid fundamentals with limited current attention.
- Prioritize resilience in choppy markets by filtering for businesses on the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com