
CoreWeave Stock Just Got a Jaw-Dropping Upgrade From JPMorgan
CoreWeave (CRWV) just got another vote of confidence from Wall Street.
This time, JPMorgan upgraded CoreWeave to “Outperform” from “Neutral” and raised its price target to $125 from $120. The bank especially points to a more favorable pricing environment for AI compute.
The call comes as demand for AI infrastructure remains strong while available capacity stays relatively tight. For CoreWeave, that could create room to charge more for shorter-term contracts and improve the economics of its rapidly expanding business.
The upgrade also challenges one of the biggest concerns hanging over the stock, whether massive capital spending and rising debt can overwhelm its growth.
CoreWeave Stock Performance
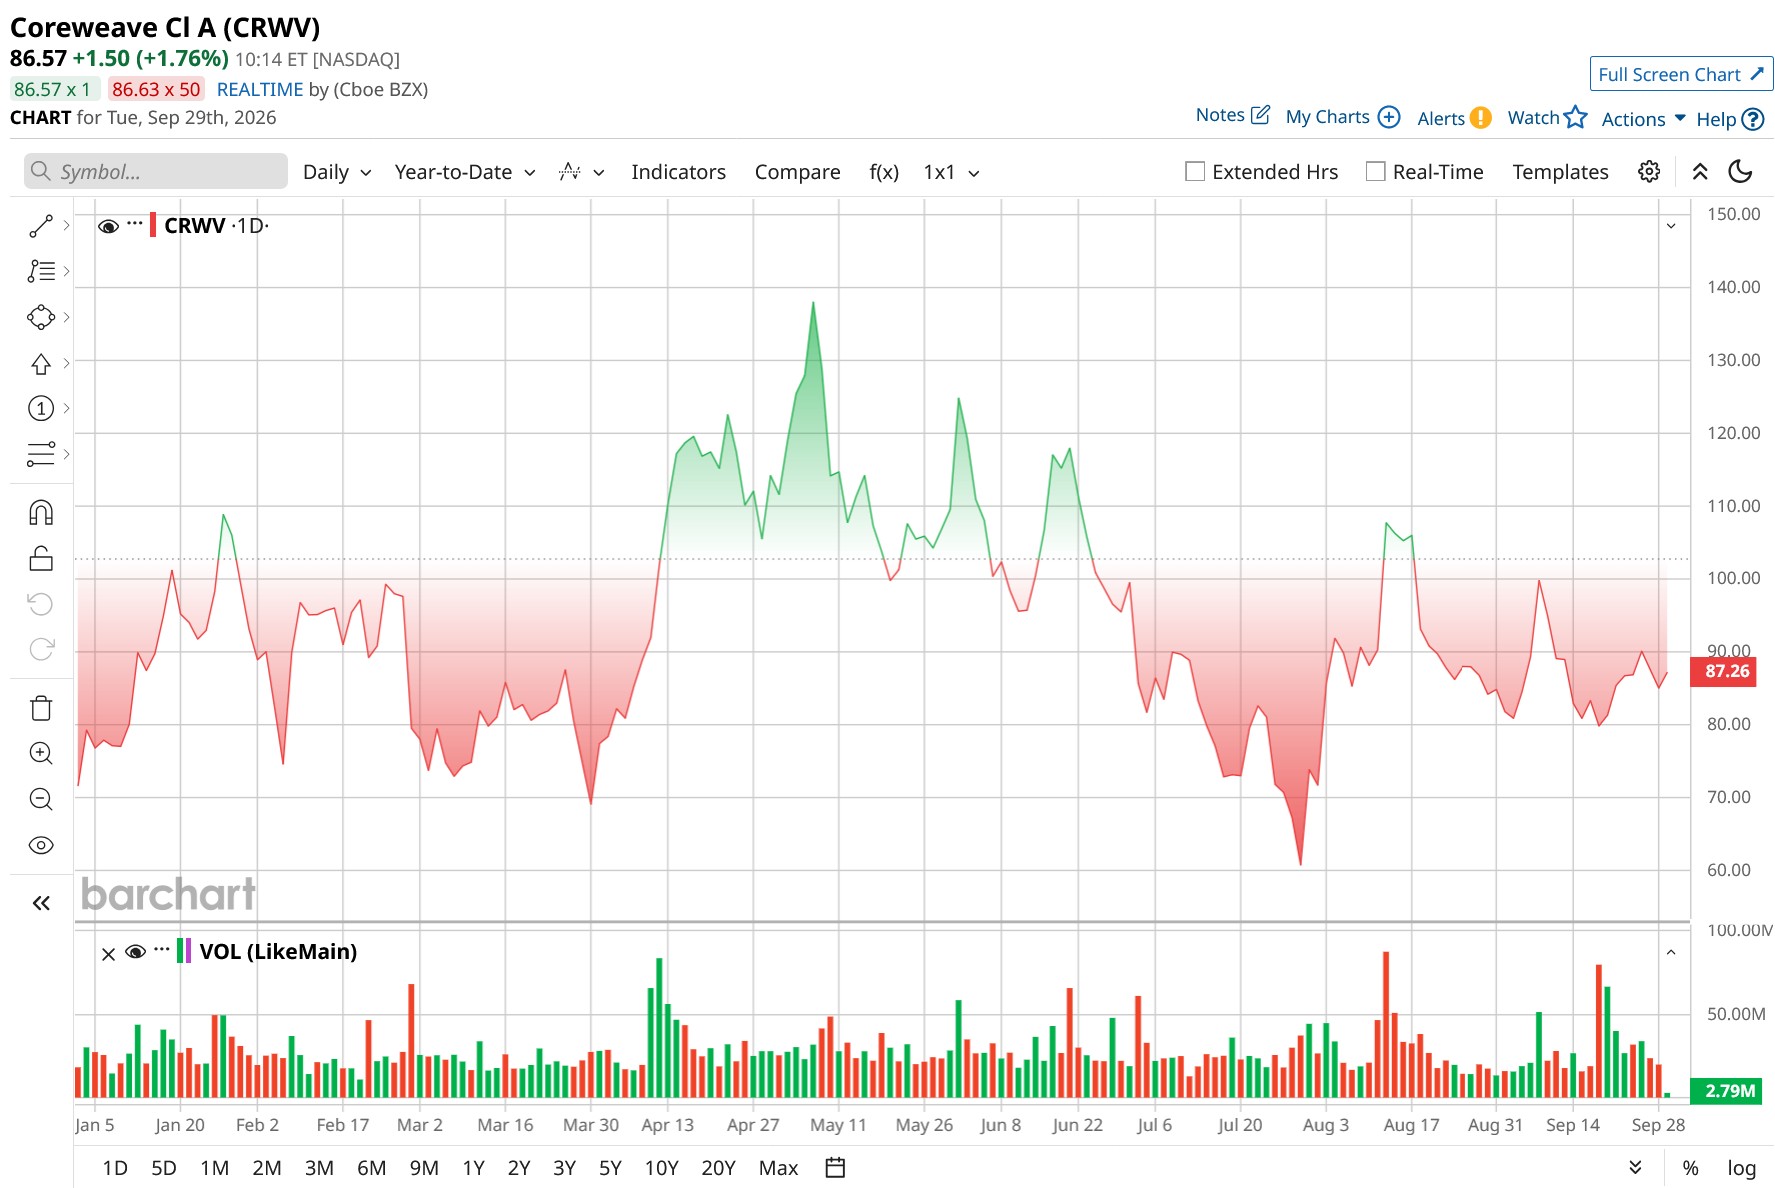
CoreWeave has a complex price chart; shares have climbed about 21% year-to-date (YTD), but the path has been anything but smooth.
CRWV stock is down 9% in the past three months as it has faced pressure from heavy borrowing, enormous capital expenditures, and the possibility that AI infrastructure spending could cool. At the same time, revenue growth and the company’s massive contracted backlog have helped support the shares.
JPMorgan’s latest call puts the focus back on a different question: How much pricing power can CoreWeave capture as customers compete for scarce AI computing capacity?
That could act as a catalyst because stronger pricing could allow the company to generate more revenue from its existing infrastructure while improving margins.
JPMorgan Sees a Pricing Power Shift
This is the key part of the upgrade. JPMorgan analyst Samik Chatterjee said compute pricing has improved during 2026, creating a more supportive backdrop for CoreWeave. The company raised prices on roughly 25% of its products in July, while competitors such as Nebius have also moved prices higher.
Short-term contracts offered by rivals are now reportedly priced at nearly three times CoreWeave’s rates on longer-term agreements. That gap could give CoreWeave an opportunity to shift more capacity toward shorter contracts carrying higher prices.
The company also completed a $5.5 billion delayed-draw term loan in August, giving it additional financing flexibility as it expands its infrastructure.
That does not remove the company’s capital needs. However, if higher prices translate into faster revenue growth and better margins, investors may start viewing its spending through a different lens.
Moreover, CoreWeave’s recent partnership with Harell Data also adds to that story. Harell plans to use CoreWeave Cloud for AI training, fine-tuning, and inference workloads using Nvidia A100 and Hopper GPUs, expanding the company’s exposure to specialized enterprise AI demand.
Q2 Results Show Both Growth and Risk
CoreWeave's recent quarter results highlighted why the stock remains such a closely watched AI infrastructure name.
In Q2 2026, Revenue boosted to $2.575 billion, marking a 112% increase year-over-year (YoY), while revenue backlog jumped 246% to $104 billion. More importantly, Adjusted EBITDA doubled to $1.51 billion, showing the impact of scale.
But the balance sheet remains a major part of the story. Net loss widened to $626 million from $290 million a year earlier, while interest expense reached $640 million. Free cash flow was negative $5.7 billion after $9.4 billion of capital expenditures.
Cash and equivalents totaled $5.524 billion, while active power capacity reached 1.5 gigawatts and contracted power stood at 3.7 gigawatts.
CoreWeave expects third-quarter revenue of $3.45 billion to $3.6 billion and raised full-year revenue guidance to $12.4 billion to $13.2 billion. It also expects to exit 2026 with an annualized revenue run rate of $18.5 billion to $19.5 billion.
Wall Street Remains Divided on CRWV
The positive pricing outlook for CRWV is set to bolster growth in both revenues and margins for JPMorgan, says its CEO Chatterjee. Analyst Karl Keirstead noted UBS's positive $120 outlook based on strong sales of AI products and rising revenue per gigawatt, which the bank initiated coverage with a “Buy” rating.
Rosenblatt has a $250 estimate, while Rothschild & Co. had coverage initiated with a “Sell” rating and a $54 estimate. Bernstein's rating for the stock is also a “Sell.”
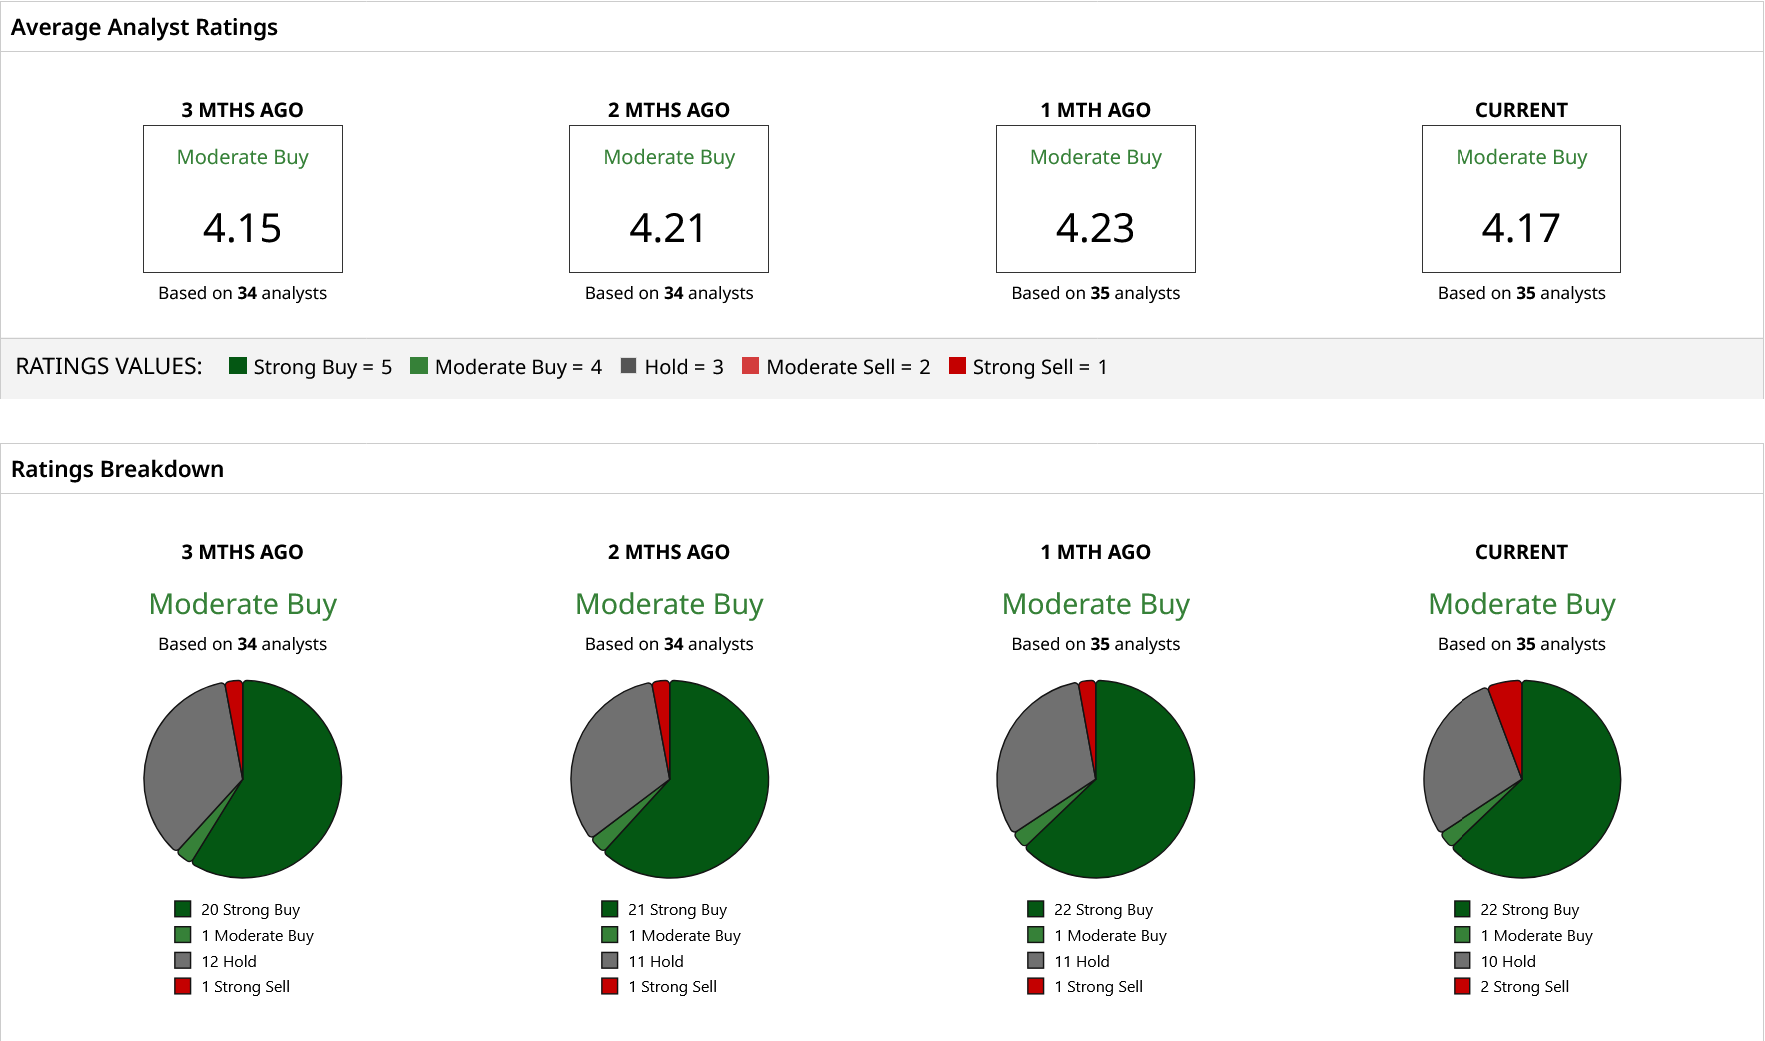
By consensus, it's a solid “Moderate Buy.” The average price target assigned by the Wall Street analysts is $135.83, whereas CRWV stock closed its trade at $85.07 on Sept. 28, which means the stock could climb further by 60%.
In the end, I think the analysts are split on the debate of whether the company will be able to find enough strength in the growing backlog and pricing of AI compute to offset the company's debt, capital expenses, and negative cash flow.
On the date of publication, Nauman Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.