
Wall Street Is Giving Up on Nike. How to Play NKE Ahead of Q1 Earnings
Things have been going from bad to worse for Nike (NKE), and it has been falling from one low to another. The stock hit a new 52-week low of $35.22 on Friday, and extended its year-to-date decline to nearly 44%. This isn't a one-off bad year for the sneaker giant, which has closed in the red for four straight years and looks on track to extend the losing streak to a fifth year.
The stock is down 80% from its November 2021 highs, and in absolute terms it has lost $200 billion in market cap from the peak. Such perennial and frustrating underperformance would test the nerves of even the most patient investors, especially as the S&P 500 Index ($SPX) has delivered double-digit returns in each of the previous three years and is sitting on double-digit gains so far in 2026.
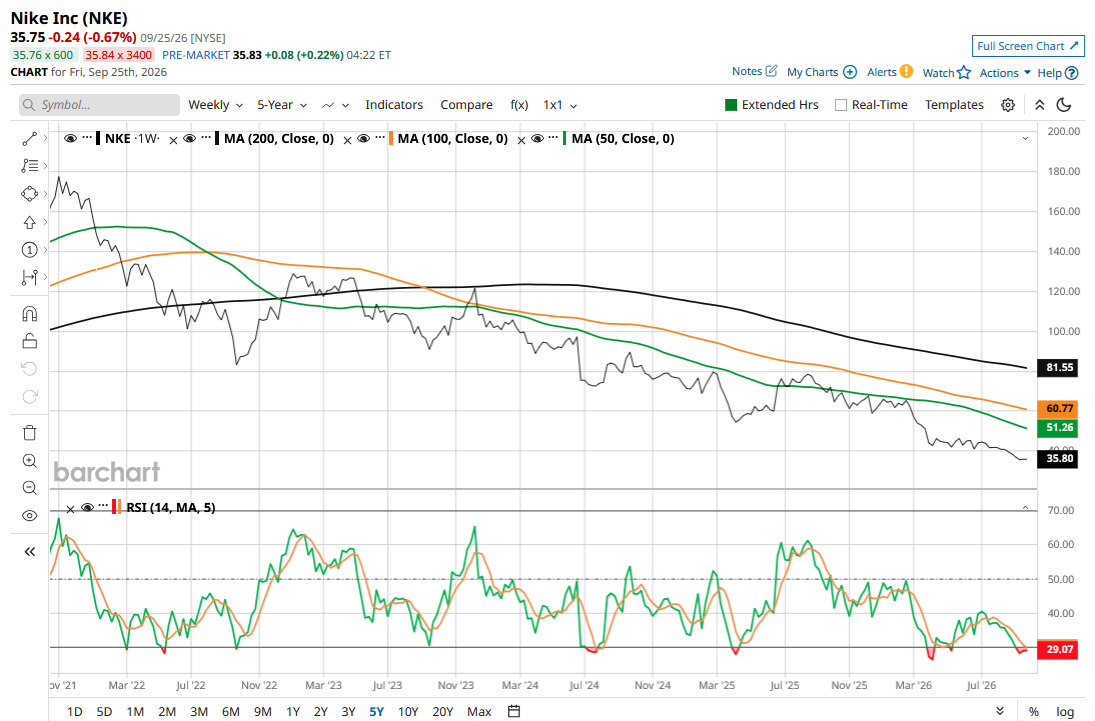
Wall Street Is Mostly Giving Up on Nike
I can go to lengths discussing Nike’s woes, which range from losing focus on third-party retail, slackening on innovation, poorly received marketing campaigns, and some serious headwinds in China where consumers are shunning U.S. brands for homegrown ones. For this article, I won’t go into detail, as I discussed these challenges and how Nike got into this mess in a previous article.
Meanwhile, Wall Street analysts are getting incrementally bearish on Nike ahead of its fiscal Q1 2027 earnings that are scheduled for Thursday, Oct. 1. Oppenheimer, Barclays, Goldman Sachs, UBS, and Stifel Nicholas are among the brokerages that have slashed NKE’s target price over the last two weeks. In that timeframe, it has faced two downgrades as well.
Last week, Bank of America analyst Lorraine Hutchinson downgraded Nike from “Neutral” to "Underperform and trimmed her price target from $47 to $30. Previously, Baird downgraded Nike from “Outperform” to “Neutral” while slashing the target price from $70 to $44. To be fair, Baird analyst Jonathan Komp did not single out Nike and downgraded a total of five names across the industry. These include DICK'S Sporting Goods (DKS), adidas (ADDYY), Rocky Brands (RCKY), and VF Corp (VFC).
Nike now has a consensus rating of “Hold” from the 39 analysts polled by Barchart, while its mean target price of $46.33 is almost 30% higher than current prices.
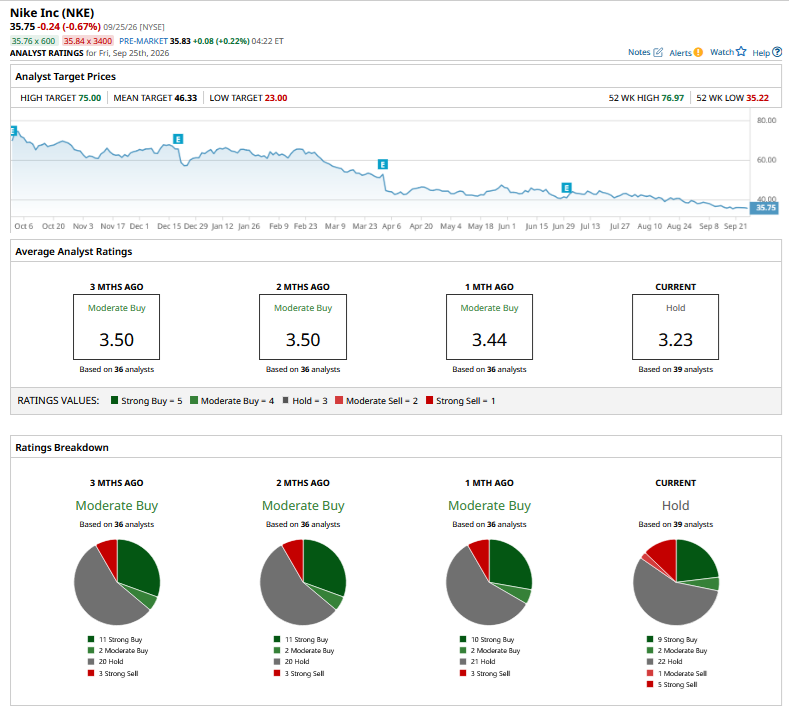
What To Consider Before Buying Nike Stock
Meanwhile, Nike might appear attractive for a couple of reasons. Its dividend yield has risen to 4.6%, which is four times the average S&P 500 Index ($SPX) constituent. From a valuation perspective, it trades at 16.5x its consensus fiscal 2028 earnings per share (EPS). Both these metrics would appear tempting but need to be seen in perspective.
Bank of America slashed Nike’s fiscal year 2026 EPS to $1.43, which is below Street estimates. Importantly, the firm’s estimate implies that Nike’s dividend payout would surpass 100% this fiscal year. In a previous article, I also noted that Nike’s dividends are not sustainable unless its earnings and cash flows improve. However, I don’t expect a cut for now unless an activist investor pushes for one.
As for the forward P/E, it is based on estimates that seem to be factoring in a turnaround in the next fiscal year. However, the wait for the elusive turnaround is getting painfully long, and the expectations for a return to topline growth have been getting pushed forward. The P/E is a function of earnings estimates, which are subject to adjustments, and if anything, brokerages have been lowering Nike’s estimates
Conversely, Nike’s brand has lost some of its sheen and does not have the same pull factor it once did. The macro environment is not getting any better with oil prices holding stubbornly around $100 per barrel. The impact of higher oil prices and the resulting surge in inflation is having an impact on consumer discretionary spending, and things might only worsen if gas prices don’t come down.
Don’t Rush to Buy Nike Stock
In my previous article, I noted that while Nike wasn’t a tempting “buy,” it can be nibbled at. I continue to hold the same view and don’t see the company turning around in a hurry, especially as some of the challenges, particularly the sales decline in the Greater China region, are more of a structural headwind given how that market is evolving.
While I still believe that Nike is near its bottom, given the sector and company-specific headwinds, I would steer clear of the name ahead of the Q1 earnings report.
On the date of publication, Mohit Oberoi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.