
3 NZ Stocks Retail Investors May Revisit As Bond Yields Ease
New Zealand’s surprise cut to government bond issuance has shifted the spotlight back onto domestic equities, as lower expected funding needs and easing 10 year yields brighten the backdrop for selected NZX stocks exposed to this fiscal story. That creates a window that some investors will not want to miss. This article walks through three New Zealand listed companies from our screener that appear well placed under this new bond market setting.
The three domestic stocks that follow are just a small sample of what screens well under this theme. The full filter surfaces 11 more New Zealand listed companies that share similarly compelling investment stories tied to the local market backdrop.
To go beyond this shortlist, head straight into the New Zealand domestic equities (broad NZ stock market exposure) screener to identify, compare, and analyze the broader set of New Zealand equities that match your own conviction and risk settings.
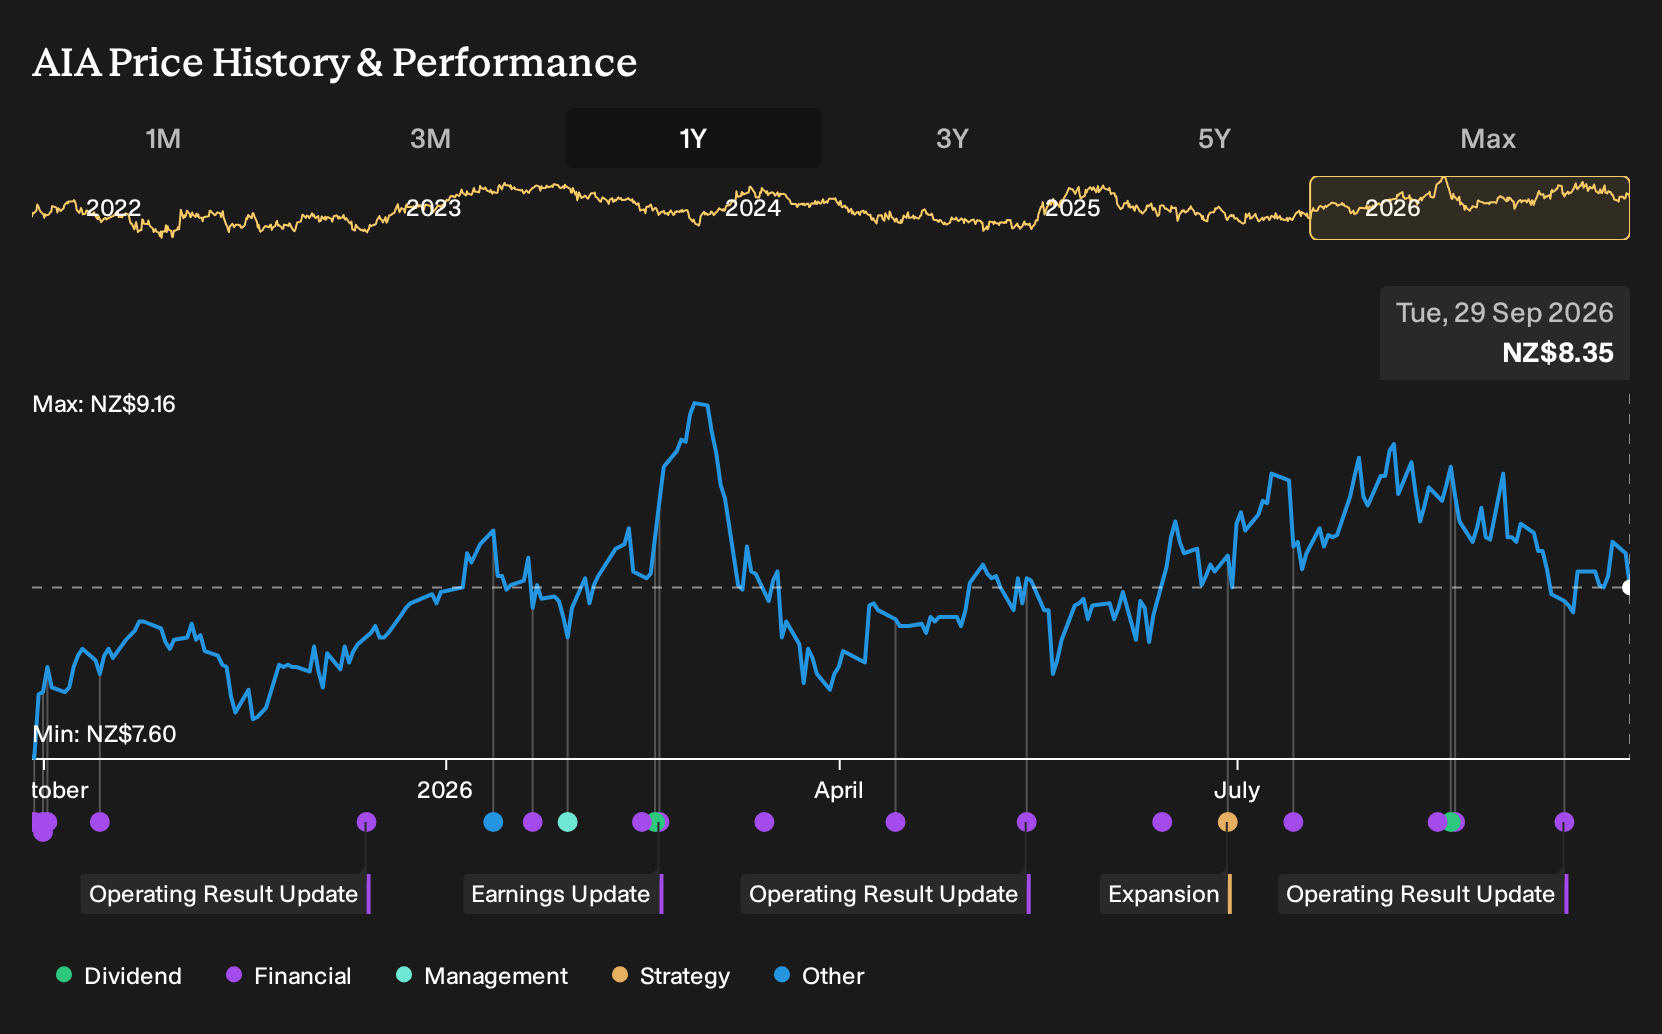
Auckland International Airport (NZSE:AIA)
Auckland International Airport is one of the clearest ways to gain direct exposure to New Zealand’s domestic economy, with its monopoly gateway role linking passenger flows, retail spending, property income and interest rate sensitive funding costs to the same macro forces that shape broad NZ equity returns.
"Domestic jet terminal opens; RAB steps up and earns through 2029 to 2032, turning the capex supercycle into positive FCF and rebuilding the dividend toward FY19 levels."
What happens when that shift in cash generation meets one unresolved pressure on the cost of funding will matter a great deal for shareholders.
Auckland International Airport operates the country’s main gateway hub, earning about $516 million from aeronautical services, $276 million from retail and car parking, and $197 million from property, all in New Zealand, and carries a market value of roughly $14.4b.
That funding pressure is exactly why the full narrative for Auckland International Airport digs into how Auckland International Airport’s capital cycle, risk profile and potential shareholder returns could be decoupling from the headline story.
Meridian Energy (NZSE:MEL)
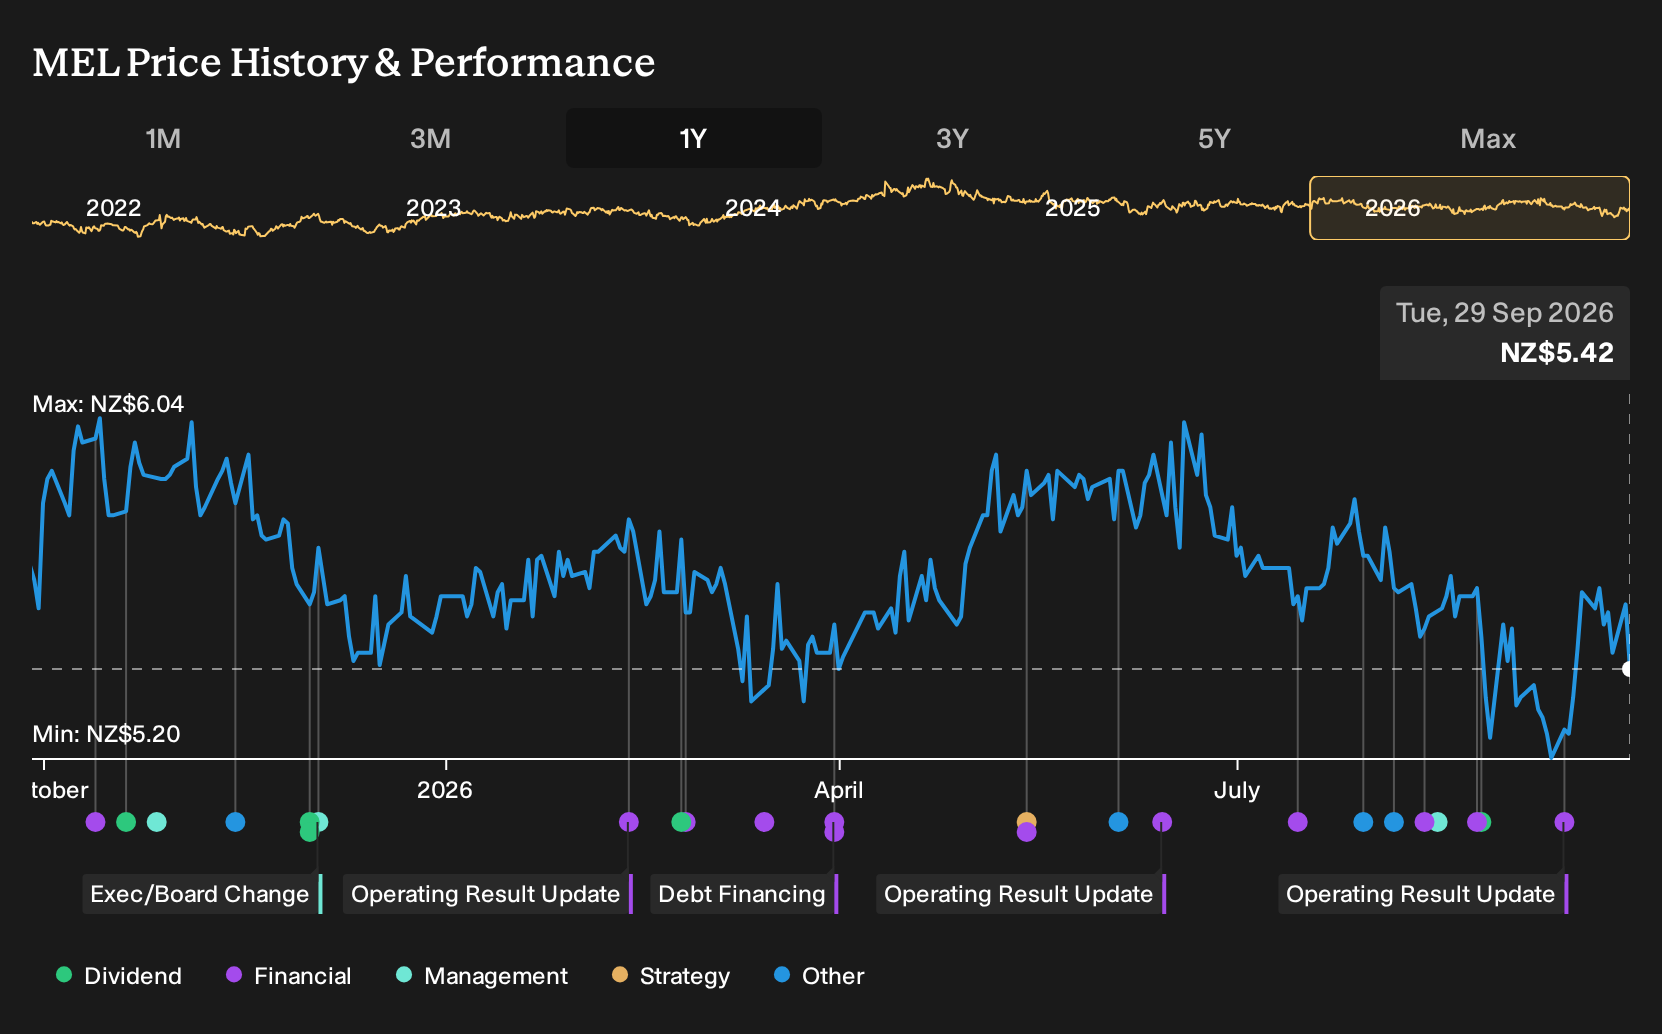
Meridian Energy is one of New Zealand’s largest listed renewables utilities, giving broad domestic equity exposure through hydro, wind, solar and a 100MW battery. It has around $1.7b from NZ retail, $3.5b from NZ wholesale activities and a market value near $14.8b.
Meridian Energy sits at the intersection of New Zealand’s broad equity market exposure and interest rate moves. Its capital-intensive renewable assets, sizeable NZ retail earnings and $14.8b market value are all tied to local funding costs, depending on how one unseen pressure plays out.
That funding squeeze is exactly why the 3 key rewards and 1 important major warning sign could be the key to seeing where Meridian Energy’s risk curve and upside potential might be starting to part ways.
Kiwi Property Group (NZSE:KPG)
Kiwi Property Group gives you direct exposure to New Zealand’s listed property market, with a diversified portfolio of mixed-use, retail and office assets that lives and breathes local funding costs and discount rates. This is exactly what this domestic equities screen is built to surface.
Kiwi Property Group is one of the largest NZX-listed landlords, earning about $177 million from retail-led mixed-use centres, $48 million from offices, $42 million from other assets and $4 million from property management fees, all in New Zealand, and carries a market value near $1.5b.
"The completion of Stage 1 earthworks at Drury and the designation as a listed project under Fast-Track Legislation highlights development progress, which could significantly impact future revenue growth as infrastructure improves."
What happens when that kind of long-dated development pipeline meets a shifting cost of capital will be crucial for margins and equity value.
When that cost of capital story starts to move, the full narrative for Kiwi Property Group shows how Kiwi Property Group’s development pipeline could accelerate value or mask emerging risks.

Curious About What You Might Be Missing?
Fresh ideas move first. Breakout themes, rising momentum and falling laggards can be identified quickly, while they are still under the radar for now, so consider acting while they remain less widely followed.
- Target steadier potential by scanning resilient businesses in the 223 resilient stocks with low risk scores before defensive opportunities get fully reflected in prices and the easier entry points diminish.
- Follow structural demand shifts by tracking infrastructure builders in the 39 power grid technology and infrastructure stocks while the theme is still less visible on many investors’ screens.
- Look for potential future leaders by focusing on early movers in the 619 high quality undiscovered gems before additional institutional interest changes their trading dynamics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com