Qunzhi Consulting: In September, the price of mainstream panel sizes of global displays remained flat across the board, and the market continued the price stability game under a weak balance
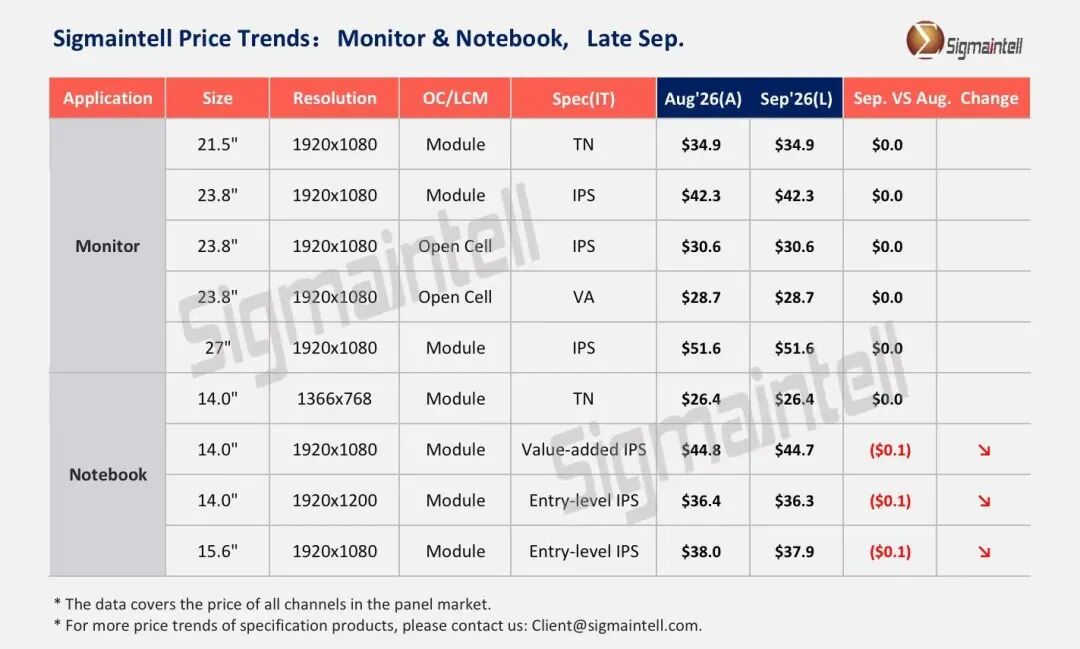
The Zhitong Finance App learned that on September 29, Qunzhi Consulting released the IT panel price trend vane for September 2026 (late version). In September, the price of mainstream panel sizes of global displays remained flat, and the market continued the price stability game under a weak balance. On the demand side, although “Double Eleven” and “Black Five” pre-holiday preparations were gradually released, the traditional peak season recovery fell short of expectations. Commercial demand release was limited, consumer demand momentum was insufficient, and the brand's “on-demand procurement and strict inventory control” strategy remained unchanged; on the supply side, panel factories continued to dynamically control production, G8.X generation line production capacity was adjusted flexibly according to TV and IT demand, and display panel supply maintained a weak balance pattern; on the cost side, the pressure to control brand costs still exists, and the supply of components such as Scaler ICs is strained and delivery times are strained. Long, there are still demands for panel price reduction; while upstream material prices Panel profits continue to rise, causing panel profits to continue to be pressured. Under the support of increased supply concentration and dynamic production control by manufacturers, panel manufacturers have a firm attitude of raising prices; under the game between supply and demand, panel prices still have a stable price foundation. Judging from comprehensive research, Qunzhi Consulting expects prices of mainstream display panels to continue to trend steadily in September.
21.5" FHD, Open Cell & LCM mainstream panel prices remained flat month-on-month in September;
23.8” FHD, Open Cell & LCM mainstream panel prices remained flat month-on-month in September;
27"FHD, Open Cell & LCM mainstream panel prices remained flat month-on-month in September;
Notebook panel
In September, global laptop panel prices ended the standoff in the early stages. Mainstream specifications were completely loosened, and mid-range and high-end specifications continued to be structurally differentiated. On the demand side, due to the demand overdraft effect in the first half of the year, brand procurement tends to be cautious; compounding the structural shortage of consumer GPUs, the brand's stocking momentum has further weakened. Meanwhile, the rise in terminal retail prices has further dampened brand confidence in preparing goods. On the supply side, in order to compete for brand orders and achieve shipping targets, some manufacturers have become aggressive in their pricing strategies, and overall supply and demand in the market have become relaxed; although the cost of panel components continues to rise, the rapid weakening of demand has shifted bargaining power to the demand side. Combining supply and demand, Qunzhi Consulting predicts that the typical price of the notebook panel market will gradually loosen in September, and the performance of various specifications will diverge.
Low-end HD TN: Prices remained flat month-on-month in September;
IPS FHD&FHD+ products: Prices for mainstream specifications and 16:10 entry-level specifications were reduced by 0.1$ month-on-month in September; prices for mid-range and high-end and high-refresh rate panels continued to diverge.