
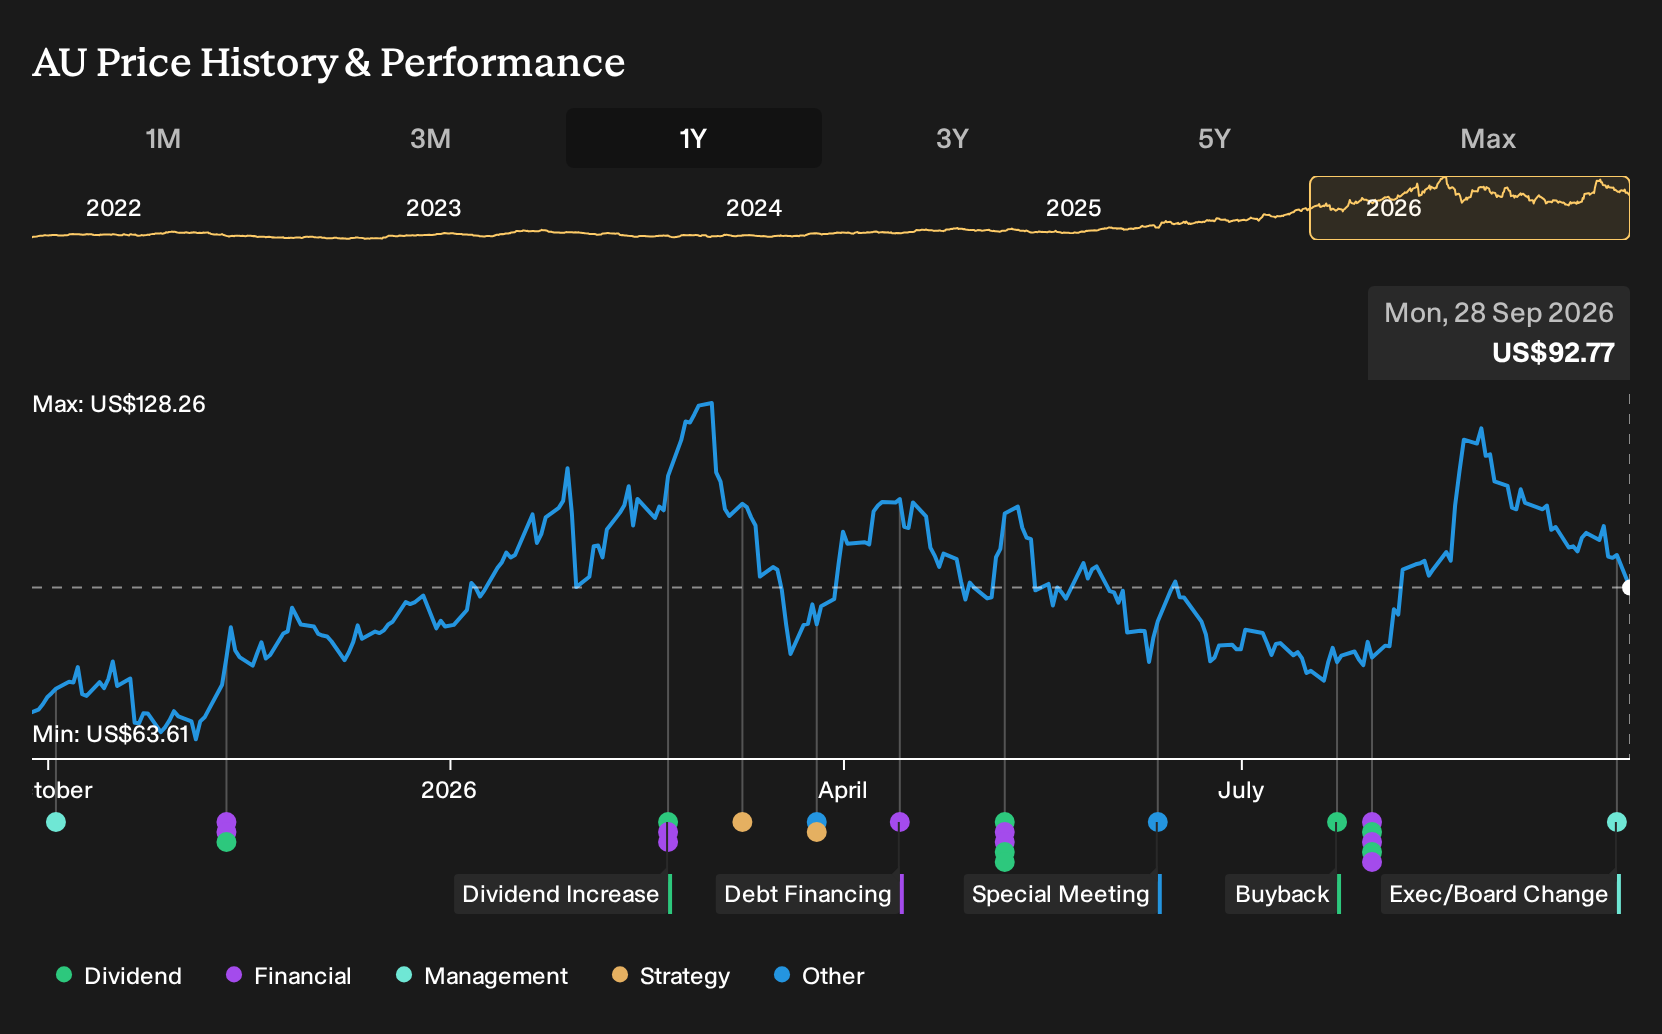
AngloGold Ashanti Stock Sinks After Sector Selloff And Downgrade
- AngloGold Ashanti appointed Paul Graves as an independent non executive director in October 2026, adding deep natural resources, finance, and public company experience to its audit, risk, and sustainability oversight.
- The business is pushing a pipeline of brownfield projects at assets such as Geita, Obuasi, and Siguiri, with fresh capital directed toward mine life extensions and future production potential rather than headline expansion deals.
- We will look at how AngloGold Ashanti's investment narrative is shaped by this operating focus as crude and yields climb.
Scan how AngloGold Ashanti compares with other producers facing the same inflation and rate pressures by reviewing our hand picked 36 elite gold producer stocks in one place.
AngloGold Ashanti Investment Narrative Recap
To own AngloGold Ashanti, you need to believe the brownfield project pipeline can keep production resilient while inflation, royalties, and grade pressures are managed. The near term focus is on execution at Geita, Obuasi, Siguiri, and other assets, with an emphasis on preventing all in sustaining costs from spiraling as crude prices and yields climb.
The main short term swing factor is operational delivery against expectations after the recent quarterly miss on earnings and revenue. The biggest risk remains persistent cost pressure and exposure to higher cost or lower grade ore, which could further squeeze margins. The Paul Graves appointment does not materially change these near term drivers.
The most relevant development is AngloGold Ashanti allocating more capital to brownfield growth, including an approved program at Geita and around US$100 million over three years for expansion. That spending is directed toward mine life extensions and future production potential rather than headline, higher risk new build projects.
This operating plan is directly connected to key catalysts such as volume stability and cost control into the next decade. Execution risk is significant, particularly around permitting and higher government take. If Geita, Obuasi, Siguiri, and Nevada progress broadly in line with plans, the project pipeline remains a central element of the AngloGold Ashanti investment thesis.
AngloGold Ashanti's current earnings sit around US$3.8b, with analyst consensus pointing to roughly flat revenue and profit of US$5.5b by 2029. This implies a US$1.7b earnings increase from today and a revenue line of about US$12.1b in that same forecast year.
Uncover why AngloGold Ashanti's fair value indicates a 22% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One area where opinions really split is the Arthur project in Nevada. Baseline forecasts point to earnings of about US$5.5b on US$12.1b of revenue by 2029, while the most cautious analysts were working off nearer US$5.0b on US$10.4b of sales. With Paul Graves joining AngloGold Ashanti, those pre news views may shift, so treat this as an invitation to compare several angles rather than pick a single “right” story.
Explore 4 other AngloGold Ashanti fair value estimates, including one that suggests it could be worth just $113.12!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AngloGold Ashanti research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AngloGold Ashanti. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AngloGold Ashanti's overall financial health at a glance.
Looking For More Investment Ideas Beyond AngloGold Ashanti?
If AngloGold Ashanti is only one piece of your watchlist, it helps to scan a wider set of opportunities that fit clear, simple filters. Use the Simply Wall St Screener to quickly sort through listed businesses that match the kind of risk, income, or quality profile you want, instead of scrolling through tickers one by one.
- For investors who want quality at a sensible entry point, review our carefully filtered set of 32 high quality undervalued stocks that pair fundamentals with pricing that may appeal to value focused portfolios.
- If capital preservation and steadier profiles matter most to you, consider scanning a curated pool of 30 resilient stocks with low risk scores that score well on our internal risk metrics.
- When you want to surface fresher ideas that are not yet heavily followed, sort through a focused collection of 16 high quality undiscovered gems built around strong financial foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com