
Is Mirror Mix Launch Altering The Investment Case For e.l.f. Beauty (ELF)?
- e.l.f. Beauty, through its e.l.f. Made entertainment arm, released its second original music album "Mirror Mix" with seven emerging artists, distributing the project across Spotify, Apple Music, Roblox and a Genius Open Mic event built around a three day songwriting camp.
- The Mirror Mix release shows e.l.f. Beauty treating marketing as an owned entertainment platform, which could influence future spending efficiency, brand reach and customer acquisition costs rather than acting as a simple promotional campaign.
- We will look at how e.l.f. Beauty's wider investment narrative could be shaped by the Mirror Mix music launch and entertainment push.
Scan how e.l.f. Beauty's entertainment driven push compares with other consumer brands by reviewing our curated list of 16 high quality undiscovered gems, which are building strong followings off the beaten path.
e.l.f. Beauty Investment Narrative Recap
Owning e.l.f. Beauty means believing the business can keep turning cultural buzz into efficient customer acquisition, while expanding globally and scaling newer brands like Rhode and Naturium. The near term focus is whether marketing outlay, including entertainment efforts like Mirror Mix, converts into sustained revenue and earnings progress without eroding profitability.
The biggest operational risk today sits in costs and concentration. Heavy use of China based manufacturing, tariff exposure and a high marketing and SG&A bill leave margins exposed if price increases or mix shifts fail to offset pressures. The Mirror Mix launch does not materially change that balance between risk and reward on its own.
The Mirror Mix project ties directly into one of e.l.f. Beauty’s key perceived catalysts, its ability to keep using culturally relevant marketing to hold customer acquisition costs in check. Distribution of the album across Spotify, Apple Music and Roblox, plus the Genius Open Mic event, keeps the brand present where its audience already spends time.
For shareholders, the real test is execution. If entertainment led marketing supports international traction, DTC stickiness and awareness for acquired labels without meaningfully lifting SG&A as a share of sales, it could support the earnings growth analysts currently model. If spend rises faster than revenue, this type of campaign could instead magnify margin risk.
e.l.f. Beauty's analyst narrative points to revenue of $2.3b and earnings of $191.4 million by 2029, built on an assumed 9.8% yearly gain in sales and an earnings increase of about $131.8 million from $59.6 million today.
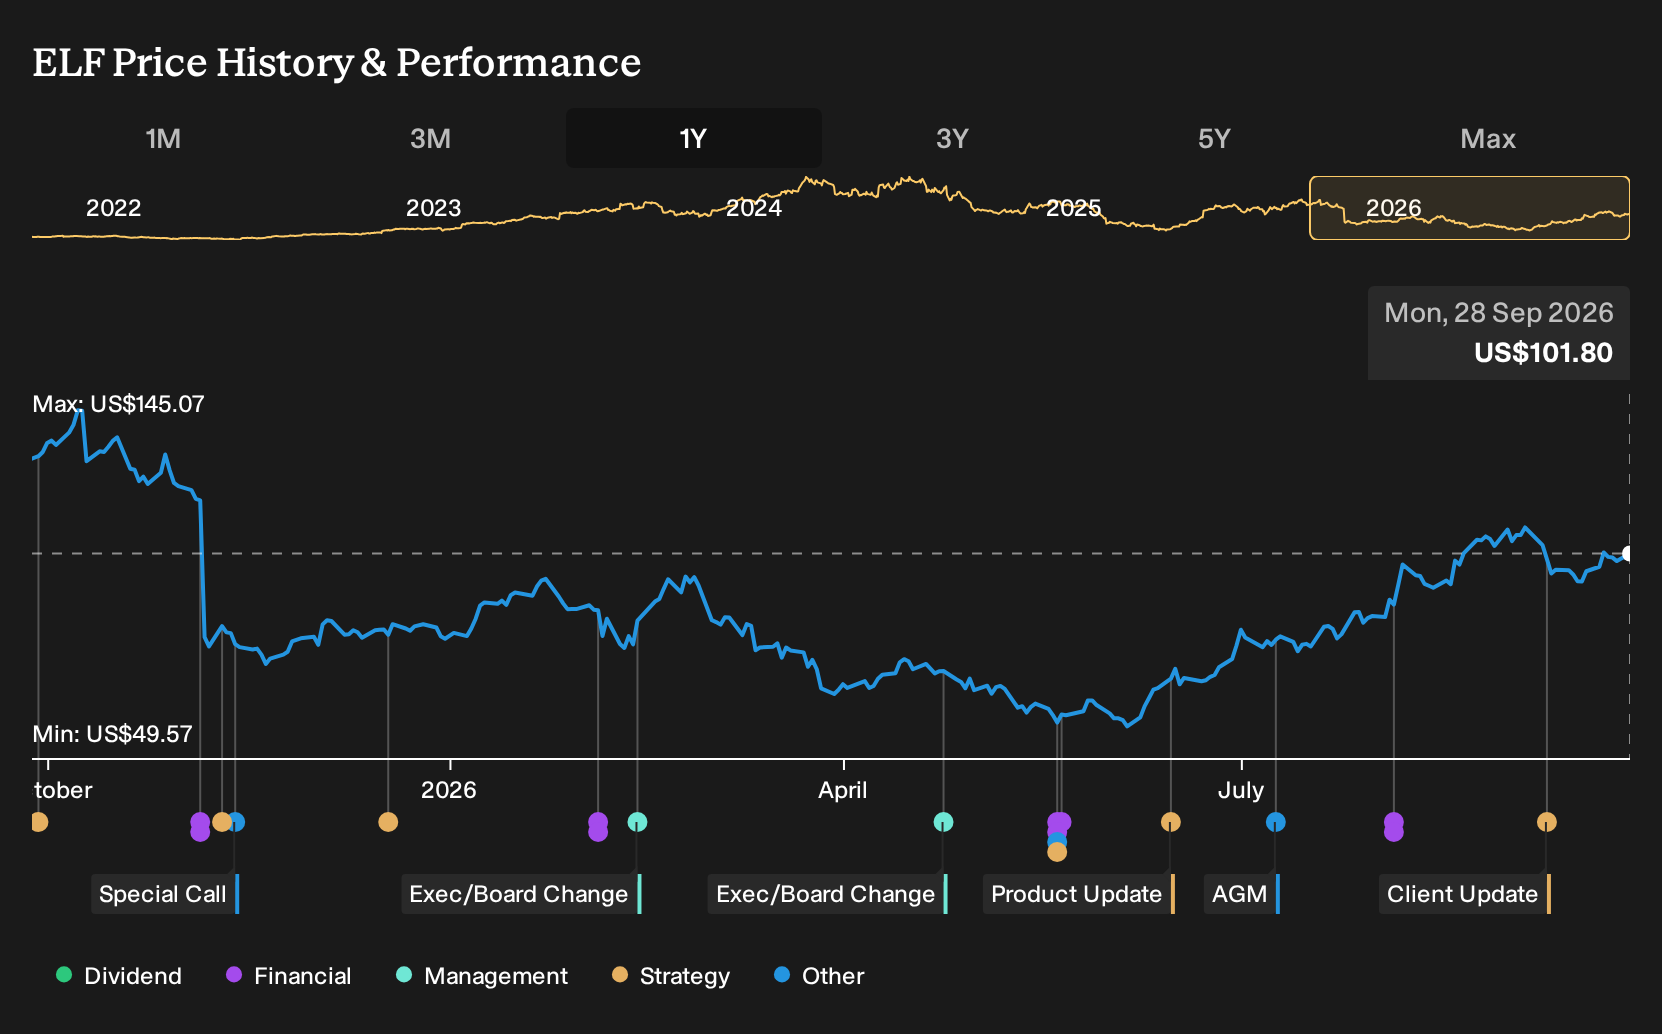
Uncover why e.l.f. Beauty's fair value indicates e.l.f. Beauty is roughly in line with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts frame entertainment projects like Mirror Mix as fuel for faster international expansion. They were already penciling in about 11.8% yearly revenue growth to roughly $2.5b and earnings of $220.2 million by 2029. You may see those views shift once this kind of campaign is fully reflected in fresh models.
Explore 3 other e.l.f. Beauty fair value estimates, including one that suggests as much as 21% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your e.l.f. Beauty research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for e.l.f. Beauty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate e.l.f. Beauty's overall financial health at a glance.
Looking for more e.l.f. Beauty style investment ideas?
If the e.l.f. Beauty story has you thinking about where else strong execution and differentiated positioning might show up, the Simply Wall St Screener can help you widen your watchlist without drowning in noise.
- If you want potential mispricing combined with quality, start with a set of 32 high quality undervalued stocks that pair sturdier fundamentals with appealing price tags.
- If resilience matters most to you, focus on a 30 resilient stocks with low risk scores that screens for businesses with stronger financial foundations and fewer red flags.
- If income is your priority, zero in on 6 dividend fortresses that offer higher yields while still meeting basic balance sheet and earnings checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com