
Alkermes (ALKS) Stock Looks Rich As Fresh ADHD Trial News Lands
Alkermes has delivered a strong multi year share price run, which now collides with fresh clinical news and raises a straightforward question for you as an investor. Is the current valuation supported by the earnings that underpin Alkermes stock today, or has sentiment moved ahead of the profit picture?
- Over the past 3 years Alkermes has returned 45.4%, which puts real weight on whether that gain is backed by the company’s ability to generate and grow earnings.
- Positive Phase 1b results for ADHD drug ALKS 7290 and an ongoing Phase 2 study may support expectations for future revenue and profitability, which feeds directly into how much investors are willing to pay for Alkermes earnings profile.
- Your read on Alkermes is one view; the desks covering it have another. See what analysts think Alkermes's shares could be worth.
The issue now is whether the earnings that Alkermes produces can justify the price investors are currently paying for the stock.
If you want more context around Alkermes and the recent ADHD data, a focused screen of 37 healthcare AI stocks can be a useful second step in your research.
Has Alkermes Run Too Far on Earnings?
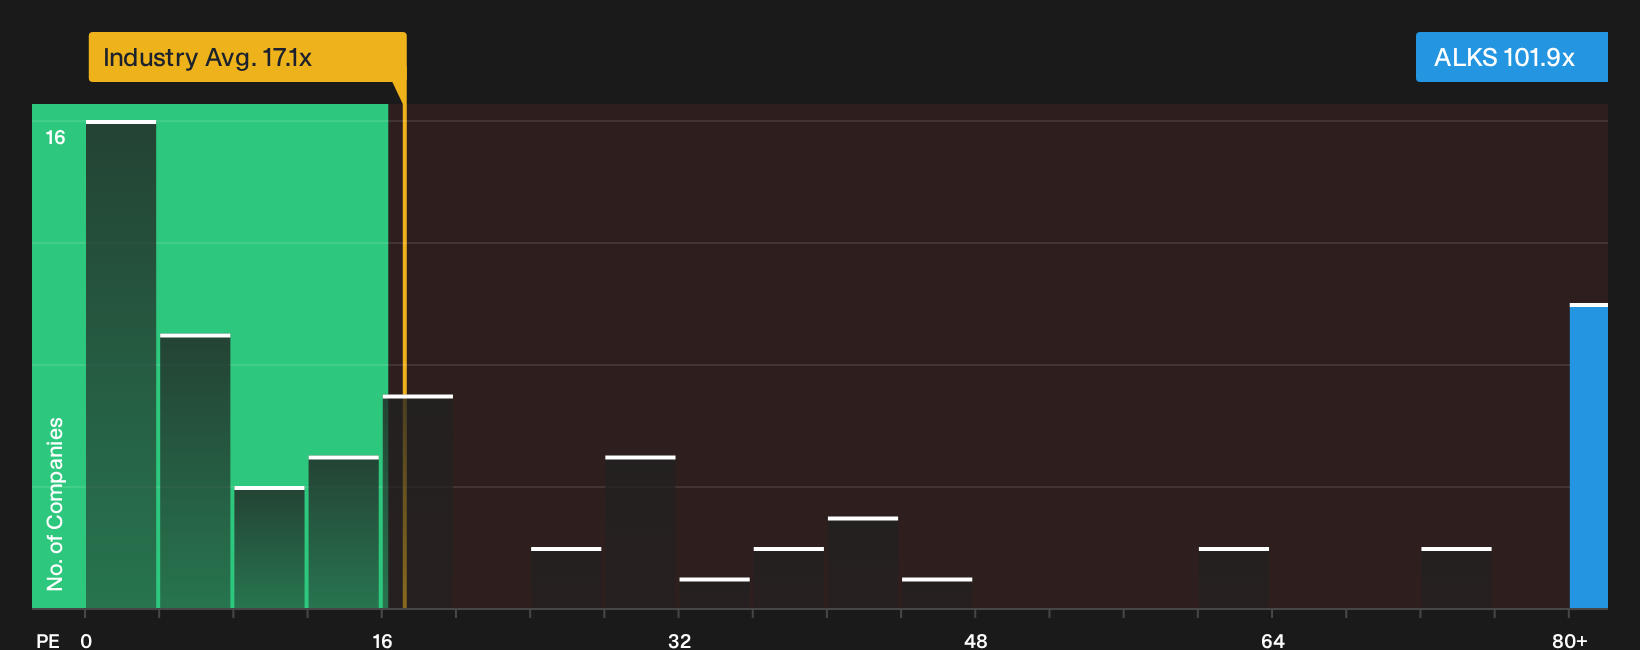
The P/E ratio fits Alkermes because earnings already matter for this stock, not just pipeline promises. On this yardstick, the shares trade on about 101.9x earnings, compared with roughly 17.1x for the wider biotechs sector, and around 90.9x for closer peers. That is a rich headline figure for a drug developer, even within a group where investors often pay up for future pipelines and optionality.
Positive Phase 1b data for ALKS 7290 has clearly lifted enthusiasm, yet the current P/E still sits well above what a tailored fair multiple model would imply based on Alkermes specific growth profile, profitability and risk mix. The premium suggests the market is already baking in a lot of success for the ADHD program and other assets, so you would need to be comfortable that the earnings story can ultimately catch up with a valuation that screens overvalued on this framework. Explore the numbers behind Alkermes's P/E valuation.
The Alkermes Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Alkermes pick up directly from this valuation puzzle and clarify which growth paths, margin structures and earnings profiles would need to occur for Alkermes' stock to be worth materially more or less than it is today. Each scenario assigns a fair value to a clear storyline about catalysts and risks, so you can track over time which version of Alkermes' future appears to be unfolding on the Community page.
Community narratives on Alkermes split between orexin and ADHD potential and concern that a concentrated portfolio and pricing pressure cap the upside.
Bull case: 48% undervalued
"Alkermes' risk-mitigated financial strength, reflected in a debt-free balance sheet with over $1 billion in cash and strong, steady cash flows from proprietary products, greatly increases optionality for high-impact strategic moves such as acquisitions, pipeline acceleration, or share repurchases…"
Discover why this Narrative puts Alkermes at 48% undervalued.
Bear case: 6% overvalued
"Although Alkermes is positioned to benefit from the rising global demand for mental health and substance use disorder treatments and is advancing its orexin agonist portfolio for new neuropsychiatric indications, the company remains heavily reliant on a few core proprietary products, making future revenues vulnerable to unforeseen competitive or regulatory setbacks…"
Explore why this Narrative puts Alkermes at 6% overvalued.
The unanswered issue that could reshape how you view Alkermes
Valuation numbers only tell part of the story, because Alkermes also triggers several caution flags in our research checks that deserve a closer look from you before you place the stock on autopilot. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com