
What Iridium Communications Shares Oscilloquartz Deal Means For Shareholders
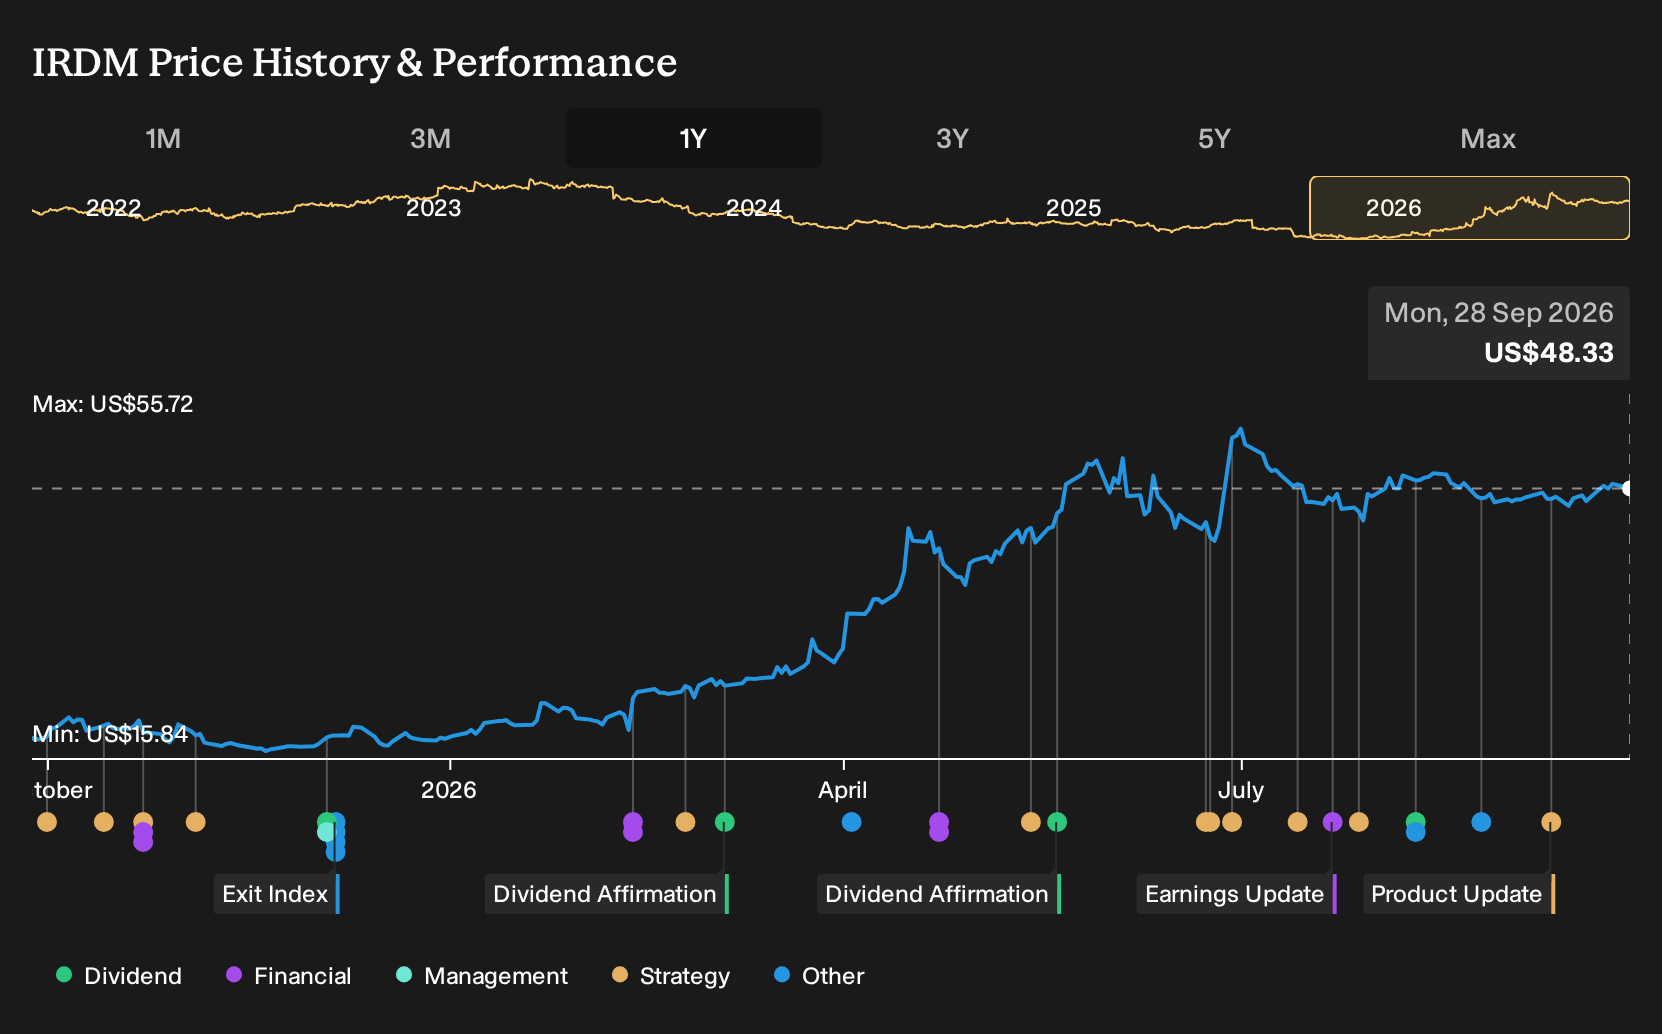
- Oscilloquartz recently announced an expanded phase of its collaboration with Iridium Communications, widening access to Iridium PNT Time, Locate and Navigate services across its synchronization portfolio for critical infrastructure, defense and other GNSS dependent uses.
- The move concentrates Iridium PNT service subscriptions and Oscilloquartz hardware into a single supplier relationship, which can simplify procurement, standardize deployment and potentially strengthen Iridium’s role in assured timing and positioning architectures.
- This article examines how Iridium Communications' investment narrative is influenced by the wider Oscilloquartz integration of its assured PNT services.
Scan how Iridium Communications fits into the broader satellite and critical infrastructure story by reviewing a hand picked set of 30 resilient stocks with low risk scores that may suit a more defensive watchlist.
Iridium Communications Investment Narrative Recap
To own Iridium Communications, you need to believe its satellite network can keep turning specialized services like IoT connectivity and PNT into steady, recurring cash flow despite uneven adoption. The Oscilloquartz expansion sits right in that thesis. It broadens where Iridium PNT can show up in real infrastructure, which can help credibility even if near term revenue impact is modest.
The key short term swing factor still looks like service momentum in higher value segments versus pressure from customers shifting to cheaper backup plans. On the risk side, interest costs are not well covered by earnings and IoT growth has already slowed, so any delay in PNT uptake or new contracts can weigh more heavily on margins.
The latest Oscilloquartz phase is directly tied to Iridium Communications' PNT ambitions. It embeds Iridium PNT Time, Locate and Navigate across a wider set of synchronization products, making Iridium easier to buy and deploy as part of assured timing and positioning stacks. That can support use cases where GPS spoofing or outages are real concerns.
For catalysts, the interesting piece is that analysts already see PNT as an important long term pillar, yet revenue recognition in that line has been uneven and slower than hoped. If this integration helps shorten customer decision cycles or broaden trials into live networks, it can ease some of that adoption risk, even as competition and capital needs remain front of mind.
Iridium Communications' current analyst script points to revenues of US$1.0b and earnings of US$170.7m by 2029, based on a 5.7% yearly revenue growth rate and an earnings increase of about US$77.4m from US$93.3m today.
Uncover why Iridium Communications' fair value indicates a 13% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternate view leans hard into Iridium Communications' PNT upside. The most optimistic analysts were already penciling in US$1.2b of revenue and US$138.6m of earnings by 2029, well above consensus. You can read that as a bet that deals like Oscilloquartz could reset expectations, or as a stretch case worth stress testing yourself.
Explore 5 other Iridium Communications fair value estimates, including one that suggests as much as 72% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Iridium Communications research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Iridium Communications. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Iridium Communications' overall financial health at a glance.
Looking For More Ideas Beyond Iridium Communications?
Once you have formed a view on Iridium Communications, it can help to line it up against a few very different types of opportunities. That way you are comparing this satellite specialist with stocks that offer different risk, income and balance sheet profiles.
- For potential mispriced opportunities with strong underlying quality, review a curated set of 32 high quality undervalued stocks that could broaden your watchlist beyond Iridium Communications.
- If income is a priority, scan a pool of 6 dividend fortresses that might appeal if you want yield plus resilience from more established businesses.
- When capital preservation matters most, focus on a list of solid balance sheet and fundamentals (25 results) to see companies where financial strength is front and center.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com