
3 European Growth Stocks With Up To 33% Insider Ownership
The European market has recently experienced a positive shift, with the pan-European STOXX Europe 600 Index rising by 0.50% amid optimism about improving economic conditions and advancements in AI technology. However, concerns about high energy prices and potential monetary policy tightening by the European Central Bank continue to loom over investors. In this environment, growth companies with substantial insider ownership can offer unique insights into business confidence and alignment of interests between management and shareholders.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.8% |
| MilDef Group (OM:MILDEF) | 10.3% | 32.5% |
| Kuros Biosciences (SWX:KURN) | 25.9% | 60.3% |
| KebNi (OM:KEBNI B) | 16.3% | 103.8% |
| Gold Road International (OB:GOLDR) | 35.9% | 89.8% |
| Clavister Holding AB (publ.) (OM:CLAV) | 20.5% | 41.1% |
| CD Projekt Red (WSE:CDR) | 35.2% | 53.9% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.2% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 30% |
Let's uncover some gems from our specialized screener.
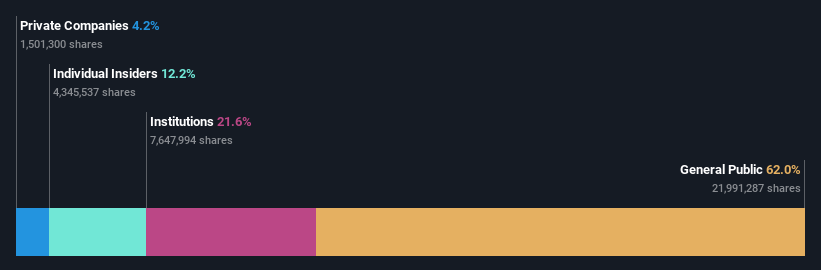
Bittium Oyj (HLSE:BITTI)
Simply Wall St Growth Rating: ★★★★★★
Overview: Bittium Oyj offers communications and connectivity solutions across Finland, Europe, the Americas, and Asia with a market cap of €1.32 billion.
Operations: The company's revenue is primarily derived from Defense & Security (€102.41 million), followed by Medical (€19.87 million) and Engineering Services (€12.80 million).
Insider Ownership: 17.9%
Bittium Oyj, with its substantial insider ownership, is positioned for robust growth in Europe. Recent strategic alliances, such as the one with Safran Electronics & Defense SAS, highlight Bittium's commitment to expanding its tactical communications solutions. The company's revenue and earnings are projected to grow significantly faster than the Finnish market, supported by strong recent financial performance and new product launches like the Bittium Faros Pro ECG device. Despite a volatile share price recently, it trades close to its estimated fair value.
- Click to explore a detailed breakdown of our findings in Bittium Oyj's earnings growth report.
- Our comprehensive valuation report raises the possibility that Bittium Oyj is priced higher than what may be justified by its financials.
Ratos (OM:RATO B)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Ratos AB (publ) is a private equity firm that focuses on buyouts, turnarounds, add-on acquisitions, and small to middle market transactions, with a market cap of approximately SEK12.27 billion.
Operations: Ratos generates revenue through its private equity activities, which include buyouts, turnarounds, add-on acquisitions, and transactions in the small to middle market sector.
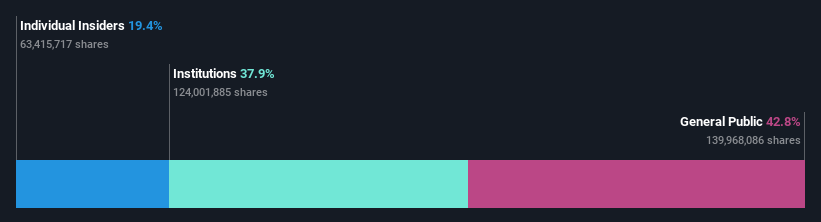
Insider Ownership: 22.1%
Ratos AB, with significant insider ownership, shows potential for growth in Europe. Despite a recent decline in net income to SEK 1.04 billion for Q2 2026 from SEK 3.23 billion a year ago, its earnings per share from continuing operations improved significantly. Revenue is forecast to grow faster than the Swedish market average, and earnings are expected to increase by over 37% annually. However, the dividend coverage remains weak and recent executive changes could impact stability.
- Get an in-depth perspective on Ratos' performance by reading our analyst estimates report here.
- Our valuation report here indicates Ratos may be undervalued.
Hypoport (XTRA:HYQ)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Hypoport SE develops, operates, and markets technology platforms for the credit, housing, and insurance industries in Germany with a market cap of €488.21 million.
Operations: The company's revenue is derived from its Financing Platforms (€83.20 million), Insurance Platforms (€66.97 million), and Real Estate & Mortgage Platforms (€466.36 million) segments in Germany.
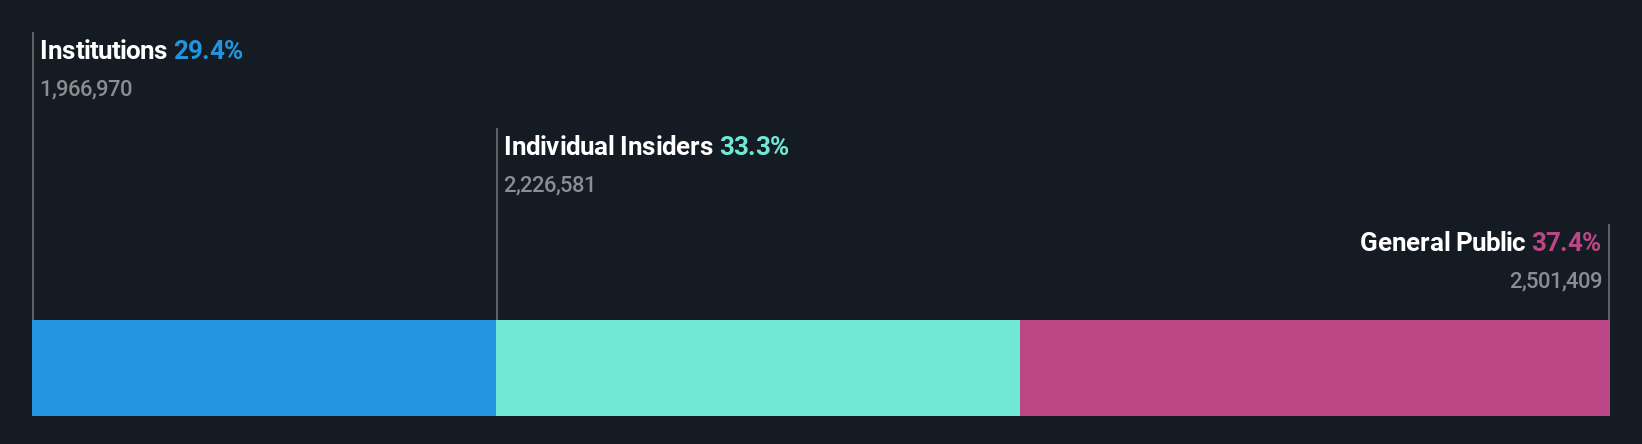
Insider Ownership: 33.6%
Hypoport SE, with strong insider ownership, demonstrates growth potential in Europe. The company reported increased earnings for H1 2026, with net income rising to €12.98 million from €10.32 million a year ago. Despite trading below estimated fair value, analysts expect the stock price to rise significantly. Revenue is forecasted to grow faster than the German market average at 9.3% annually, while earnings are projected to increase by 21.4% per year over the next three years.
- Click here to discover the nuances of Hypoport with our detailed analytical future growth report.
- Our valuation report unveils the possibility Hypoport's shares may be trading at a discount.
Key Takeaways
- Take a closer look at our Fast Growing European Companies With High Insider Ownership list of 212 companies by clicking here.
- Interested In Other Possibilities? Rare earth metals are an input to most high-tech devices, military and defence systems and electric vehicles. The global race is on to secure supply of these critical minerals. Beat the pack to uncover the 36 best rare earth metal stocks of the very few that mine this essential strategic resource.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com