
Contract Wins Could Be A Game Changer For Vallourec Stock (ENXTPA:VK)
- Vallourec reported two sizeable contract wins, providing around 3,000 tons of premium casing for the Prinos CO2 storage project in Greece and roughly 15,000 tons of sour service line pipe plus thermal insulation for Petrobras’s Sepia 2 development in Brazil.
- These awards widen Vallourec’s exposure to both carbon storage infrastructure and ultra deepwater oil and gas, which matters for capacity planning, product mix, and future order visibility.
- The next step is to see how Vallourec’s investment narrative is shaped by this fresh contract momentum in premium tubular solutions.
Scan how contract driven momentum, like Vallourec’s, could play out in other infrastructure suppliers by checking the 39 power grid technology and infrastructure stocks in the same broader energy build out theme.
Vallourec Investment Narrative Recap
To own Vallourec, you need to believe the premium tubular story holds in both traditional oil and gas and newer areas like carbon storage. The short term swing factor is still order quality and pricing in core OCTG and line pipe, where capacity utilization and mix decide how much of the cost work in Brazil and Europe shows up in margins.
The biggest immediate risk is that this capital intensive footprint hits a soft patch in spending from exploration and production clients, while FX and pricing pressure from low cost competitors squeeze profitability. The new Petrobras and Prinos wins help order visibility but do not remove that cyclical exposure.
The Sepia 2 line pipe and coating contract with Subsea7 looks most relevant right now. It uses Vallourec’s Jeceaba mill and Serra coating unit heavily, so it tests whether the cost and operational improvements in Brazil can hold up on a complex, high spec deepwater job at meaningful volume.
For catalysts, investors will probably watch execution on Sepia 2 for schedule discipline, coating performance and any commentary on pricing versus input costs. Successful delivery would support the narrative of structurally higher margins and strong cash generation, while delays or overruns would reinforce the concern around high fixed costs and project risk.
Vallourec's current analyst script points to revenue of $5.7 billion and earnings of $713.1 million by 2029. That profile assumes yearly revenue growth of 10.7% and an earnings increase of about $309.6 million from $403.5 million today.
Uncover why Vallourec's fair value indicates a 34% potential upside to its current price, which could narrow quickly.
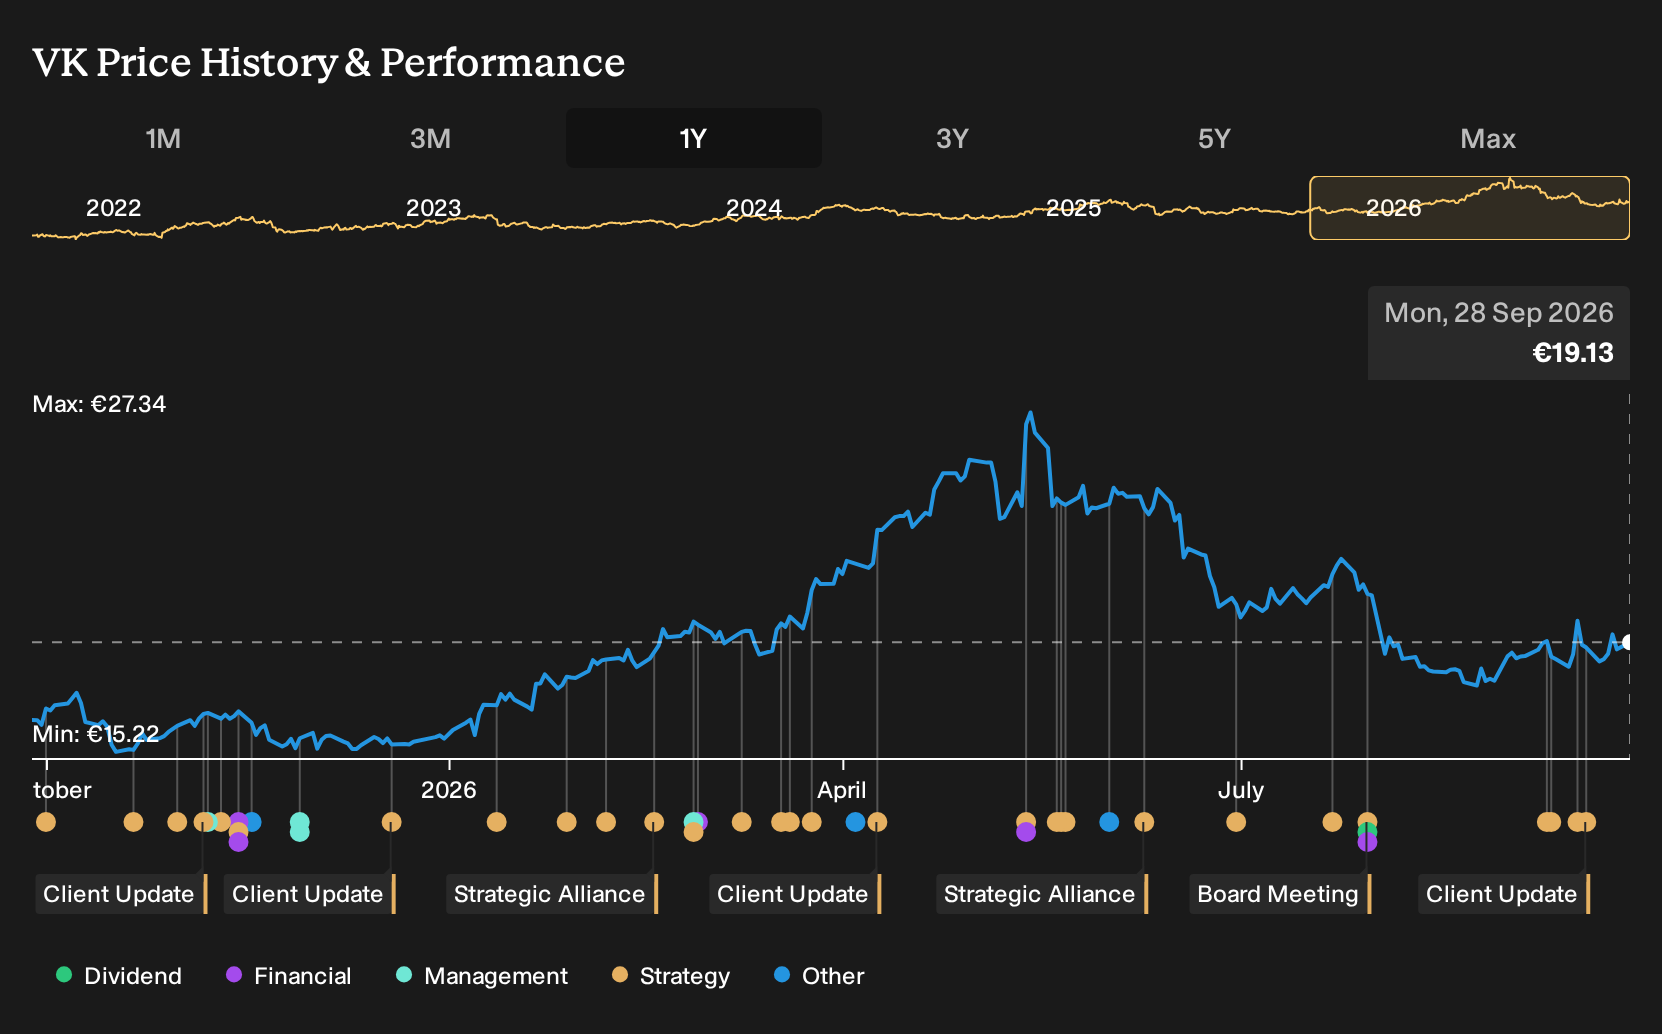
Exploring Other Perspectives
One alternate angle on Vallourec focuses on the risk that heavy shareholder payouts could crimp reinvestment. The most cautious analysts were penciling in around $5.1b of 2029 revenue and $638.9 million of earnings before this Petrobras and Prinos news. That is a more muted story. It shows how far opinions can differ and why it helps to compare several narratives before deciding how these new contracts might reshape your own view.
Explore 3 other Vallourec fair value estimates, including one that suggests it could be worth just €21.77.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Vallourec research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Vallourec. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vallourec's overall financial health at a glance.
Looking for more Vallourec style investment ideas?
If Vallourec has put premium industrial exposure on your radar, it can help to widen the search and see how other businesses stack up on quality, valuation, and resilience using the Simply Wall St Screener.
- For investors who want quality and value in the same place, scan a curated set of 196 high quality undervalued stocks that pair stronger fundamentals with more modest pricing.
- If balance sheet strength matters most to you, start with a list of solid balance sheet and fundamentals (202 results) and see which companies carry less financial strain while still offering room for growth.
- Those hunting for resilient performers with fewer red flags can review 221 resilient stocks with low risk scores that may better match a more cautious risk profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com