
How A 4.9% Rate Increase At Old Dominion Freight Line Stock Has Changed Its Investment Story
- Old Dominion Freight Line has implemented a 4.9% general rate increase effective October 5, 2026, aiming to offset higher operating costs and support spending on its service network and technology.
- The broad rate adjustment highlights how Old Dominion Freight Line is leaning on pricing to manage wage, real estate, equipment, and technology expenses while seeking to protect service quality.
- We will now look at how Old Dominion Freight Line's general rate increase could reshape its investment narrative around pricing power.
Compare Old Dominion Freight Line's pricing power and boardroom refresh with other freight and logistics stocks that also pair disciplined rate moves with resilient balance sheets using our curated list of solid balance sheet and fundamentals (25 results)
Old Dominion Freight Line Investment Narrative Recap
To own Old Dominion Freight Line, you need to believe that disciplined pricing and tight cost control can offset freight softness and higher overheads. The 4.9% rate increase is aimed at protecting service levels and funding the network, so the near term catalyst remains whether yields hold without pushing too much volume to rivals.
The biggest short term risk is that domestic demand stays weak and LTL tons per day remain under pressure, which would keep the operating ratio elevated. The recent board change and pricing update do not materially change that tension between volume and yield, but they keep the focus squarely on execution.
The most relevant update for that execution story is the board refresh. Old Dominion Freight Line added Worthing Jackman, who ran Waste Connections and has deep experience in asset heavy services, while John Kasarda retired with no reported dispute. The new director joins both the governance and nomination committee and the talent and compensation committee.
For you, that matters less as a corporate formality and more as a potential support for pricing discipline, capital allocation, and incentive design around operating efficiency. Board independence was already described as solid. A fresh independent voice with operating and finance credentials may help management stay aligned with the current catalysts and cost risks.
Old Dominion Freight Line is currently framed around analysts expecting revenue to compound at 8.1% a year, with earnings projected to rise from US$1.1b today to US$1.6b by 2029. This increase of about US$500m underpins a forecast for US$7.1b of revenue and US$1.6b of profit in 2029.
Uncover why Old Dominion Freight Line's fair value indicates a 30% potential upside to its current price that could narrow quickly.
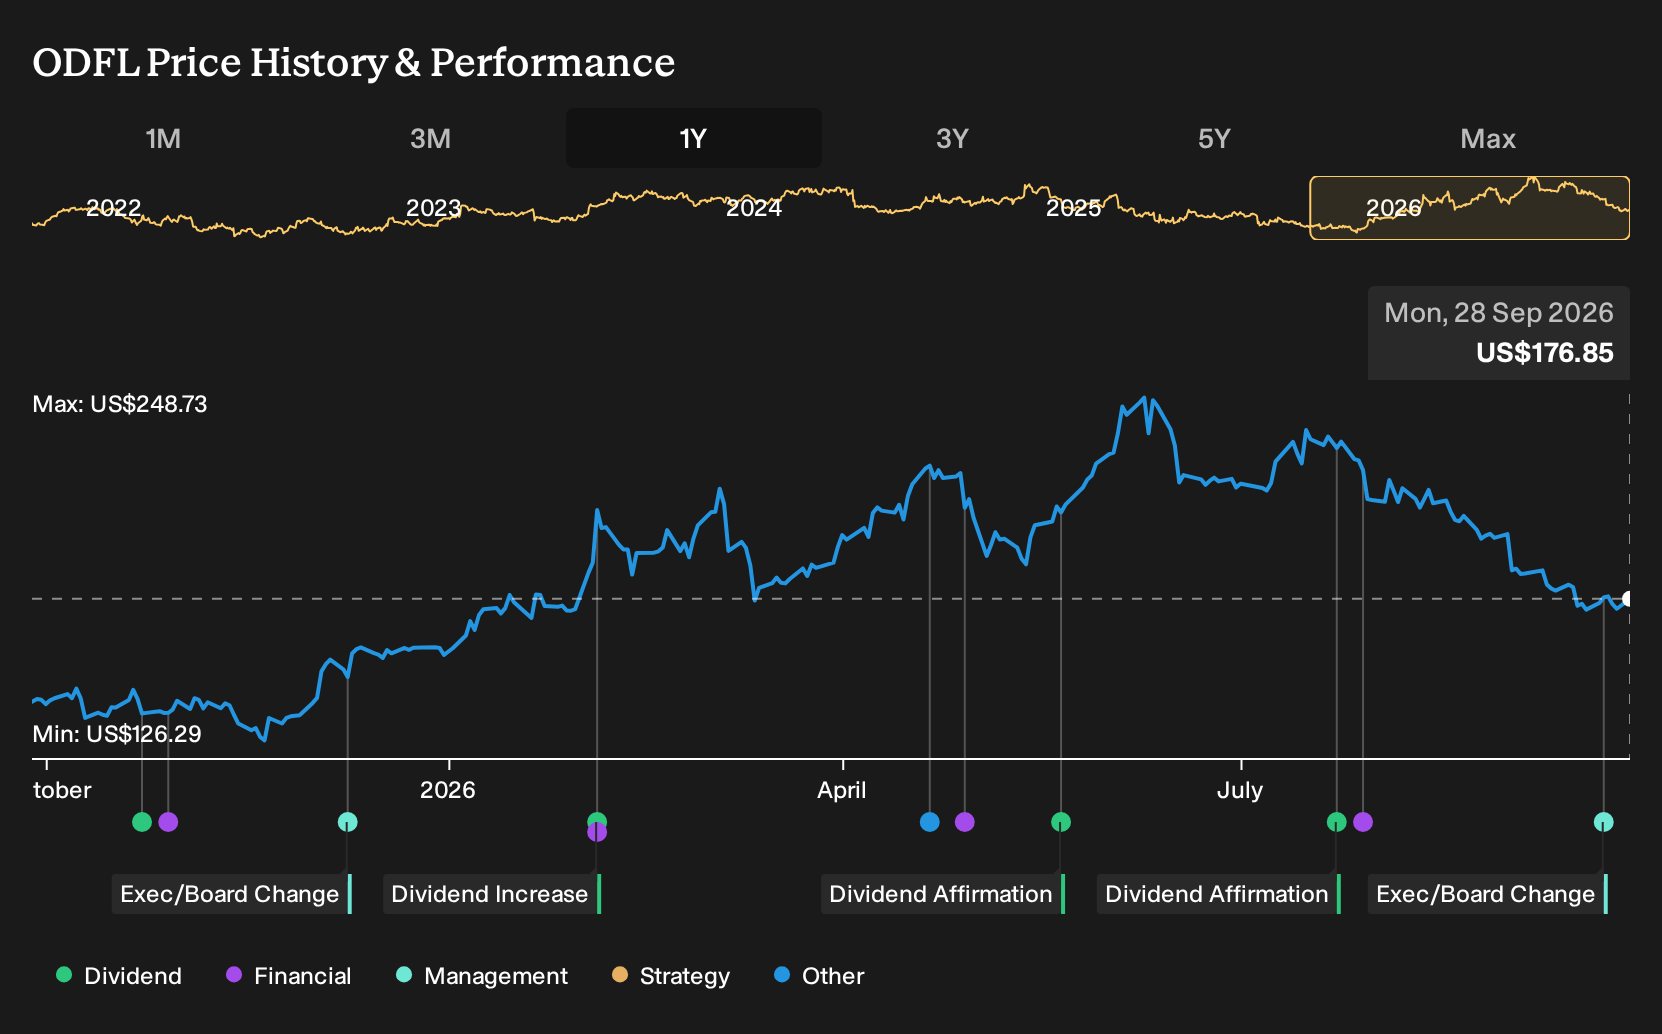
Exploring Other Perspectives
Some analysts see Old Dominion Freight Line through a much more cautious lens. The most pessimistic group expected only 6.8% annual revenue growth and about US$6.6b of revenue by 2029 before this board change and rate increase. That view assumes softer freight and a lower P/E, so use it as a contrast and explore both sides.
Explore 4 other Old Dominion Freight Line fair value estimates, including one that indicates up to 9% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Old Dominion Freight Line research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Old Dominion Freight Line. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Old Dominion Freight Line's overall financial health at a glance.
Looking For More Ideas Beyond Old Dominion Freight Line?
If the Old Dominion Freight Line story has sharpened your focus on pricing power and balance sheet strength, it can help to widen the lens and compare it with other businesses that share similar financial traits.
- If you want potential mispricing opportunities with strong fundamentals, check out our curated 33 high quality undervalued stocks that might fit your return and quality criteria.
- For investors who see income as a core part of total returns, scan through a hand picked set of 6 dividend fortresses that aim to combine yield with resilience.
- When capital preservation is at the top of your checklist, start with our focused group of 30 resilient stocks with low risk scores that score well on financial strength and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com