
Adeia (ADEA) Names Dipti Vachani CEO On A Bullish Fair Value Narrative
Leadership change at Adeia and what it means for investors
Adeia (ADEA) is entering a leadership transition after appointing semiconductor veteran Dipti Vachani as CEO and board member. She succeeds Paul E. Davis, who is stepping back for personal reasons.
Recent trading reflects a mixed picture for Adeia. The share price is down about 24% over the past 90 days, yet the year-to-date share price return of 41.75% sits alongside a 1-year total shareholder return of 50.47% and a 5-year total shareholder return of 458.95%. This points to strong longer term momentum despite the pullback around leadership changes.
Scan how other semiconductor and IP licensing players with recurring revenue models compare with Adeia using our hand picked 84 AI infrastructure stocks for this theme.
Adeia now trades at about $24.92 after the pullback, while analyst targets cluster near $43 and intrinsic estimates land slightly below spot. So where does a reasonable fair value actually fall in that spread?
Most Popular Narrative: 42% Undervalued
On the most followed view of Adeia, a fair value of $43 sits well above the recent $24.92 close, so the gap between price and narrative is wide.
Adeia is capitalizing on the ongoing proliferation of connected devices and the exponential surge in data generation, which is increasing the need for advanced digital content delivery, storage, and high-performance semiconductor technologies. These trends underpin expanding royalty streams, support sustainable top-line revenue growth, and reinforce long-term earnings stability.
See why 8 investors see Adeia as 42% undervalued.
Result: Fair Value of $43 (UNDERVALUED)
Still, Adeia’s story can change quickly if big licensing deals slip or legal disputes escalate, which could strain both royalty income and profitability expectations.
Find out about the key risks to this Adeia narrative.
Another view on Adeia’s valuation
A different lens on Adeia comes from the SWS DCF model, which puts the future cash flow value at about $24.12 compared with the recent $24.92 share price. That points to a stock trading slightly above this estimate, so how much weight do you give to analyst targets against a tighter cash flow view?
To see how this cash flow approach is built and what assumptions sit underneath it, take a closer look at the Look into how the SWS DCF model arrives at its fair value..
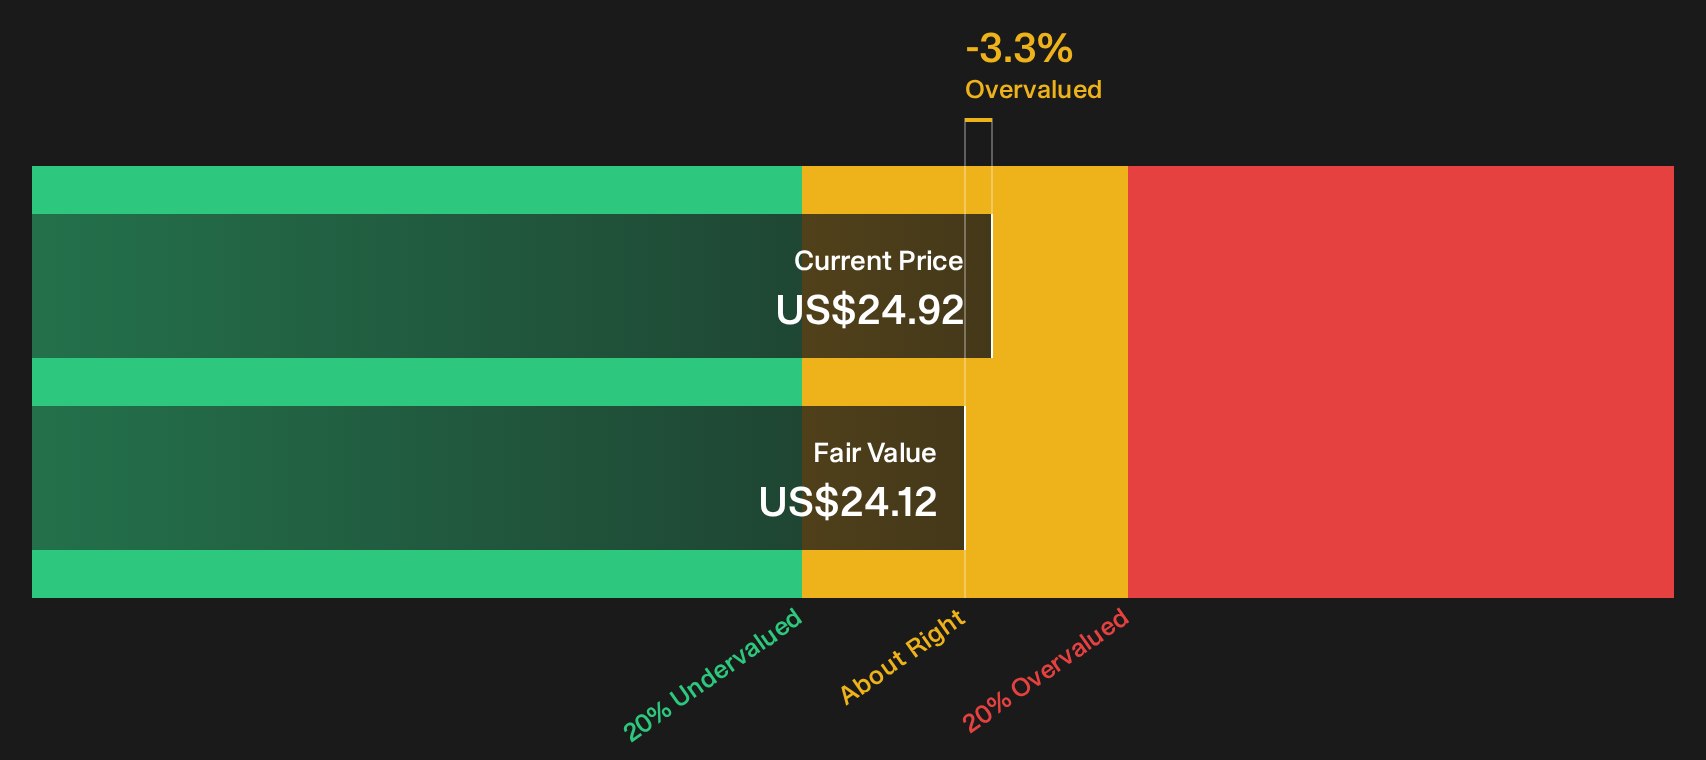
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Adeia for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or clear opportunity; either way, the clock is ticking for anyone trying to build an informed view on Adeia. Weigh the upside against the concerns by starting with the 4 key rewards and 2 important warning signs.
Looking for more Adeia sized investment ideas?
If Adeia has your attention, do not stop here. Broaden your watchlist with a few curated ideas that could reshape how you think about opportunities.
- Target quality at a discount by scanning a curated 33 high quality undervalued stocks that filters for strong fundamentals at prices that may not last.
- Prioritize resilience by reviewing a 30 resilient stocks with low risk scores that highlights businesses with steadier risk profiles when you want fewer surprises.
- Hunt for future leaders through a 16 high quality undiscovered gems that focuses on under-the-radar companies with robust financial foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com