
Top 3 Australian Insider Owned Growth Stocks To Watch In September 2026
Global markets have been swinging around higher interest rates and stubborn inflation, which has put pressure on many highly priced growth stories. That backdrop can reward investors who focus on fast growing Australian companies where insiders already hold meaningful stakes and have their own capital on the line. This article breaks down three such stocks from our screener, explaining why their growth profiles and ownership structures may appeal today.
The three stocks below are just a small sample, and the full screen surfaced 110 more fast growing Australian businesses with high insider ownership and equally compelling narratives that are not covered here. To cast a wider net and quickly identify which ones best fit your style, head straight into the Fast Growing Stocks With High Insider Ownership screener
Liontown (ASX:LTR)
Overview: Liontown is an Australian minerals developer focused on the Kathleen Valley lithium project, a large hard rock deposit supported by additional exploration.
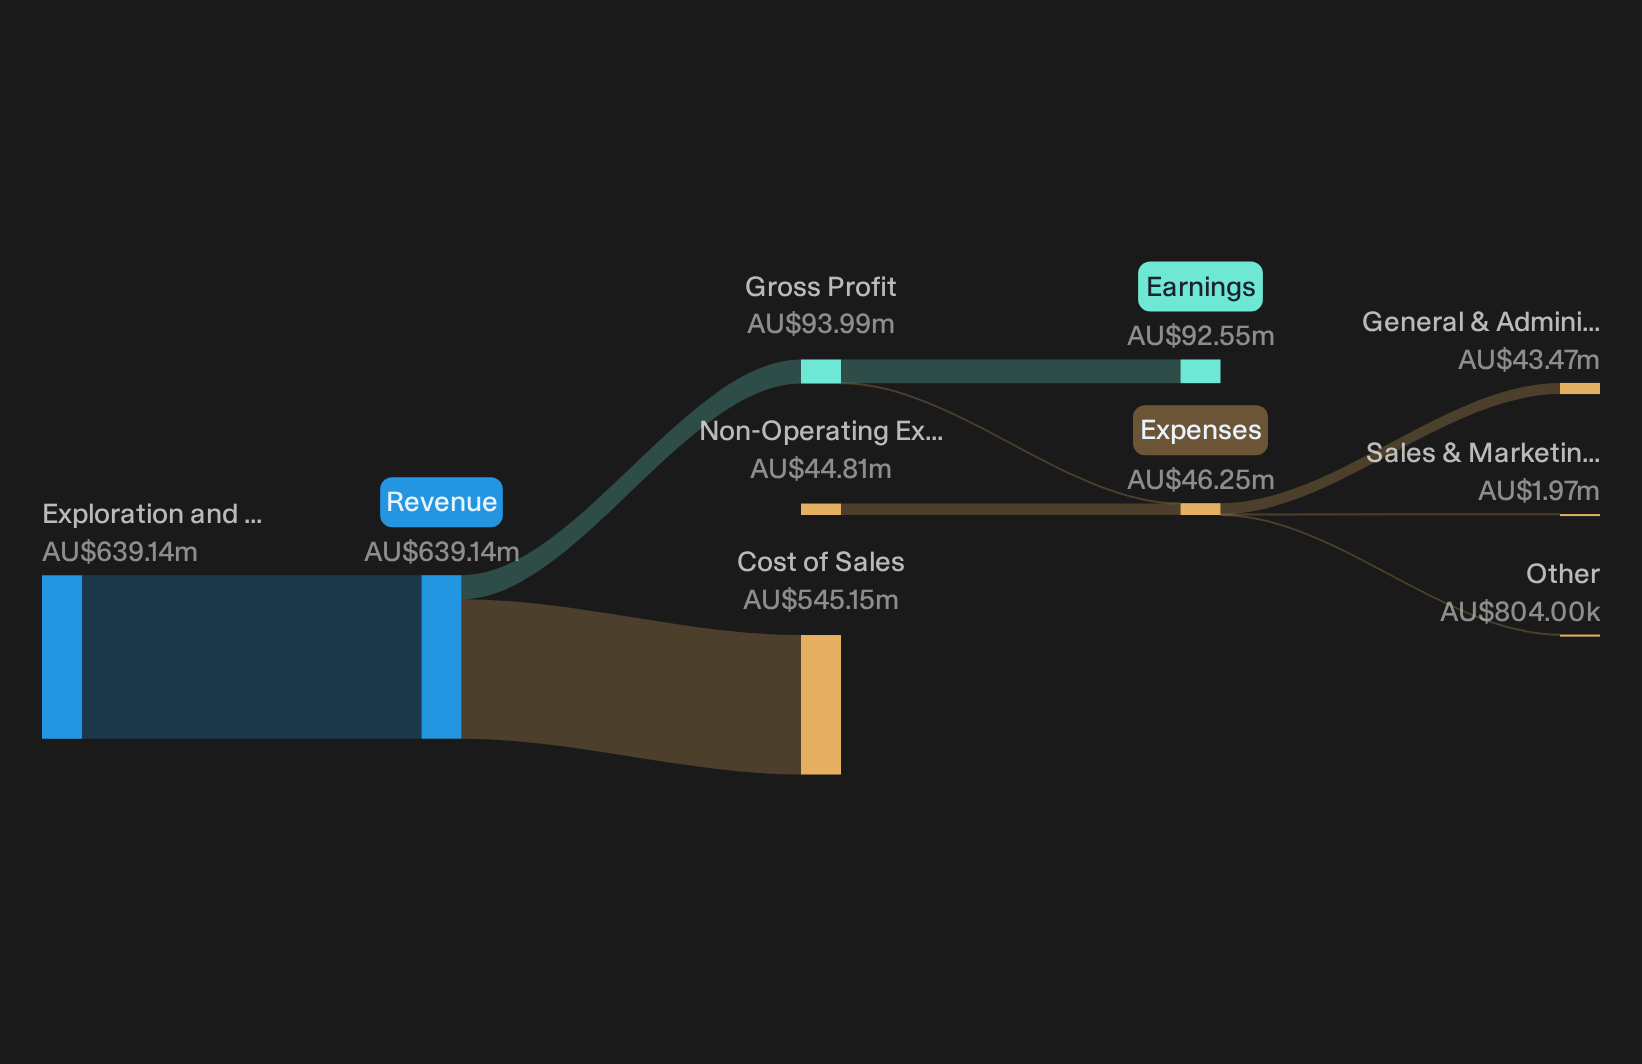
Operations: Liontown generated A$639 million from exploration and development of minerals in Australia, with all reported revenue tied to domestic activities.
Market Cap: A$2.9 billion
Liontown matters for this screener because its Kathleen Valley lithium project and expanding project pipeline are central to the business strategy, with management and analysts both allocating capital and operational focus to these developments.
"The company has initiated trials with higher contamination ore, achieving higher lithium recovery rates while maintaining strong recovery even with lower-grade material, which could affect net margins by changing processing costs over time."
What happens to those margins if one unseen pressure on lithium pricing and project costs moves in the wrong direction will be crucial.
If that pressure on pricing starts to bite, the full narrative for Liontown explains how Liontown’s growth plans, funding options and insider alignment could still keep the story accelerating.
PDI Gold (ASX:PDI)
Overview: PDI Gold is a West African gold explorer and producer, with growth tied closely to its large Kiniéro project and broader pipeline.
Market Cap: A$4.5 billion
PDI Gold matters for this screener because Kiniéro anchors a growth profile where management and analysts both see potential for output expansion and stronger cash generation over time.
"The merger with Robex creates a larger platform with two producing mines and the Bankan development project. This combination can support higher group gold output over time and provide a broader base for revenue and earnings."
Any change in a single key assumption around West African permitting and production timelines could be critical for that growth path.
That single hinge on permitting risk is exactly where the full narrative for PDI Gold shows how PDI Gold’s growth ambitions could accelerate or stall under different scenarios.

Telix Pharmaceuticals (ASX:TLX)
Overview: Telix Pharmaceuticals develops and commercialises radiopharmaceutical diagnostics and therapies, using precision imaging and targeted treatments to help clinicians find and attack cancers.
Operations: Telix generated about $704.7 million from Precision Medicine and $277.1 million from Manufacturing Solutions, with meaningful inter segment eliminations.
Market Cap: A$5.47 billion
Telix matters for this fast growing, high insider ownership theme because its late stage prostate cancer radiopharmaceuticals and diagnostics concentrate both the commercial opportunity and management focus.
"And the therapeutics pipeline: prostate, kidney, glioblastoma and others is where the real long-term upside lives if trials go well."
What happens when one key assumption on trial outcomes and regulator decisions shifts will heavily influence how this growth story ultimately plays out.
That hinges on how Telix Pharmaceuticals balances trial risk with commercial momentum, and the full narrative for Telix Pharmaceuticals maps where that tension could turn into accelerating upside or stall points.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. The strongest stories often break out while most investors are still watching old favourites. Scan these under the radar lists before momentum is fully caught and consider acting promptly.
- Target rock solid balance sheets and steady fundamentals by running your filters through the curated list of solid balance sheet and fundamentals (11 results) while it still feels like quiet territory.
- Explore potential income opportunities by zeroing in on high yield candidates using the carefully assembled 3 dividend fortresses before payouts and prices are fully repriced.
- Review opportunities in precious metals by combing through the hand picked 36 elite gold producer stocks while sentiment remains muted and expectations stay low.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com