
Ondas (ONDS) Lands SSE Deal, But Is The Stock Still A Bargain?
Cyberhawk’s new three year agreement with SSE for drone inspection across UK electricity networks, including offshore wind assets and renewed iHawk services, has put Ondas (ONDS) back under the microscope for valuation focused investors.
The SSE contract lands at a time when Ondas’ 1-day share price return of 0.52% and 7-day share price return of 4.06% hint at improving near term sentiment, even though the year to date share price return is down 30.31% and the 1-year total shareholder return is slightly negative. At the same time, the very large 3-year total shareholder return suggests longer term holders have still seen substantial gains.
Scan beyond Ondas and this SSE deal by reviewing a curated group of power and infrastructure plays in our 39 power grid technology and infrastructure stocks that could also benefit from grid modernization and inspection demand.
Ondas now carries a fresh SSE contract, a strong three year shareholder return and a recent bounce from weaker year to date levels. Does that mix still leave enough upside to justify the risk at today’s price?
Most Popular Narrative: 62% Undervalued
Ondas closed at $7.68 while the most widely followed narrative pegs fair value at $20.13. The contract news therefore fits into a story already framed as deeply discounted, with a lot riding on execution.
Ondas anticipates record revenue growth in 2025, primarily driven by Ondas Autonomous Systems (OAS), due to significant backlog and expanding programs with Optimus and Iron Drone systems in defense and homeland security sectors. This will directly impact revenue.
See why 139 investors see Ondas as 62% undervalued.
Result: Fair Value of $20.13 (UNDERVALUED)
Still, execution setbacks at Ondas Networks and any repeat of geopolitical disruption in Israel could quickly challenge the upbeat fair value story that investors are leaning on.
Find out about the key risks to this Ondas narrative.
Another View On Ondas’ Valuation
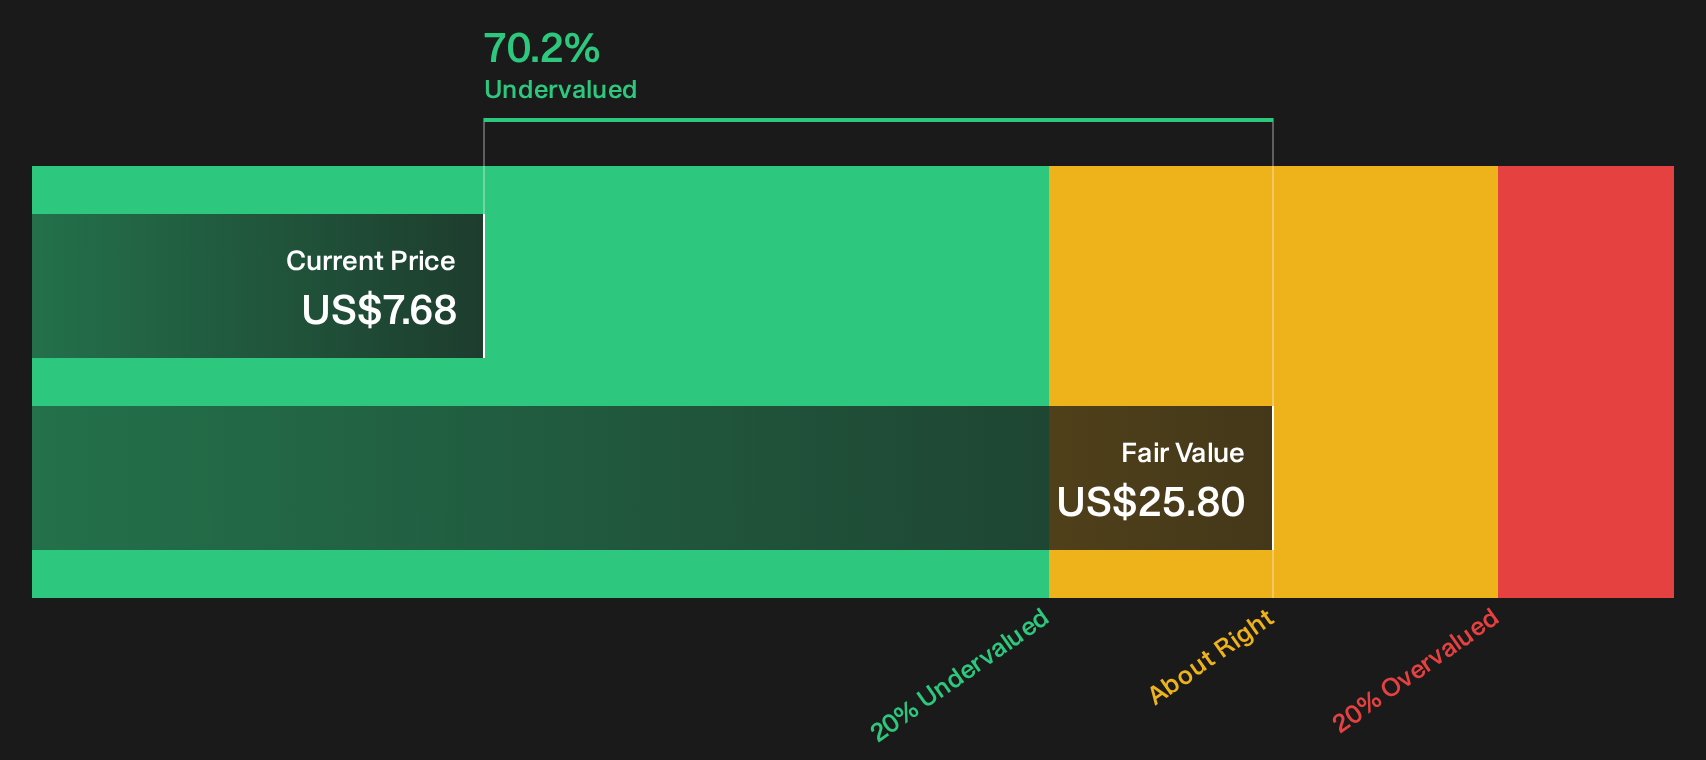
Analyst narratives and the SWS DCF model both lean toward Ondas looking cheap, with the DCF pointing to a future cash flow value of $25.80 per share, well above the recent $7.68 price. The puzzle is that earnings forecasts are set to decline 2.5% a year. How comfortable are you relying on cash flow assumptions when profit projections move the other way?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Ondas can either sharpen your conviction or push you to reassess fast. Pressure test the thesis yourself and weigh up the 3 key rewards and 4 important warning signs.
Want More Ondas-Like Investment Ideas?
If Ondas has sharpened your appetite for opportunity, do not stop here. Broaden your watchlist with a few focused stock ideas built from hard numbers.
- Target potential bargains by scanning companies that combine quality fundamentals with discounted prices through our 33 high quality undervalued stocks.
- Prioritize resilience and steadier sleep at night by reviewing a 30 resilient stocks with low risk scores that filters for companies with lower overall risk profiles.
- Spot financially robust operators early by studying a list of solid balance sheet and fundamentals (25 results) that highlights businesses with stronger balance sheets and healthier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com