
Is Chewy (CHWY) A Bargain Following Concerns Over Growth And Costs?
Recent commentary around Chewy (CHWY) has focused on its scale limitations, higher servicing costs, and softer demand. Together, these factors have weighed on expectations for future revenue expansion and pressured investor sentiment.
Chewy’s recent price action reflects that pressure, with the 7-day share price return down 9.26% and the 30-day move down 19.99%. The year-to-date share price return has declined 44.43%, and the 1-year total shareholder return is down 53.41%, signalling fading momentum despite a broadly flat 3-year total shareholder return of 0.11%.
Compare Chewy’s recent pullback with other e-commerce and retail names by scanning our hand-picked 16 high quality undiscovered gems that may be flying under most investors’ radar.
Chewy’s share price reset is plain to see. What still feels up for debate is whether that slump has already captured most of the bad news, or if the bulk of any upside is now behind the stock.
Most Popular Narrative: 35% Undervalued
On Simply Wall St’s most followed narrative, Chewy’s fair value sits at $28.82 against a last close of $18.61, putting the current share price well below that estimate and placing more focus on whether the underlying thesis still holds up.
Chewy's strategic expansions, such as opening new Chewy Vet Care Clinics, are expected to further penetrate the $25 billion vet services market, likely increasing revenue and active customer engagement in 2025 and beyond.
The migration to a 1P ad platform allows for enhanced advertising capabilities, including off-site ads and new content formats like video, which could grow the sponsored ads business up to 3% of total enterprise net sales, positively impacting gross margins.
See why 75 investors see Chewy as 35% undervalued.
Result: Fair Value of $28.82 (UNDERVALUED)
Still, the heavy reliance on Autoship for more than 80% of sales and only modest customer growth leave Chewy exposed if shopper behaviour or acquisition trends weaken.
Find out about the key risks to this Chewy narrative.
Another View On Chewy’s Valuation
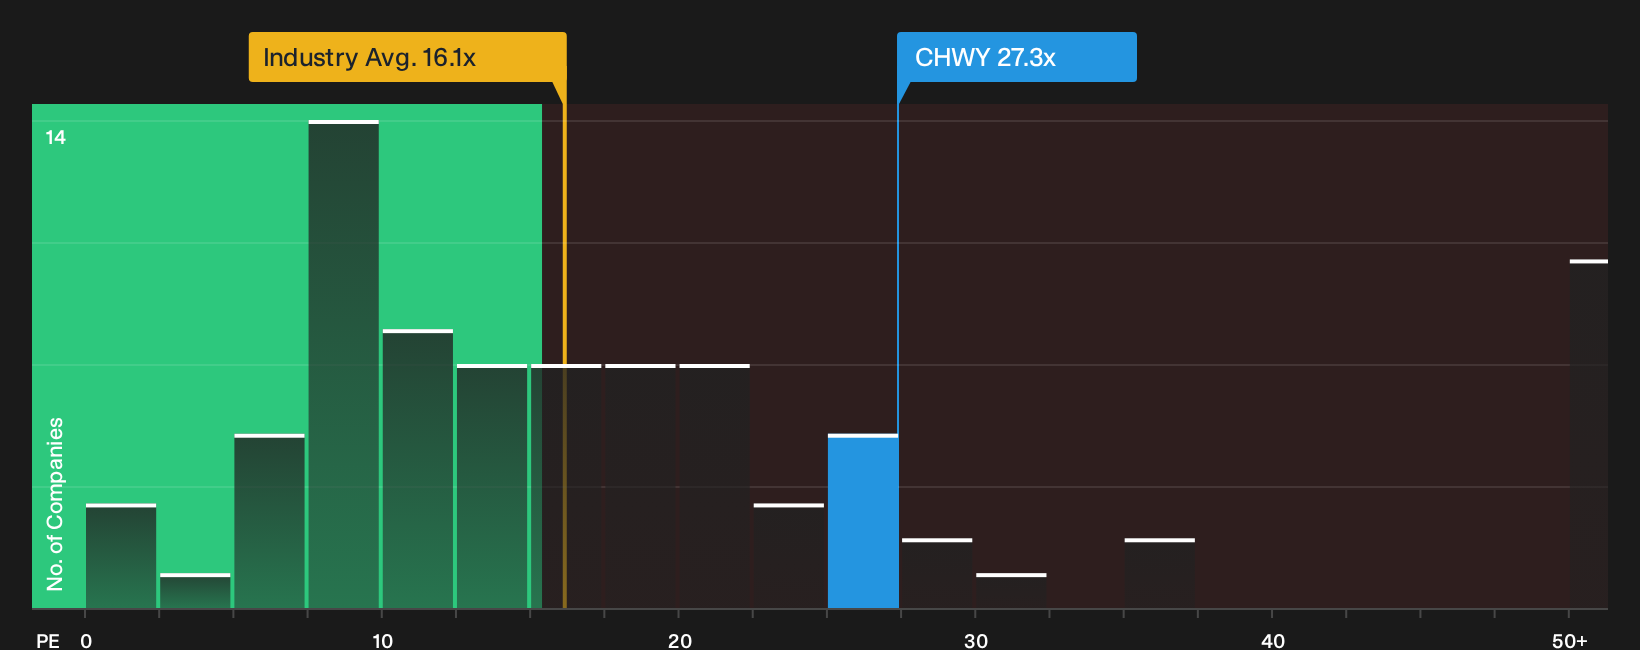
The first lens paints Chewy as undervalued versus a $28.82 fair value. Using earnings multiples tells a tougher story. The stock trades on a P/E of 27.3x, well above both the US Specialty Retail group at 16.1x and peers at 15.5x, and above its own fair ratio of 21.3x. That gap suggests investors are already paying a premium for future profit delivery, so how comfortable are you with that margin for error?
To see how that premium lines up with the underlying numbers, check the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the tone on Chewy so far feels cautious, that is by design, but data beats opinions when you move quickly and check the full picture. To see which rewards are underpinning current optimism and to pressure test them against your own thesis, review the 4 key rewards
Looking for more investment ideas beyond Chewy?
Do not stop with Chewy alone. Use curated idea lists to pressure test your thinking, source fresh candidates, and avoid missing opportunities that already fit your criteria.
- Target stability in rough markets by scanning a curated set of 30 resilient stocks with low risk scores that prioritize resilient balance sheets and lower risk profiles.
- Hunt for value opportunities by reviewing the 33 high quality undervalued stocks that combine stronger fundamentals with pricing that still trails underlying business quality.
- Anchor your portfolio with income candidates by focusing on 6 dividend fortresses that pair higher yields with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com