
Can Centuri Holdings (CTRI) Justify Its Valuation On Michael Christy’s Appointment?
Centuri Holdings (CTRI) just reshaped its leadership bench by appointing Michael Christy as Executive Vice President and Group Development Officer, placing him in charge of strategy, sales processes, growth initiatives, and non-union electric operations.
Centuri Holdings shares closed at US$19.92 after a one day share price return that declined 2.88%, and the stock has retreated 34.13% on a 90 day share price basis while the 1 year total shareholder return is down 4.37%. Recent momentum has been fading even as investors weigh Christy’s appointment as a potential shift in how growth opportunities and risks are managed.
Scan how Centuri Holdings compares with other infrastructure focused contractors by checking the hand picked 39 power grid technology and infrastructure stocks that is now shaping the build out of modern utility networks.
Centuri Holdings now trades well below recent levels after a sharp 90 day pullback, even as a new growth focused executive steps in. Does that reset leave more upside potential than downside risk for fresh buyers?
Most Popular Narrative: 37% Undervalued
On the most followed view of Centuri Holdings, a fair value of $31.75 sits well above the recent $19.92 close. This puts the focus on whether the contract pipeline and execution quality can support that gap over time.
Record backlog of approximately $5.9 billion and a robust $13 billion opportunity pipeline, including over 600 strategic bids, supports sustained revenue growth by converting awarded work into a higher, more stable top line.
Growing utility infrastructure investment tied to regulatory-driven gas pipeline replacement, such as PHMSA Gas Mega Rule projects, is expanding high-visibility, multi-year workloads that may support steady revenue expansion and structurally higher base earnings.
See why 3 investors see Centuri Holdings as 37% undervalued.
Result: Fair Value of $31.75 (UNDERVALUED)
Still, the Centuri Holdings story can break if higher fuel and fleet costs linger or if sector wide clean energy policy risk keeps valuations under pressure.
Find out about the key risks to this Centuri Holdings narrative.
Another View: What P/E Says About Centuri Holdings
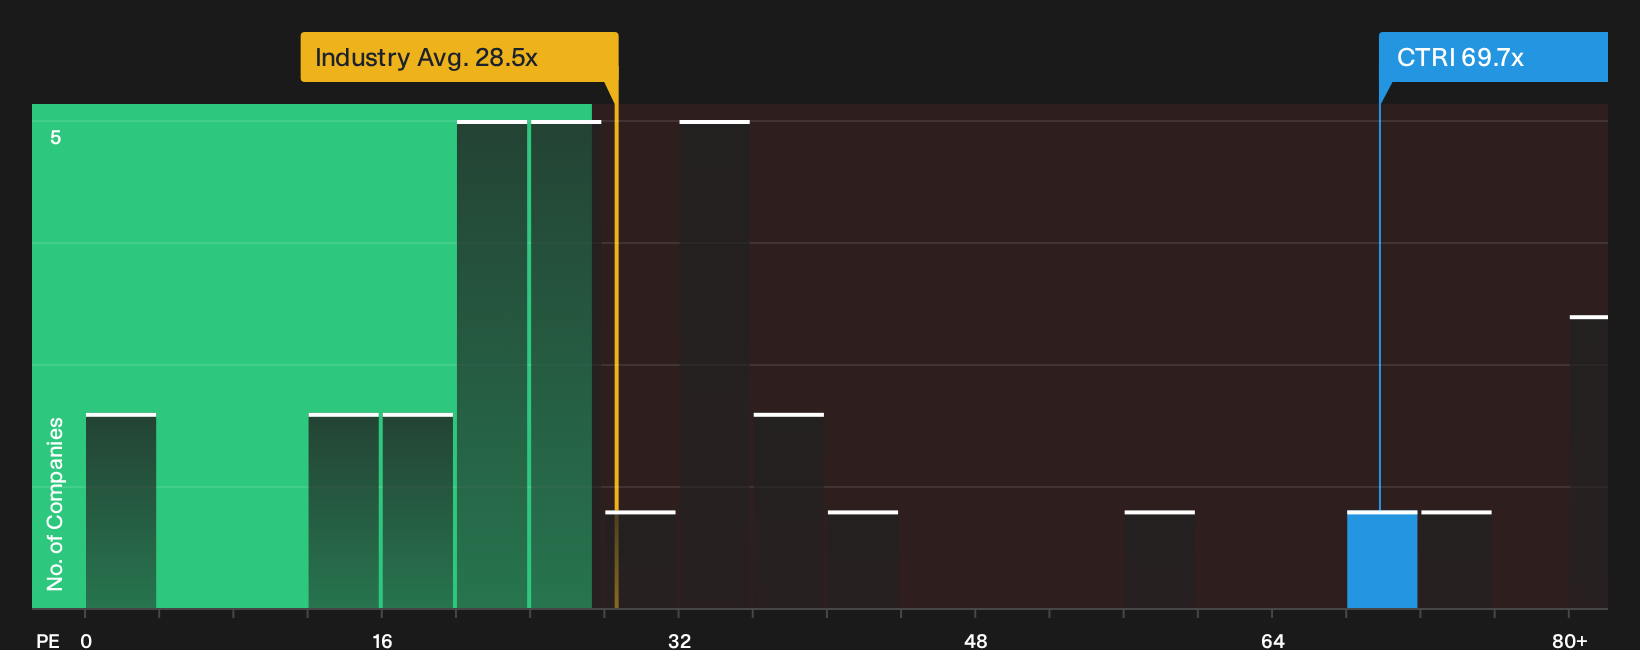
That $31.75 fair value line is one story. The P/E picture tells a very different one. Centuri Holdings trades on about 69.7x earnings, while the US Construction industry sits near 28.5x, peers around 30.4x, and the fair ratio is estimated at 41x. That gap points to meaningful valuation risk if expectations wobble, so how comfortable are you paying a premium that large for this earnings profile?
See what the numbers say about this price by checking the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Centuri Holdings can either keep you on the sidelines or push you to test the numbers yourself and decide fast. To weigh both sides of the story in one place, start with the 3 key rewards and 2 important warning signs.
Looking for more Centuri Holdings sized ideas?
If Centuri Holdings has you thinking more broadly about where to put fresh capital, do not stop at one ticker. Cast the net wider with focused stock lists built from fundamentals and clear financial traits.
- Target value opportunities that combine quality and pricing power by using the 33 high quality undervalued stocks tailored to financially robust businesses trading at what may be compressed valuations.
- Lock in potential income streams and stress test payout strength through the 6 dividend fortresses which filters for companies offering higher yields with supporting fundamentals.
- Prioritise resilience and capital preservation by turning to the 30 resilient stocks with low risk scores that filters for businesses with sturdier balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com