
Liberty Energy (LBRT) Faces A 90 Day Slide, Is A 35% Undervaluation Enough?
Liberty Energy (LBRT) drew fresh attention after recent trading data highlighted a mixed return profile, with the stock roughly flat year to date while showing a materially weaker performance over the past 3 months.
Short term momentum for Liberty Energy has cooled, with the 90 day share price return down 27.6% even as the latest close sits at $18.95 and the 1 year total shareholder return is 51.4%. This shows a very different picture for longer term holders.
Scan beyond Liberty Energy and evaluate other oilfield and energy contractors showing similar price swings with our curated list of list of solid balance sheet and fundamentals (25 results).
After a sharp 90-day pullback but a strong 1-year return, Liberty Energy now raises a timing question. Is the recent slide already reflected in the price, or is patience on entry still worth considering as you weigh valuation next?
Most Popular Narrative: 35% Undervalued
On the most followed narrative, Liberty Energy screens as undervalued, with a fair value of $29.04 versus the latest close at $18.95, which puts the spotlight firmly on whether the long-term power buildout can justify that gap.
Liberty's leadership in next-generation technology, including its digiPrime/digiFleet natural gas-powered frac solutions and modular, low-emission power generation, is enabling market share gains, operational efficiencies, longer asset life, and stronger pricing with top-tier customers, supporting improved margins and higher free cash flow. Strategic alliances and scale investments (e.g., Oklo partnership for advanced nuclear solutions, microgrid and distributed power projects) position Liberty to capture higher-value, long-duration contracts from large-scale customers like data centers, expanding Liberty's addressable market and driving future top-line and margin growth.
See why 8 investors see Liberty Energy as 35% undervalued.
Result: Fair Value of $29.04 (UNDERVALUED)
Still, Liberty Energy faces two clear swing factors: a softer completions backdrop and higher power capex without firm contracts could quickly puncture the current undervalued narrative.
Find out about the key risks to this Liberty Energy narrative.
Another View: Liberty Energy On Earnings Multiples
There is a catch. On simple earnings metrics, Liberty Energy does not look as cheap as the 35% undervalued fair value would suggest.
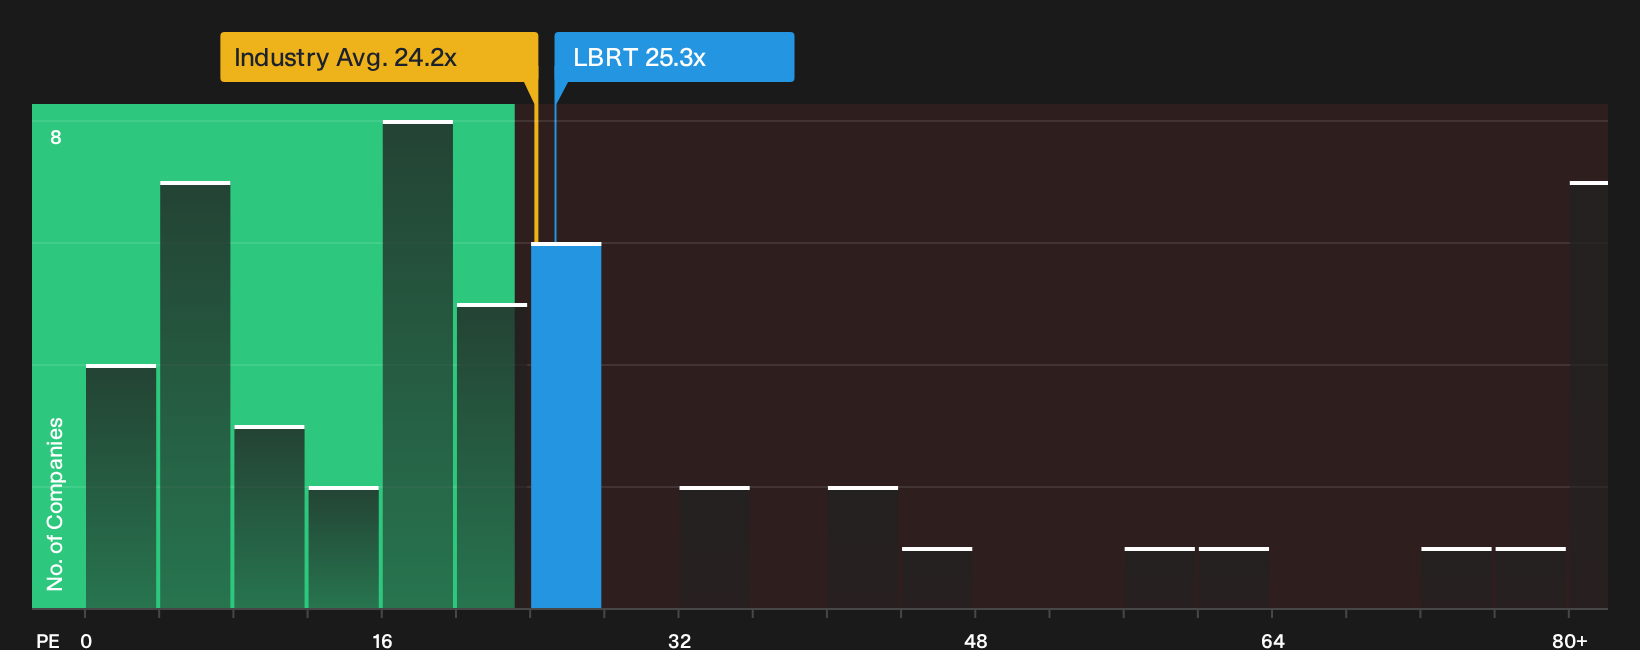
The stock trades on a P/E of 25.3x, which sits above the US Energy Services industry average of 24.2x. Our fair ratio points to 11.4x as a level the market could move towards. That gap signals meaningful valuation risk if sentiment cools, so how much weight do you put on the narrative versus the numbers?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Liberty Energy feels familiar, move quickly from headline impressions to your own assessment by weighing the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Liberty Energy?
You have a clear view on Liberty Energy. Now widen your opportunity set with focused stock ideas that fit different risk, income, and value preferences.
Skip the guesswork and use filtered ideas to guide your next move with the Simply Wall St Screener. You may prefer not to identify these opportunities only after other investors have already acted.
- Target potential mispricing by scanning for companies that combine quality fundamentals with discounted valuations through our 33 high quality undervalued stocks.
- Focus on your income objectives by considering businesses with robust payouts using the 6 dividend fortresses.
- Emphasise resilience by reviewing companies with sturdier finances via the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com