
Why Southwest Airlines (LUV) Is Back In The Spotlight
Southwest Airlines (LUV) reshaped its flight credit rules from May 28, 2025, adding expiration dates while a gift card workaround emerged. Investors now have a fresh policy shift to factor into the stock’s risk reward profile.
The recent tweak to Southwest Airlines’ credit policy comes after a mixed stretch for the stock. The share price is up 6.66% over 30 days but down 17.78% over 90 days, while the 1-year total shareholder return of 31.36% points to momentum that has cooled in recent months.
Scan how Southwest Airlines’ shift toward ancillary revenue stacks up against peers by zeroing in on 33 high quality undervalued stocks that may offer a similar mix of pricing power and customer loyalty.
Southwest Airlines is tweaking how it treats loyal customers at the same time the share price has cooled after a strong 1-year run. Does that mix still tilt the risk reward toward new buyers at today’s valuation?
Most Popular Narrative: 16% Undervalued
Southwest Airlines closed at $42.28, while the most followed narrative pins fair value closer to $50.05. The current price sits below what that framework implies once longer term earnings and margin assumptions are plugged in.
Planned introduction of premium and assigned seating, along with basic economy offerings, can enhance revenue yield through differentiated pricing strategies catering to varied consumer preferences, thereby potentially boosting net margins and overall earnings.
See why 31 investors see Southwest Airlines as 16% undervalued.
Result: Fair Value of $50.05 (UNDERVALUED)
Still, the narrative can break if jet fuel remains expensive and if new fees like bag charges and basic economy continue to push Southwest Airlines customers toward rivals.
Find out about the key risks to this Southwest Airlines narrative.
Another View: Southwest Airlines Through Market Multiples
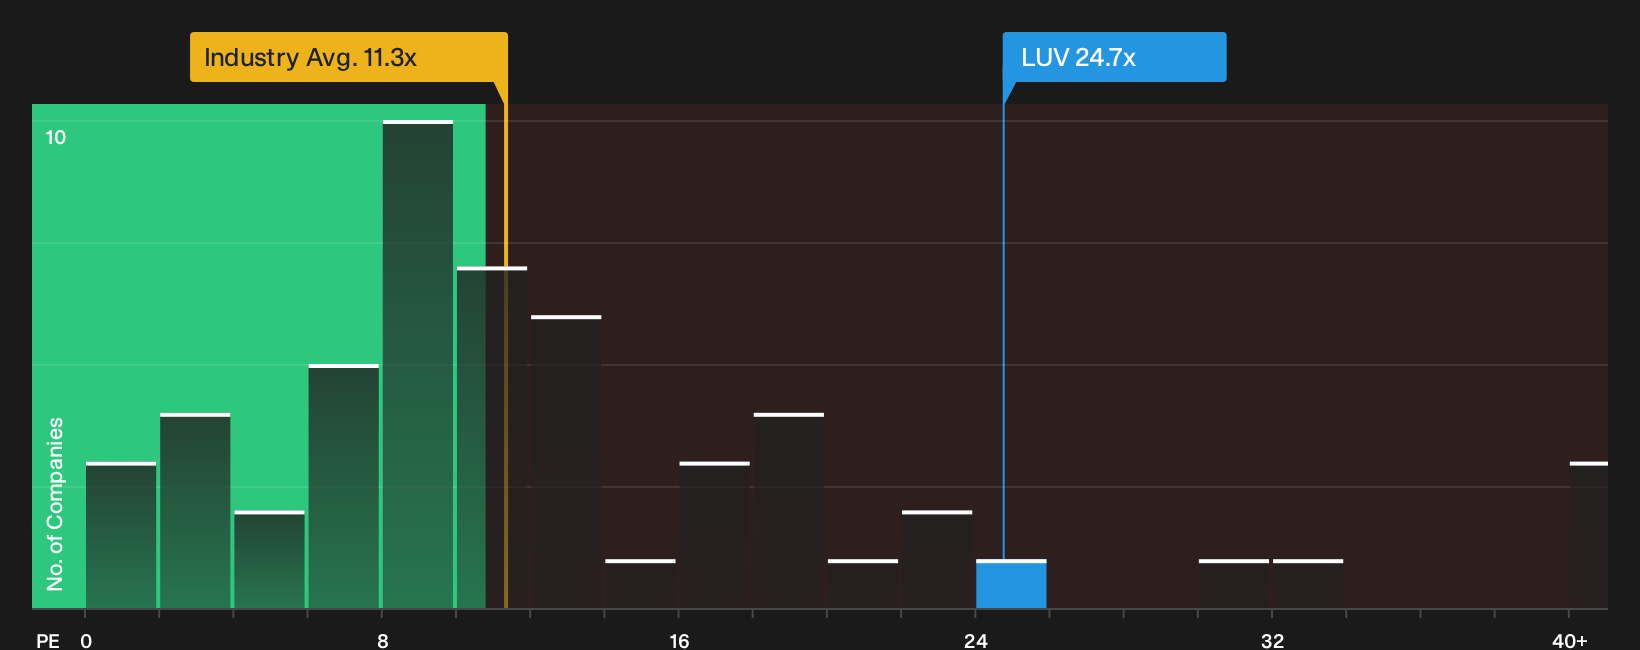
The fair value story around Southwest Airlines looks different once P/E comes into focus. The stock trades at 24.7x earnings, which is more than double both the Global Airlines industry at 11.3x and its peer average at 10.6x, even though the fair ratio is 25.4x.
That gap suggests investors are already paying a premium and leaving only a narrow margin between the current P/E and the fair ratio the market could move toward. If sentiment shifts or earnings expectations cool, how much downside tolerance is there at this entry point?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Southwest Airlines can feel confusing, so move quickly, review the full set of bullish and bearish factors, then weigh the 3 key rewards and 1 important warning sign.
Looking for more Southwest Airlines investment ideas?
If Southwest Airlines has your attention, do not stop here. Broaden your watchlist with fresh ideas built from data driven screeners that surface focused opportunities.
- Target potential mispricings by scanning companies flagged as high quality and potentially overlooked through the 16 high quality undiscovered gems.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that can help you stress test ideas before committing capital.
- Zero in on quality at a possible discount by checking a 33 high quality undervalued stocks that aligns price with fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com