
NetEase (SEHK:9999) In Focus As Ananta Buzz Raises The Question Of Value
NetEase (SEHK:9999) is back in focus after Morgan Stanley highlighted the upcoming global release of its game Ananta as a key potential growth driver, along with recent gains in Hong Kong technology shares.
Recent trading hints at shifting sentiment around NetEase. The 1-day share price return of 4.86% and 7-day gain of 2.37% contrast with a year to date share price decline of 17.09%, while the 5-year total shareholder return of 66.78% points to a much stronger long run record.
Scan how NetEase compares with other potential breakout opportunities using our curated list of 618 high quality undiscovered gems in similar high-growth themes.
NetEase now trades at a sizeable discount to both analyst targets and some intrinsic value estimates, even after the recent bounce. Is this caution a sober read on risk, or a mispriced opportunity on Ananta and the wider business franchise?
Most Popular Narrative: 24% Undervalued
NetEase is priced at HK$189.7, while the most followed narrative pegs fair value at HK$249.78 based on a 9.07% discount rate and detailed earnings assumptions.
NetEase is accelerating global expansion with self-developed and licensed games that have performed strongly in overseas markets (e.g., Marvel Mystic Mayhem, FragPunk, Once Human, Eggy Party). This is increasing the company's addressable market and diversifying revenue streams beyond China, supporting higher long-term revenue growth and earnings stability. Rising adoption of digital entertainment and online experiences, including increasing global internet connectivity and smartphone penetration, continues to boost demand for NetEase's core gaming and music businesses, laying a foundation for sustainable top-line growth and robust user engagement.
See why 20 investors see NetEase as 24% undervalued.
Result: Fair Value of HK$249.78 (UNDERVALUED)
Still, the NetEase story can crack if overseas expansion keeps contributing only a small slice of revenue, or if heavier R&D and content spending squeezes margins.
Find out about the key risks to this NetEase narrative.
Another View On NetEase Valuation
Those fair value estimates around HK$249.78 lean on long term earnings forecasts and discount rates. A simpler cross check looks at what investors are currently paying for NetEase profits.
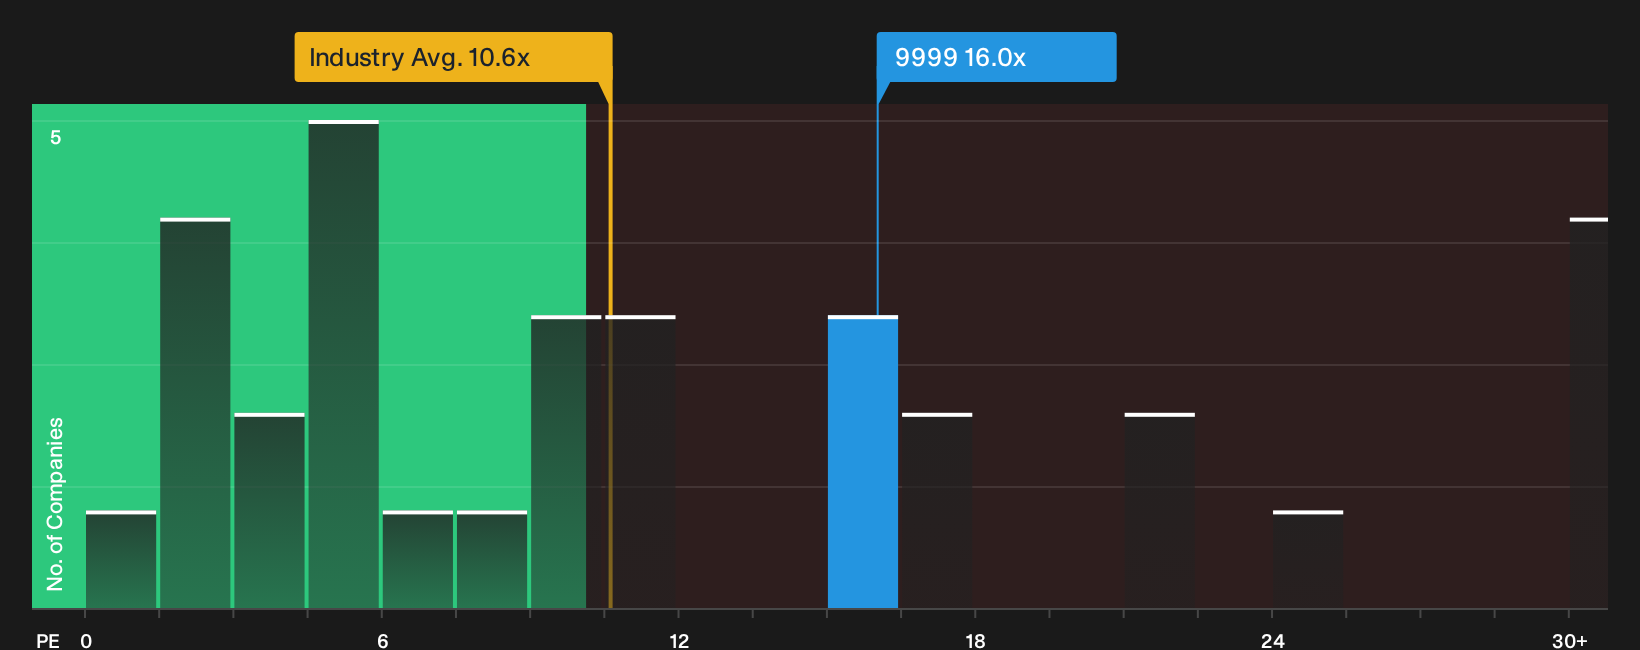
The stock trades on a P/E of 16x, which is well above the Hong Kong Entertainment industry at 10.6x and peers at 7.6x. It also sits above the fair ratio of 15.3x that the market could move toward over time. That richer multiple can signal optimism, but it also raises the risk that any disappointment on growth, margins, or Ananta uptake hits the share price harder than expected.
For a closer look at how this earnings multiple stacks up against fundamentals and peers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around NetEase is split, which is exactly why looking at the underlying numbers yourself can be valuable before the next move. To see what is driving optimism and where the market sees potential upside, review the 3 key rewards
Looking for more NetEase sized ideas?
If you stop with NetEase, you only see part of the opportunity set. Use the Simply Wall St screener to spot what the wider market might be missing.
- Hunt for businesses the market may have overlooked by scanning our hand picked 618 high quality undiscovered gems that combine quality fundamentals with quieter headlines.
- Prioritise resilience first and focus on 221 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
- Target value with quality by reviewing a curated list of 198 high quality undervalued stocks that pair solid cash flows with attractive pricing signals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com