
Will Federal Racketeering Lawsuit Change C.H. Robinson Stock Narrative
- C.H. Robinson Worldwide has been named in a federal lawsuit in Texas alleging violations of the RICO Act, including racketeering, forced labor and wire fraud, with the firm stating that it rejects the claims and plans to defend itself.
- The complaint challenges how C.H. Robinson Worldwide positions itself as a broker while working with certain carriers, which could affect compliance costs, contract structures and how shippers assess operational risk across its logistics network.
- This development also raises questions about how C.H. Robinson Worldwide's investment narrative intersects with these racketeering allegations related to its broker relationships.
Spread your risk beyond C.H. Robinson Worldwide by reviewing a curated 30 resilient stocks with low risk scores that aims to pair operational resilience with cleaner risk profiles than relying on a single logistics stock facing legal scrutiny.
C.H. Robinson Worldwide Investment Narrative Recap
To own C.H. Robinson Worldwide, you need to believe its Lean AI model, automation and large data set can keep raising productivity and supporting earnings growth while legal and insurance pressures stay manageable. The short term hinge is execution in core segments such as North American Surface Transportation and Global Forwarding, where efficiency gains are already a key focus.
The biggest operational risk is that mounting legal exposure, including the new RICO lawsuit and the earlier US$604 million jury award, feeds into higher insurance costs or tighter carrier capacity. If that happens, it could weigh on net margins and soften the benefits from industry consolidation and shipper volume concentration.
With no fresh operational announcements tied directly to this lawsuit, the most relevant reference point is still that prior US$604 million jury award that found C.H. Robinson Worldwide partially liable in a major accident case. That decision already put broker liability in the spotlight and raised questions about how courts might treat intermediaries in the freight chain.
If courts maintain or extend that stance, it could push C.H. Robinson Worldwide to adjust contracts, carrier vetting and pricing to reflect higher perceived risk. Any shift that raises insurance expense or causes risk averse carriers to pull back would matter for the Lean AI margin story and for how much operating leverage investors can reasonably underwrite.
C.H. Robinson Worldwide's current analyst narrative points to revenues of US$20.3b and earnings of US$941.9m by 2029, based on an assumed 6.2% annual revenue growth rate. This is up from earnings of US$633.3m today, which implies an earnings increase of about US$308.6m over that period.
Uncover why C.H. Robinson Worldwide's fair value indicates a 35% potential upside to its current price, which could narrow quickly.
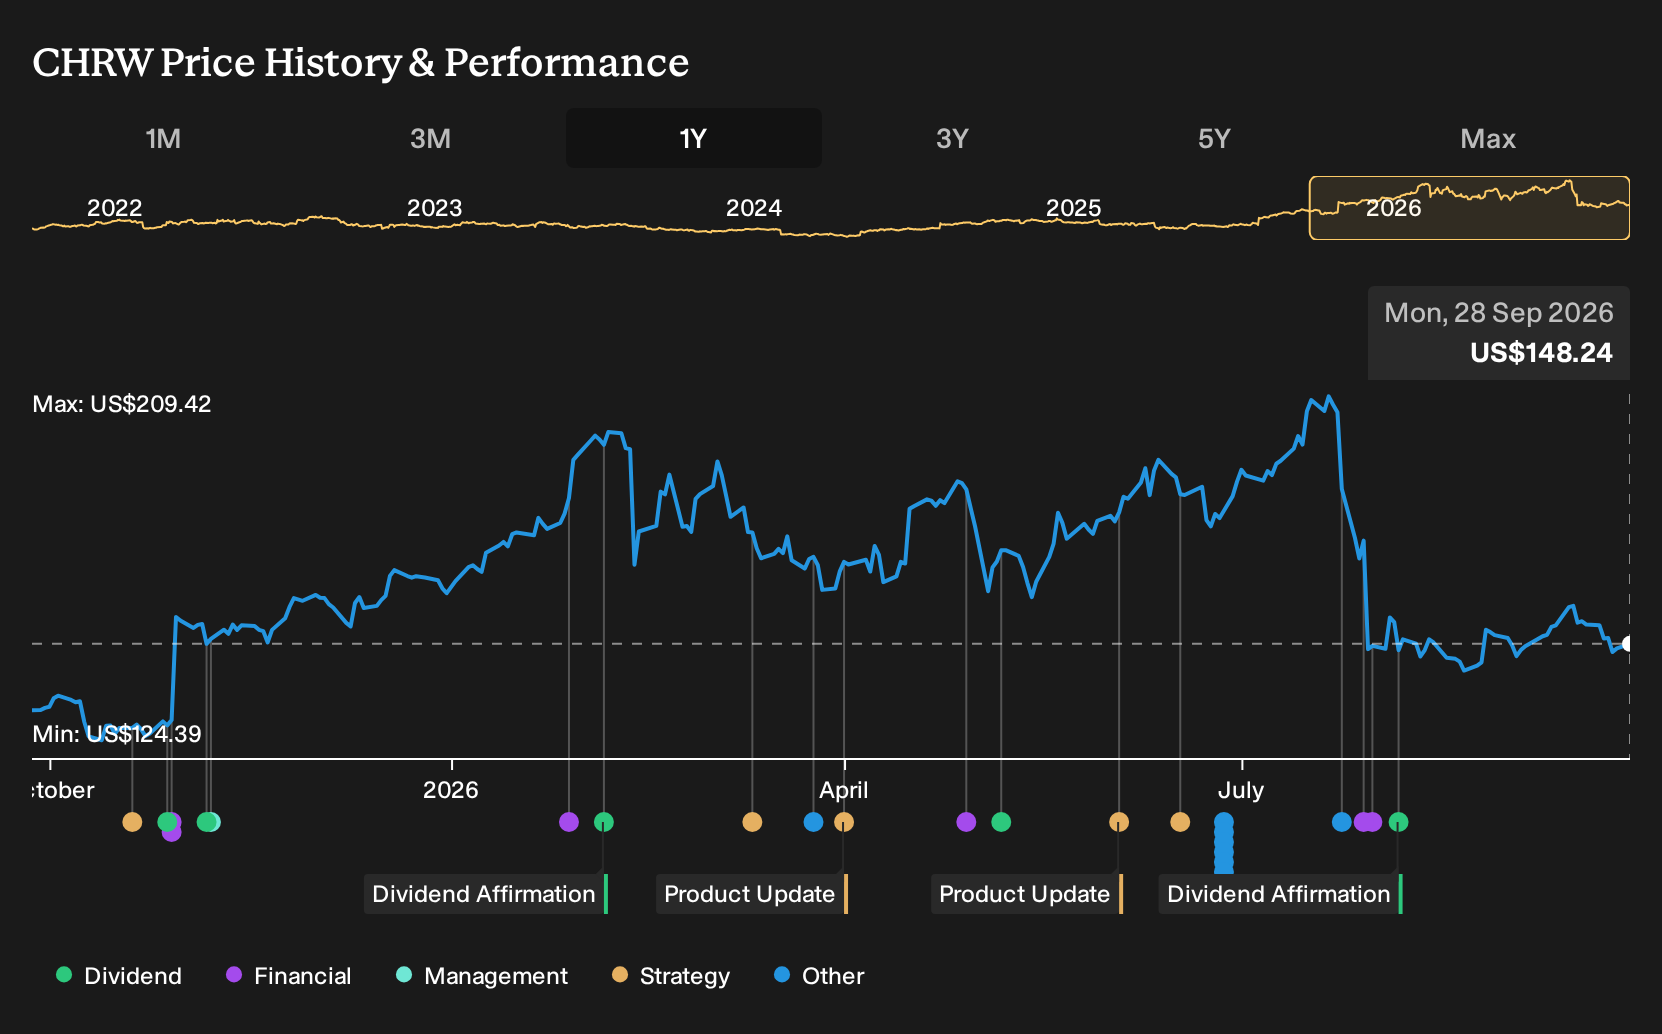
Exploring Other Perspectives
Some of the highest analysts frame the bigger swing factor not as legal risk at all, but as how far C.H. Robinson Worldwide can push AI driven operating leverage. Before this RICO case surfaced, that group was pencilling in revenues of about US$22.5b and earnings around US$1.1b by 2029, so their story is far more optimistic than consensus. You do not need to agree with that view, but it is useful to see how sharply opinions can differ and to ask how this lawsuit could reshape those forecasts.
Explore 2 other C.H. Robinson Worldwide fair value estimates, including one that suggests as much as 35% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your C.H. Robinson Worldwide research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for C.H. Robinson Worldwide. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate C.H. Robinson Worldwide's overall financial health at a glance.
Looking For More Investment Ideas Beyond C.H. Robinson Worldwide?
If this C.H. Robinson Worldwide story has you thinking about position sizing and concentration risk, it can help to widen your watchlist using structured filters rather than hunches.
- For investors who care most about resilient balance sheets and consistent fundamentals, start by scanning a list of solid balance sheet and fundamentals (25 results) that can help you focus on businesses with sturdier financial footing.
- If you are hunting for potential mispricings, broaden your opportunity set with a 33 high quality undervalued stocks that surfaces companies where quality and price look more closely aligned with your preferred criteria.
- Those who want growth stories the market has not crowded into yet can review a 16 high quality undiscovered gems that highlights lesser known stocks with stronger underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com