
Boeing (BA) On Orders And Labor Progress Still Faces A Pricey Narrative
Boeing (BA) just tied fresh operational headlines to its stock story, with recent 737 MAX technical scrutiny and a tentative labor deal arriving alongside new aircraft orders and a major aerospace training investment.
Against this backdrop of new orders, labor progress and fresh Starliner headlines, Boeing’s share price has drifted lower, with a year to date share price return of down 13.0% and a 1 year total shareholder return of down 8.8%, while the 3 year total shareholder return is positive. This suggests longer term holders have seen modest gains even as near term momentum has faded.
Spot opportunities beyond Boeing by scanning a hand picked 32 high quality undervalued stocks that combine resilient cash flows with balance sheets built to handle the kind of headlines Boeing is working through today.Boeing is trading well below its recent peak, even as orders, labor talks and Starliner headlines keep piling up. Is most of the valuation reset already done, or is the upside still mostly ahead?
Most Popular Narrative: 24% Overvalued
Boeing last closed at $198.07, compared with a fair value of $160.01 in the most followed valuation narrative. This frames the current price as running ahead of that thesis.
The operating recovery is real but incomplete. Commercial Airplanes narrowed its operating margin from negative 5.1% to negative 2.7% on 171 deliveries against 150. The 737 is transitioning to 47 per month from 38 a year ago, with a fourth Everett line activated in July, and management targets 52 next year. The FAA certified the MAX 7 today after nearly a decade, with roughly 30 airframes in storage ready for retrofit.
See why 5 investors see Boeing as 24% overvalued.
According to rcb9, that fair value relies on Boeing lifting revenue at 8% a year, reaching an 8% net margin, and being valued at 23x earnings at the end of the period, all discounted back at 10%. The same narrative contrasts this with what today’s price would need instead, including roughly 9.3% top line growth, a 10% net margin, and a richer 25x multiple, which is closer to the company’s best historical profitability but with a very different balance sheet and share count.
The same writer lists clear break points for that story, such as any single program charge above $1b through 2027, free cash flow for 2026 falling short of the $1b guidance floor, or Commercial Airplanes still sitting in loss making territory by the end of 2027. There is also focus on leverage, with interest expense described as the main drag on net income and progress tied to getting debt below $40b by 2026 while keeping key certification milestones like the MAX 10 and 777X on track.
Result: Fair Value of $160.01 (OVERVALUED)
Still, Boeing’s story can change quickly if another large program charge lands or if key certification milestones slip again and undermine the recovery timeline.
Find out about the key risks to this Boeing narrative.
Another View: SWS DCF Signals Deep Discount
A second lens on Boeing comes from the SWS DCF model. On that framework, the shares at $198.07 are described as trading 48.8% below an estimated future cash flow value of $386.86, which is the opposite conclusion to the 24% overvalued narrative based on earnings and multiples.
Both approaches use detailed assumptions about profit, cash generation and risk, yet they land in very different places. For an investor weighing Boeing today, the key question is which set of cash flow and execution assumptions feels closer to reality.
Look into how the SWS DCF model arrives at its fair value.
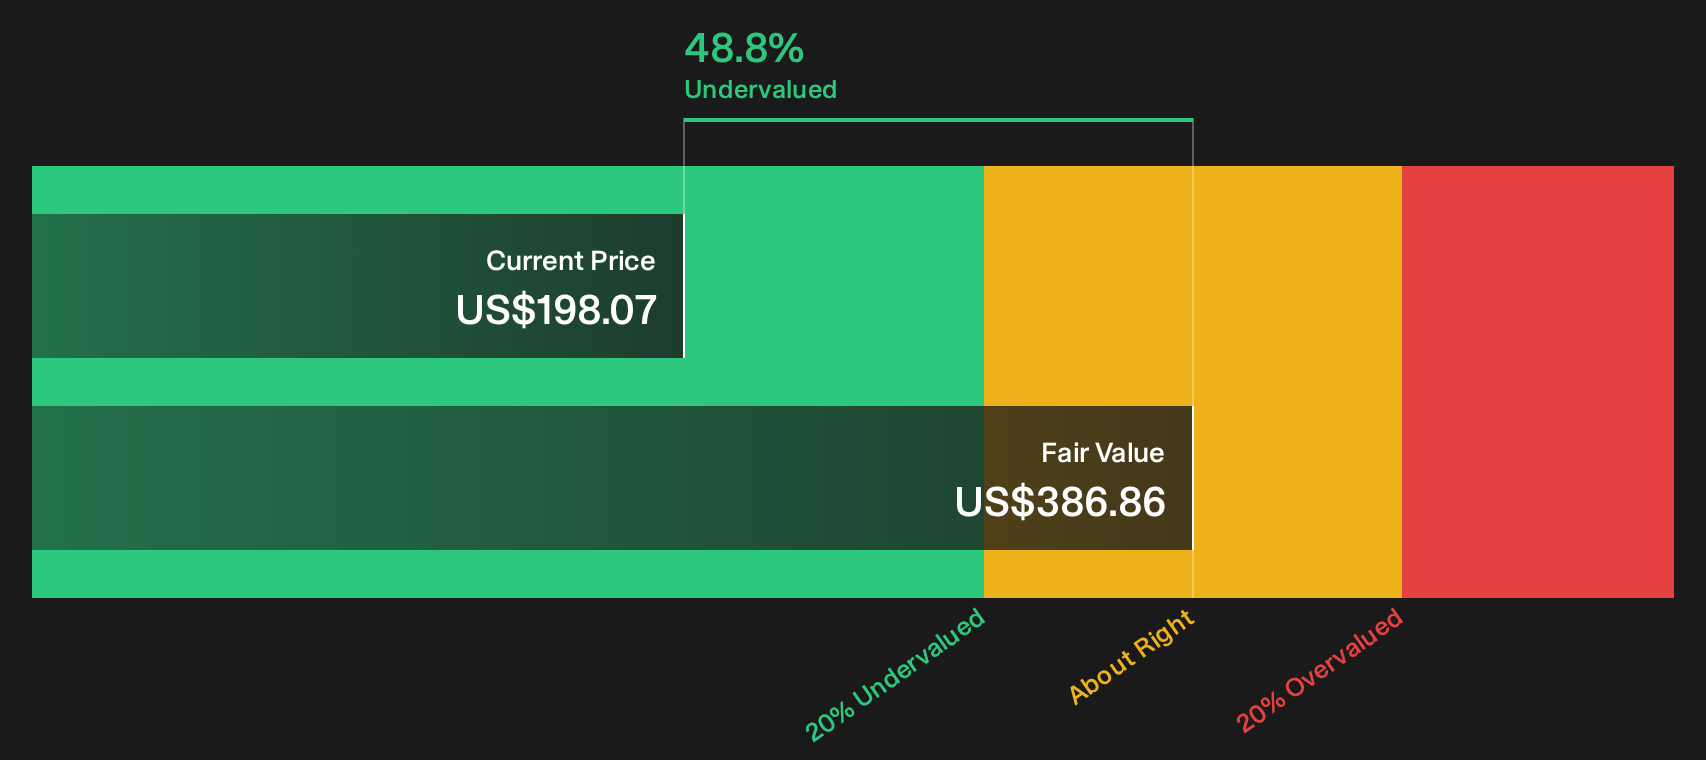
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Boeing for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Boeing’s value can be confusing, so move quickly, review the full data set, and stress test it against your own expectations using the 4 key rewards and 2 important warning signs.
Looking for more Boeing investment ideas?
If Boeing has your attention, do not stop here. Use this momentum to scout a wider field of opportunities that could better fit your risk and return preferences.
- Chase potential mispricing by scanning a focused list of 32 high quality undervalued stocks that combine solid fundamentals with room for a stronger market rerating.
- Lock in income possibilities by checking a curated group of yield focused picks in the 7 dividend fortresses before others crowd in.
- Protect your downside by filtering for resilient balance sheets using the list of solid balance sheet and fundamentals (24 results) that highlight companies built to handle shocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com