
Enova International (ENVA) Could Be 37% Below Fair Value On Reaffirmed Guidance
Enova International (ENVA) reaffirmed its earnings outlook for the third quarter and full year 2026, and guided for revenue growth of about 25% for the quarter and 20% to 25% across the year.
At a share price of US$173.48, Enova International has seen short term momentum weaken, with the 30 day share price return down 25.5% and the 90 day move down 27.9%. This comes even though the year to date share price return is 7.1% and the 5 year total shareholder return is 390.8%, which signals long term investors have still been well rewarded as they weigh the reaffirmed guidance and the scrapped Grasshopper Bancorp deal announced this month.
Scan beyond Enova International to see how other high quality financial stocks with solid fundamentals are setting up right now with the curated 16 high quality undiscovered gems screener.
The recent slide in Enova International raises a simple tension. Are you seeing a reset in how the market feels about the withdrawn Grasshopper deal, or a gap opening up between sentiment and what the business is actually earning?
Most Popular Narrative: 37% Undervalued
Against the latest close at $173.48, the most followed narrative pins Enova International’s fair value around $277. This frames the recent pullback very differently from the headline reaction to the scrapped Grasshopper Bancorp deal.
The analysts have a consensus price target of $277.14 for Enova International based on their expectations of its future earnings growth, profit margins and other risk factors.
In order for you to agree with the analysts, you would need to believe that by 2029, revenues will be $9.6 billion, earnings will come to $665.0 million, and it would be trading on a PE ratio of 13.8x, assuming you use a discount rate of 9.5%.
See why 11 investors see Enova International as 37% undervalued.
Result: Fair Value of $277 (UNDERVALUED)
Still, the whole Enova International story can change quickly if regulators clamp down harder on nonprime lending, or if credit losses climb faster than expected.
Find out about the key risks to this Enova International narrative.
Another Angle On Enova International’s Value
The most popular story around Enova International leans on analyst targets and earnings forecasts, yet the SWS DCF model presents a very different picture. Within that framework, the current share price of $173.48 appears expensive compared with an estimated future cash flow value of $95.50. This raises a key question: which signal is more informative, the earnings narrative or the cash flow analysis?
Look into how the SWS DCF model arrives at its fair value.
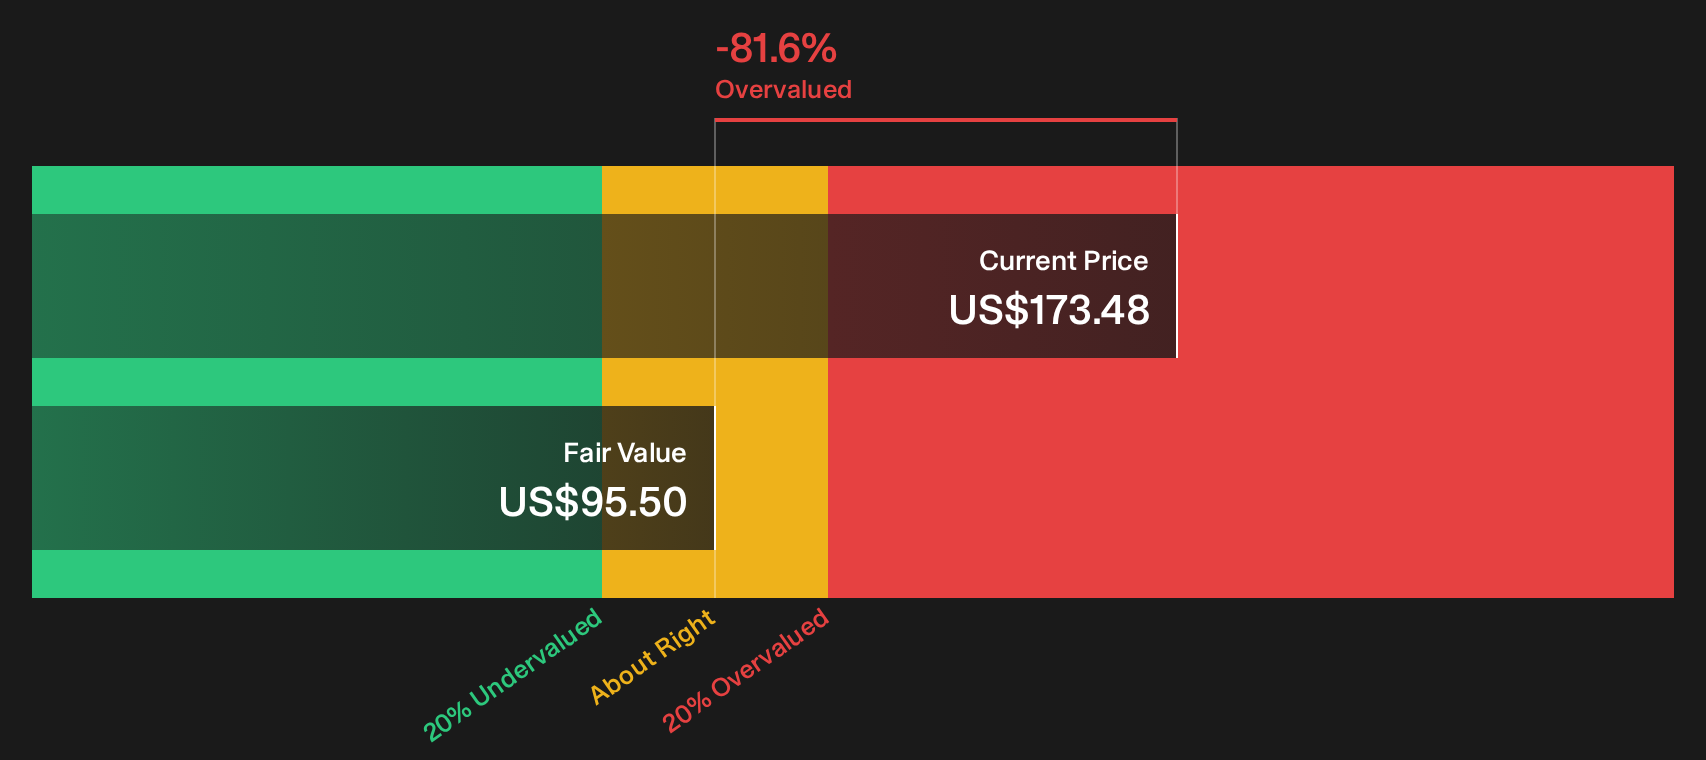
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Enova International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If sentiment in this Enova International story feels split between opportunity and concern, move quickly to test the numbers yourself, weigh the downside scenarios against the upside drivers, and then benchmark your own view against the 3 key rewards and 1 important warning sign.
Looking for more Enova International style investment ideas?
Do not stop with Enova International. Use the Simply Wall St Screener to quickly surface other opportunities that match your risk appetite and return goals.
- Target potential upside by scanning a curated pool of companies that screen as 32 high quality undervalued stocks based on cash flows and balance sheet strength.
- Prioritise resilience first and see which businesses qualify as 30 resilient stocks with low risk scores so you are not relying on a single story to carry your portfolio.
- Raise your quality bar and hunt for under the radar opportunities using a focused 16 high quality undiscovered gems built around strong fundamentals and financial discipline.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com