
PUMA Fragrance Deal Might Change The Case For Investing In Interparfums (IPAR)
- Interparfums announced it has entered into an exclusive worldwide license with PUMA for fragrance creation and distribution through 2037 and secured a 20 year extension of its Roberto Cavalli and Just Cavalli fragrance licenses through 2046.
- The combination of PUMA’s long term fragrance license and the Roberto Cavalli renewal highlights Interparfums’ continued reliance on licensing to support its product pipeline and global reach.
- We will now see how Interparfums’ investment narrative could be reshaped by the long term PUMA fragrance licensing agreement.
Interparfums Investment Narrative Recap
Owning Interparfums means believing its license heavy model can keep turning global fragrance brands into steady cash flow despite consumer and retailer swings. The PUMA deal and Cavalli extensions mainly reinforce that story rather than change it. In the near term, the key swing factor is how well the current launch slate converts into orders in a retail channel that can still lean toward destocking.
The biggest risk remains dependence on a handful of licensed labels at a time when trends, pricing pressure from online channels, and demand for cleaner formulas can move quickly. These long dated agreements help reduce contract risk, but they do not remove execution risk on product design, marketing, and digital reach.
The PUMA agreement looks most relevant to the current catalyst mix. Management is already investing in e commerce and social platforms such as Amazon and TikTok, and a global sports lifestyle partner gives Interparfums more to work with in those channels. The planned 2027 launch gives investors a clear operational milestone to watch.
Execution around PUMA will sit alongside existing priorities such as supply chain tweaks, regional expansion, and supporting brands including Longchamp, Lacoste, and Jimmy Choo. The way Interparfums sequences PUMA with its other licenses could influence how stable margins and cash generation look over the next few years.
Interparfums Earnings And Revenue Set Against Long Term Licensing Bets
Analysts currently frame Interparfums' long dated PUMA and Cavalli agreements against a financial path that points to 5.7% yearly revenue growth over the next three years. Consensus earnings forecasts sit at US$184.4 million by 2029 versus earnings today of US$167.8 million, which implies an increase of about US$16.6 million. On that view, the business would be generating US$1.8b in revenue and US$184.4 million in earnings in 2029. This means the projected profit step up is relatively modest compared with the planned expansion of the licensed fragrance line up.
Uncover why Interparfums' fair value indicates a 7% potential upside to its current price, which could narrow quickly.
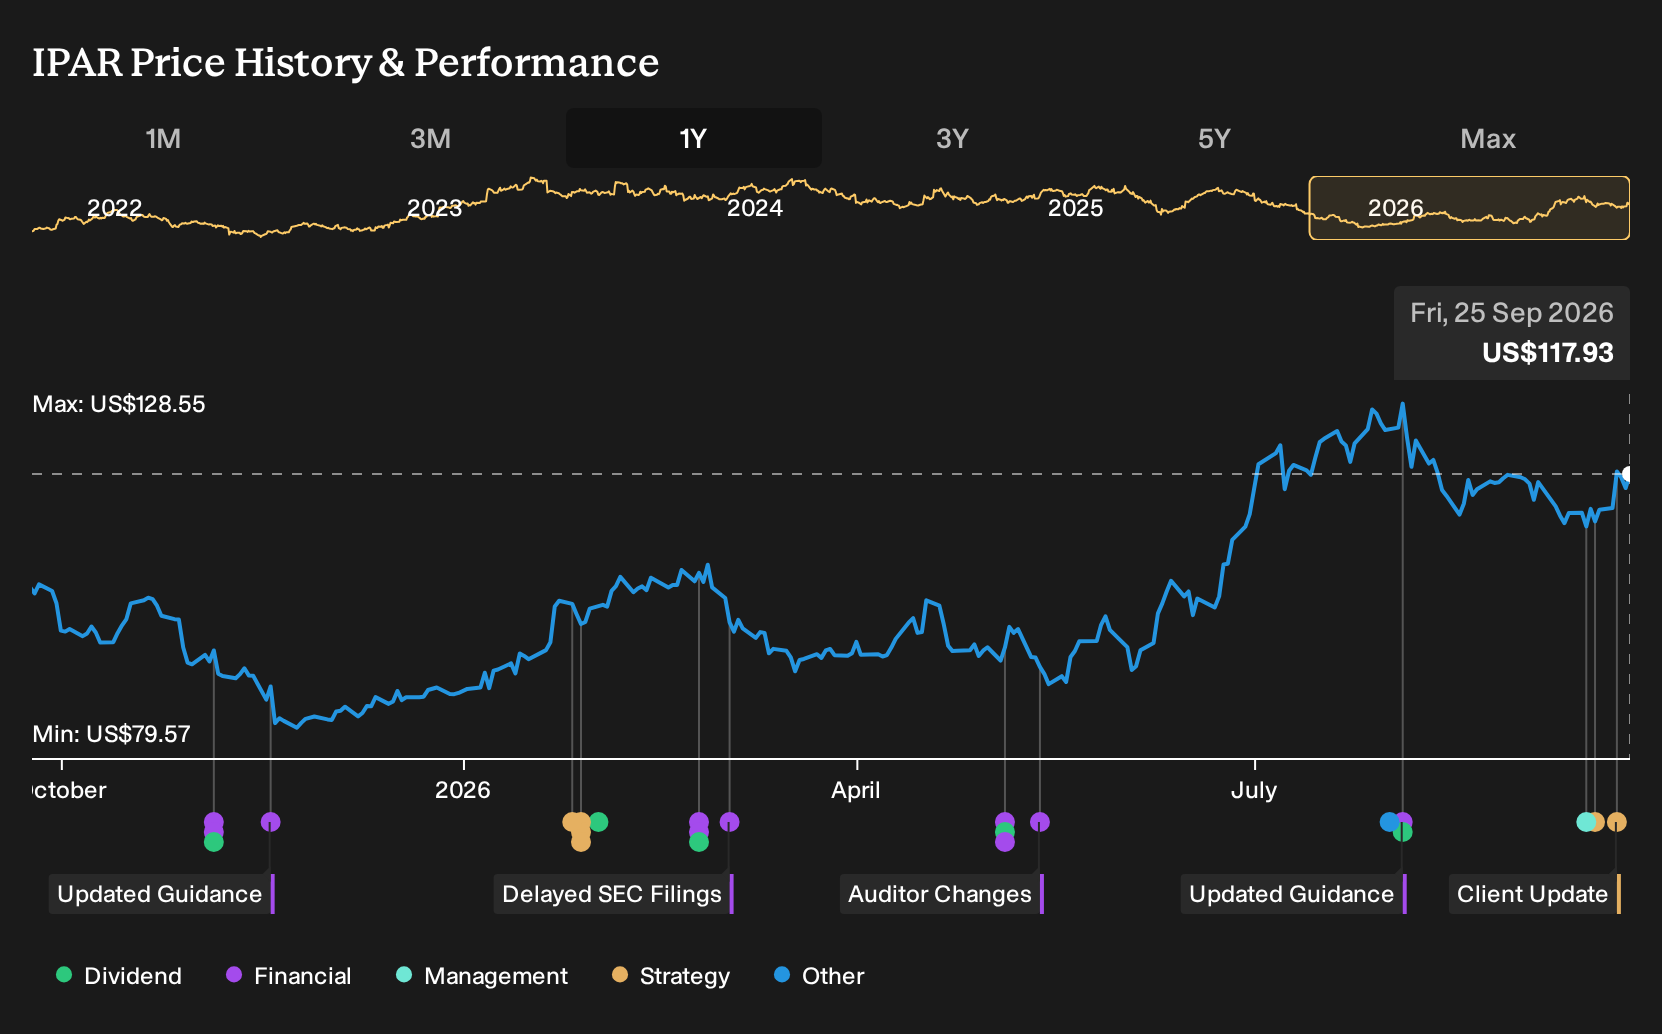
Exploring Other Perspectives
You also need to factor in a different catalyst. The most bearish analysts worried that heavy 2027 launch clustering could backfire, with only 3.5% annual revenue growth and earnings of about US$188.6 million on US$1.7b of sales by 2029. Their view before the news was more cautious, so the PUMA and Cavalli deals might eventually shift that narrative.
Explore 5 other Interparfums fair value estimates, including one that suggests as much as 71% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Interparfums research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Interparfums. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Interparfums' overall financial health at a glance.
Looking For More Investment Ideas Beyond Interparfums?
Once you have formed a view on Interparfums, it can help to cross check that thesis against other businesses with different balance sheet profiles, payout policies, or potential mispricings. A quick pass through a few targeted stock lists can surface candidates for deeper research that fit your risk tolerance and income or growth priorities.
- If you want ideas where price and fundamentals appear out of sync, start with our curated set of companies flagged as potentially mispriced using the 32 high quality undervalued stocks.
- Income focused readers who care about smoother return profiles can scan for payout heavy businesses in the 8 dividend fortresses to see which ones might merit a closer look.
- For a focus on resilience and financial strength, filter for companies with cleaner balance sheets and sturdier fundamentals using the list of solid balance sheet and fundamentals (24 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com