
Can CEVA (CEVA) Justify Its Valuation On Leadership Changes In Connectivity And Sensing?
CEVA (CEVA) has just reshaped its senior ranks by appointing industry veteran Ziv Hammer to a newly created role: Executive Vice President, Connectivity & Sensing, which unifies key wireless, sensing and CTO functions.
CEVA’s latest leadership reshuffle follows a sharp move in the shares, with a 30 day share price return of 33.48% and a year to date share price return of 61.46%. This comes even though the 90 day share price return declined 23.24%, while the 1 year total shareholder return of 39.07% and 3 year total shareholder return of 85.74% point to momentum that has been building over a longer stretch.
Scan beyond CEVA and see how other semiconductor and connectivity plays line up by reviewing the hand picked 85 AI infrastructure stocks that is now moving on investor radars.
After a surge that pushed CEVA shares sharply higher in a short window, investors may be asking whether recent gains already reflect the story or if the current price still leaves meaningful upside on the table.
Most Popular Narrative: 26% Undervalued
On the most followed view of CEVA, a fair value of $48.88 sits above the last close at $36.20, which puts the recent rally in a different light and draws attention to what might be driving that valuation gap.
Accelerating customer adoption of CEVA's Edge AI NPUs (as evidenced by multiple new, high-impact licensing deals and the integration of NeuPro architectures across diverse markets like audio, video, and infrastructure) lays the foundation for materially higher royalty revenue per device as these AI-enabled products ramp into mass production over the next 18 to 24 months.
See why 7 investors see CEVA as 26% undervalued.
Result: Fair Value of $48.88 (UNDERVALUED)
Still, CEVA’s reliance on a small pool of large customers, along with its current net loss of $10.976 million, keeps execution and profitability firmly in focus.
Find out about the key risks to this CEVA narrative.
Another View on CEVA’s Valuation
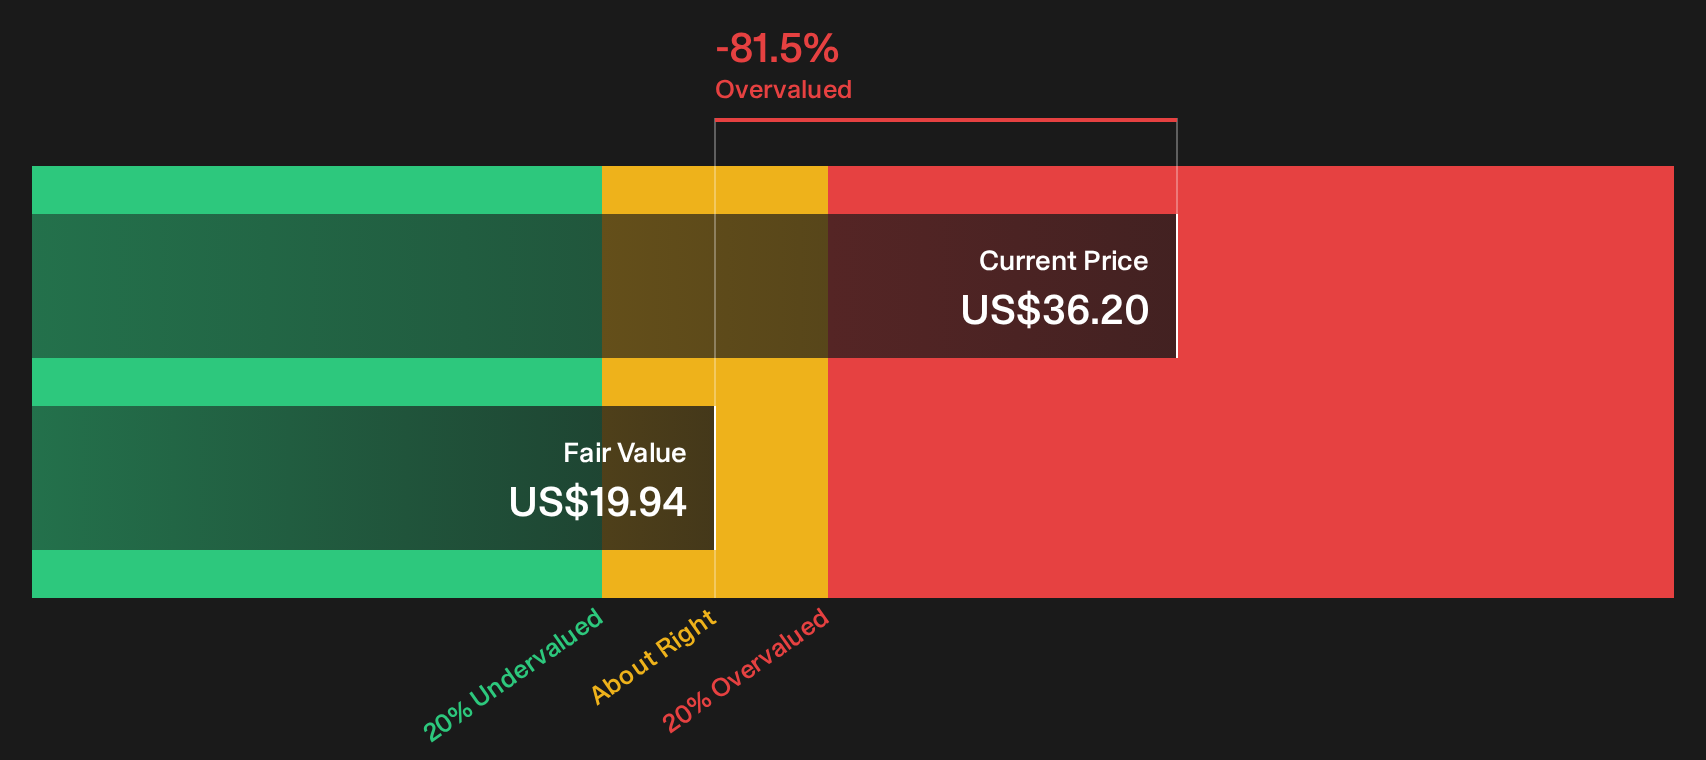
The analyst narrative refers to a fair value of $48.88, yet the SWS DCF model points in a different direction. On that cash flow view, CEVA at $36.20 trades above an estimated future cash flow value of $19.94, which highlights potential downside rather than upside. Which lens do you rely on more when the signals clash?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on CEVA’s value and risk profile can be confusing, so move quickly, review the full data set, and then weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond CEVA?
Do not stop your research with CEVA alone. Broader opportunity often sits in places you have not checked yet, and you do not want to miss them.
- Target potential mispricings by scanning companies that combine quality metrics with appealing valuations through our 32 high quality undervalued stocks.
- Strengthen your downside protection by focusing on businesses with robust finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for underfollowed opportunities that larger investors may overlook with the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com