
China Modern Dairy Holdings (SEHK:1117) Rallies As Valuation Models Pull In Opposite Directions
China Modern Dairy Holdings (SEHK:1117) has drawn fresh attention after its latest trading session, with the share price closing at HK$1.535 and recent returns showing a mixed short term and longer term pattern.
Across recent periods, China Modern Dairy Holdings has combined a 56.63% 90 day share price return with a 20.87% 1 year total shareholder return, which suggests momentum has been building, even though the year to date share price return is down 5.25%.
Scan beyond China Modern Dairy Holdings and compare its recent momentum with a curated group of 193 high quality undervalued stocks that also pair stronger recent returns with solid fundamentals.
After a sharp 90 day climb but only moderate 1 year progress, China Modern Dairy Holdings now sits at a crossroads. Has most of the rerating already played out, or does valuation still point to meaningful upside ahead?
Preferred Price-to-Sales of 0.8x: Is it justified?
On simple sales based metrics, China Modern Dairy Holdings trades on a P/S ratio of 0.8x, which screens as expensive relative to both peers and the wider Hong Kong food sector despite the recent share price reset to HK$1.535.
P/S compares the value the market assigns to a business with the revenue it generates. It is a straightforward way to see how much investors are willing to pay for each unit of sales. For a dairy farming and raw milk producer like China Modern Dairy Holdings, where earnings are currently loss making and margins are under pressure, sales based valuation often becomes the default yardstick.
China Modern Dairy Holdings carries a richer P/S tag than both its direct peer group average of 0.6x and the broader Hong Kong Food industry on the same 0.6x level. This signals investors are willing to pay more for each dollar of its revenue than for competitors. Yet that premium sits only slightly below the SWS fair P/S estimate of 0.9x, which suggests the market pricing is already close to the level the fair ratio model indicates it could move toward if assumptions hold.
Explore the SWS fair ratio for China Modern Dairy Holdings.
Result: Price-to-sales of 0.8x (OVERVALUED)
Still, the story around China Modern Dairy Holdings can change quickly if loss making net income persists or if raw milk demand softens from key Mainland China customers.
Find out about the key risks to this China Modern Dairy Holdings narrative.
Another view on China Modern Dairy Holdings valuation
There is a very different message coming from the SWS DCF model. On that framework, China Modern Dairy Holdings at HK$1.54 is described as trading well below an estimated future cash flow value of HK$14.31. The gap is large enough to make the first P/S based verdict look conservative. Which lens do you trust more when the signals clash this sharply?
Look into how the SWS DCF model arrives at its fair value.
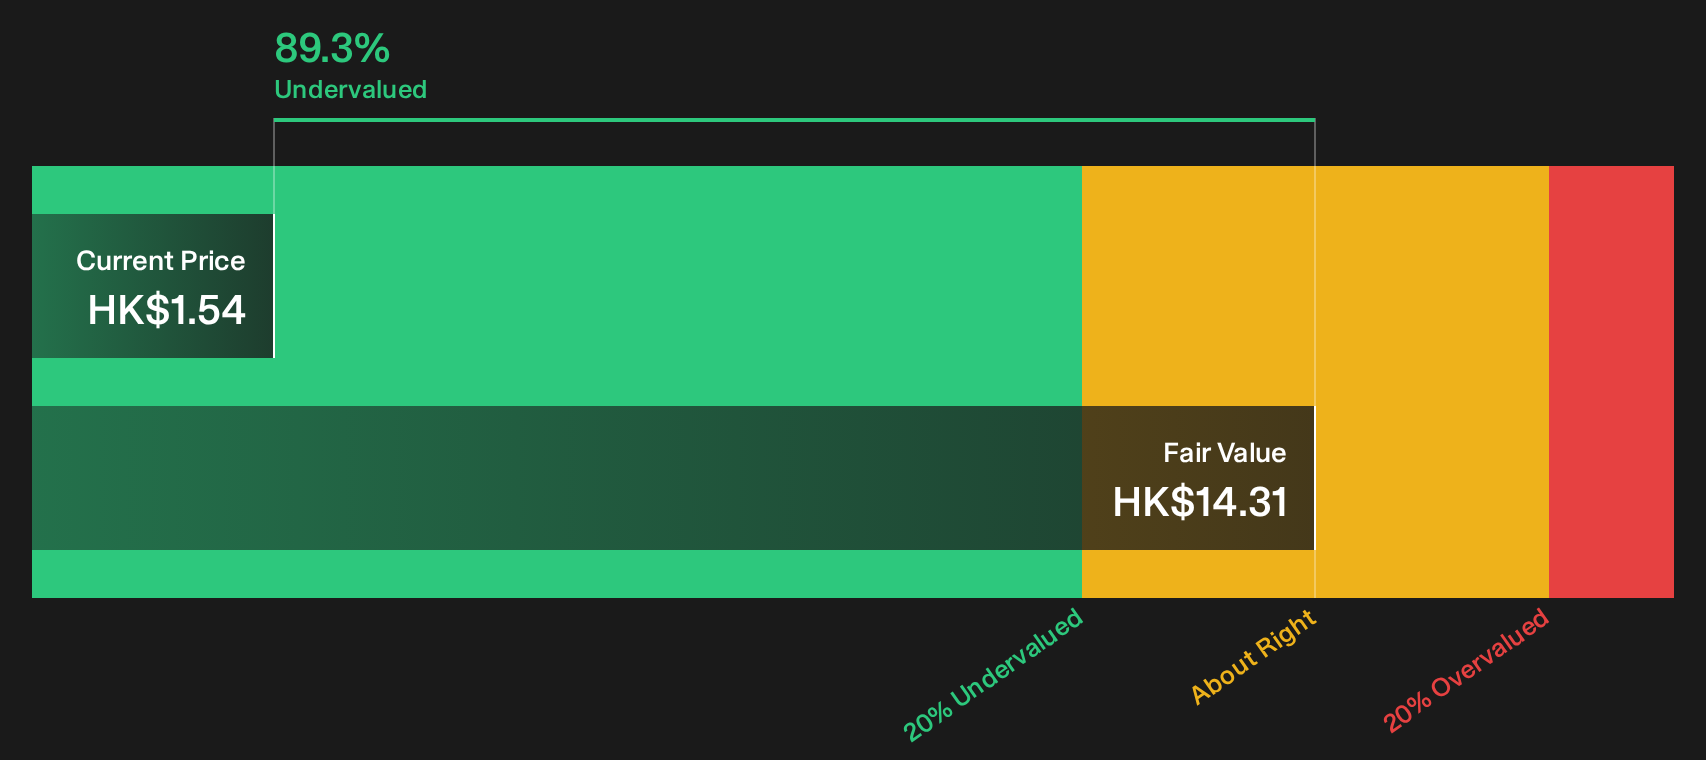
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Modern Dairy Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 193 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the market is being too harsh or not harsh enough on China Modern Dairy Holdings after these conflicting signals? Act quickly, review the underlying data for yourself, and weigh up the 3 key rewards.
Looking for more ideas beyond China Modern Dairy Holdings?
If China Modern Dairy Holdings has sparked fresh questions about value, do not stop here. Broaden your watchlist with a few focused shortlists that keep quality, price and resilience front of mind.
- Spot potential turnaround opportunities early by scanning a tight group of 126 elite penny stocks with strong financials with stronger financials than typical low priced shares.
- Zero in on attractively priced businesses by reviewing a curated set of 193 high quality undervalued stocks that combine healthier balance sheets with more appealing fundamentals.
- Prioritise resilience and capital preservation by checking a filtered pool of 226 resilient stocks with low risk scores designed to limit unpleasant surprises when conditions get tougher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com