
Should NDA Filing Require Action From Xenon Pharmaceuticals (XENE) Investors?
- Xenon Pharmaceuticals has submitted an NDA to the FDA for azetukalner in focal seizures, supported by positive Phase 2b and Phase 3 data and more than 1,500 patient years of exposure.
- The firm has temporarily paused enrollment in major depressive disorder and bipolar depression trials to reassess dosing around neuropsychiatric side effects. This directly affects how investors think about azetukalner’s broader commercial potential beyond epilepsy.
- We will now look at how Xenon Pharmaceuticals’ investment narrative could shift as azetukalner advances in epilepsy while psychiatry enrollment pauses.
Scan late stage neurology pipelines beyond Xenon Pharmaceuticals by reviewing our hand picked 16 high quality undiscovered gems, which are also pushing towards key regulatory and clinical milestones.
Xenon Pharmaceuticals Investment Narrative Recap
For Xenon Pharmaceuticals, investors need to believe azetukalner can become a meaningful epilepsy franchise and eventually support a shift from zero revenue to a commercial business. The fresh NDA filing in focal seizures keeps that core path intact and gives the company a concrete regulatory milestone to work toward in the near term.
The main near term swing factor is how regulators respond to the NDA and how cleanly the remaining epilepsy Phase 3 studies execute. The psychiatry enrollment pause raises the biggest current risk, since any prolonged delay or dose related complication could blunt the longer term pipeline in a product story that many investors are watching.
The most relevant development for that debate is the voluntary pause in new enrollment for the Phase 3 MDD and BPD trials. Management has tied this to neuropsychiatric adverse events that are described as consistent with azetukalner’s known profile, and existing participants will keep dosing, which preserves an opportunity to gather more data.
Operationally, this means epilepsy continues as the lead value driver, while mood disorder indications carry more uncertainty on timing and label scope. X-NOVA2 is already about 80% enrolled and still expected to read out topline data in early 2027. Psychiatry therefore remains in play as a future catalyst, but with a more visible execution and safety risk attached.
Xenon Pharmaceuticals’ current analyst framework points to forecast revenue of US$449.0 million and earnings of US$79.2 million by 2029. This implies a move from today’s earnings loss of US$409.2 million to a profit and an earnings swing of about US$488.4 million, alongside a very large cumulative step up in annual revenue from a zero base.
Uncover why Xenon Pharmaceuticals' fair value indicates a 105% potential upside to its current price that could close faster than investors expect.
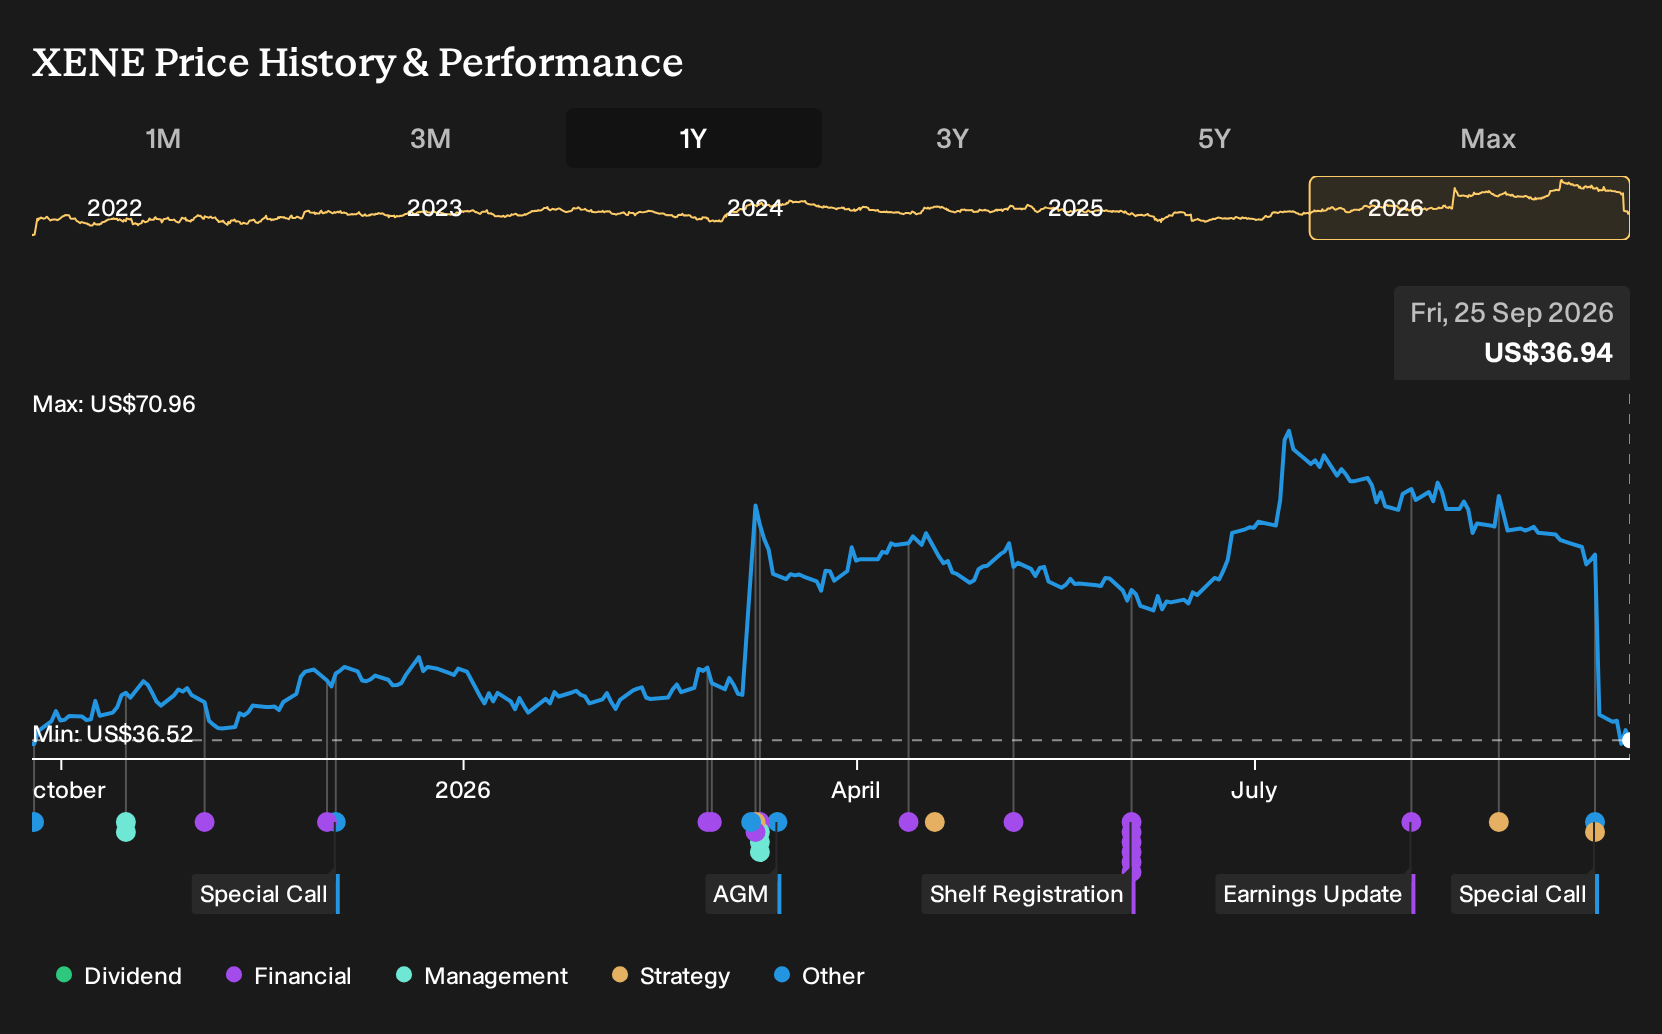
Exploring Other Perspectives
One alternate view puts psychiatry as the real swing factor for Xenon Pharmaceuticals. The most optimistic analysts were sketching out revenue of about US$905.1 million and earnings of US$18.3 million by 2029, backed by a very high implied P/E. Those forecasts came before this NDA update and enrollment pause, so opinions may shift.
Explore 2 other Xenon Pharmaceuticals fair value estimates, including one that suggests as much as 1047% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Xenon Pharmaceuticals research is our analysis highlighting 2 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for Xenon Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Xenon Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Xenon Pharmaceuticals?
If the Xenon Pharmaceuticals story has you thinking about portfolio balance, it can help to line it up against other opportunities with very different profiles. The Simply Wall St Screener lets you quickly sort through companies by quality, risk, income profile, and more, so you can stress test your own thesis rather than relying on a single stock.
- For investors who want potential upside paired with robust finances, check out our list of solid balance sheet and fundamentals (24 results) to help you focus on businesses with stronger fundamentals behind them.
- If income is a priority and you are hunting for reliable cash returns, use the 8 dividend fortresses to focus on higher yielding payout opportunities.
- When capital preservation matters just as much as return potential, narrow your watchlist with the 30 resilient stocks with low risk scores to aim to limit exposure to companies with weaker risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com