
Is Ingevity (NGVT) Fairly Valued As It Nears The End Of Its Portfolio Reset?
Ingevity (NGVT) is back in the spotlight as it prepares to present at the Water Tower Research Virtual Insights Conference on September 23, 2026, with investors watching its ongoing portfolio reshaping.
Ingevity shares have gained a 21.48% year to date share price return and delivered a 33.92% total shareholder return over the past year. The recent 5.86% 7 day share price return hints that investors are warming to the portfolio overhaul, even though the 90 day share price return is slightly down 2.24%.
Scan for other materials stocks reshaping their portfolios and tightening balance sheets with a curated short list of 16 high quality undiscovered gems that echo Ingevity's current playbook.
The recent climb in Ingevity’s share price could mark investors finally pricing in the reshaped portfolio rather than just chasing a mood shift. The valuation work now is to separate sentiment from what the business currently supports.
Most Popular Narrative: 18% Undervalued
Ingevity’s most followed valuation narrative puts fair value at $89 per share compared with the recent $73 close, which implies investors are still assigning a discount to the reshaped portfolio and its cash generation potential.
Accelerated portfolio repositioning and the advanced-stage divestiture of non-core, lower-margin businesses (Industrial Specialties and CTO refinery) are expected to drive a step-change in margin profile. This would enable greater focus and capital allocation toward higher-growth, value-added specialty chemicals, supporting both revenue quality and sustained EBITDA margin improvement. Structural optimization of operational footprint, resulting in lower maintenance CapEx and improved manufacturing efficiency, is freeing up cash flow while lowering cost per unit, directly enhancing free cash flow generation and improving net earnings resiliency.
See why 1 investors see Ingevity as 18% undervalued.
Result: Fair Value of $89 (UNDERVALUED)
Still, the Ingevity narrative could be knocked off course if tariff pressure keeps weighing on Advanced Polymer Technologies margins or if planned divestitures fail to deliver smoother earnings.
Find out about the key risks to this Ingevity narrative.
Another View On Ingevity’s Valuation
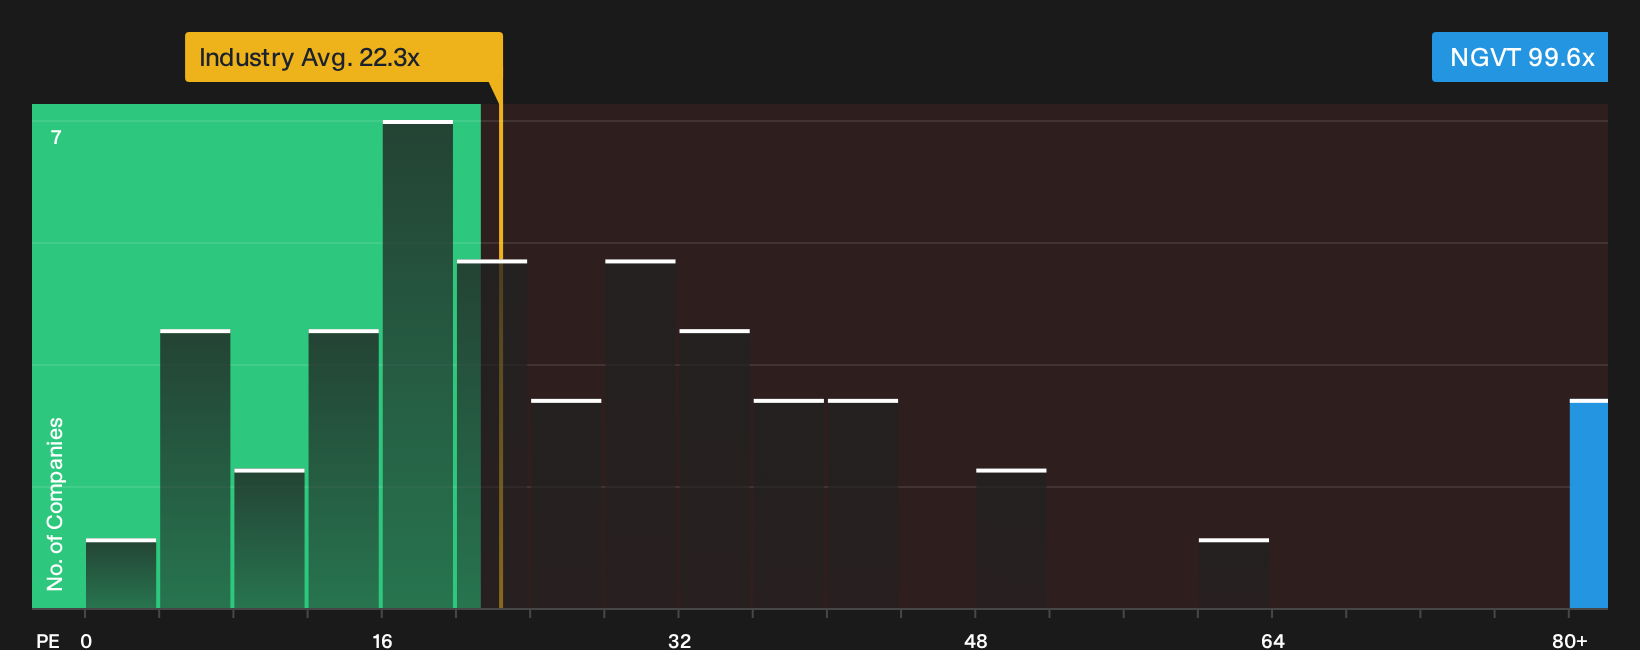
The first narrative frames Ingevity as undervalued against a fair value of $89 per share. A very different picture comes from the P/E lens. The stock trades on a 99.6x P/E, compared with 26.2x for peers, 22.3x for the wider US Chemicals group, and a fair ratio estimate of 33.8x. That gap suggests investors are already paying a rich price for each dollar of earnings, which raises a simple question for you: Is the story strong enough to justify such a premium multiple?
To see how this premium stacks up against the underlying numbers and where the ratio could move, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If sentiment in this Ingevity story feels divided to you, consider acting while the data is fresh and test the thesis against your own risk and reward checklist using the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Ingevity?
Ingevity gives you one angle on portfolio reshaping, but you leave money on the table if you stop your research with a single stock story.
Use the Simply Wall St Screener to pressure test your thinking across different types of opportunities before the market moves on without you.
- Target resilient compounding potential by focusing on businesses that already show disciplined financial strength through a list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced quality where fundamentals and valuation both work in your favor by scanning a curated 32 high quality undervalued stocks.
- Balance return and resilience by reviewing a 30 resilient stocks with low risk scores that filters for companies with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com