
Kinsale Capital Group (KNSL) Pullback Puts Its Fair Value Debate Back In Focus
How the recent slide in Kinsale Capital Group shares reframes the story
Kinsale Capital Group (KNSL) has slipped about 13% over the past month and roughly 16% year to date, pulling the specialty insurer’s stock well off prior highs and reopening questions around valuation.
Short term momentum for Kinsale Capital Group has cooled, with the share price down 7.7% over the past week and 13.2% over the past month, while the 1 year total shareholder return has declined 20.5% even after a 109.1% total shareholder return over five years. Recent weakness around $330.49 suggests investors are reassessing growth prospects and risk, which is why today’s valuation debate feels more pointed than during the earlier multi year upswing.
Scan beyond Kinsale Capital Group and compare this reset with a curated group of insurers and financials that also screen as 32 high quality undervalued stocks.
The pullback now leaves Kinsale Capital Group trading at a discount to both analyst targets and one intrinsic value estimate. The real tension is whether that gap reflects mispricing or a fair response to softer momentum.
Most Popular Narrative: 7% Undervalued
Against Kinsale Capital Group's last close at $330.49, the most followed narrative pegs fair value at $354.78. This frames the recent pullback as a discount rather than a breakdown in the story.
The numbers indicate that Kinsale’s current share price already reflects a full valuation for a high ROE insurer with strong capital returns, so investors are paying for perceived quality rather than a clear margin of safety.
See why 39 investors see Kinsale Capital Group as 7% undervalued.
Result: Fair Value of $354.78 (UNDERVALUED)
Still, that 5.9% rate decline in key lines and the recent pattern of insider selling could unsettle the Kinsale Capital Group narrative if pricing or sentiment weakens further.
Find out about the key risks to this Kinsale Capital Group narrative.
Another view on Kinsale Capital Group’s valuation
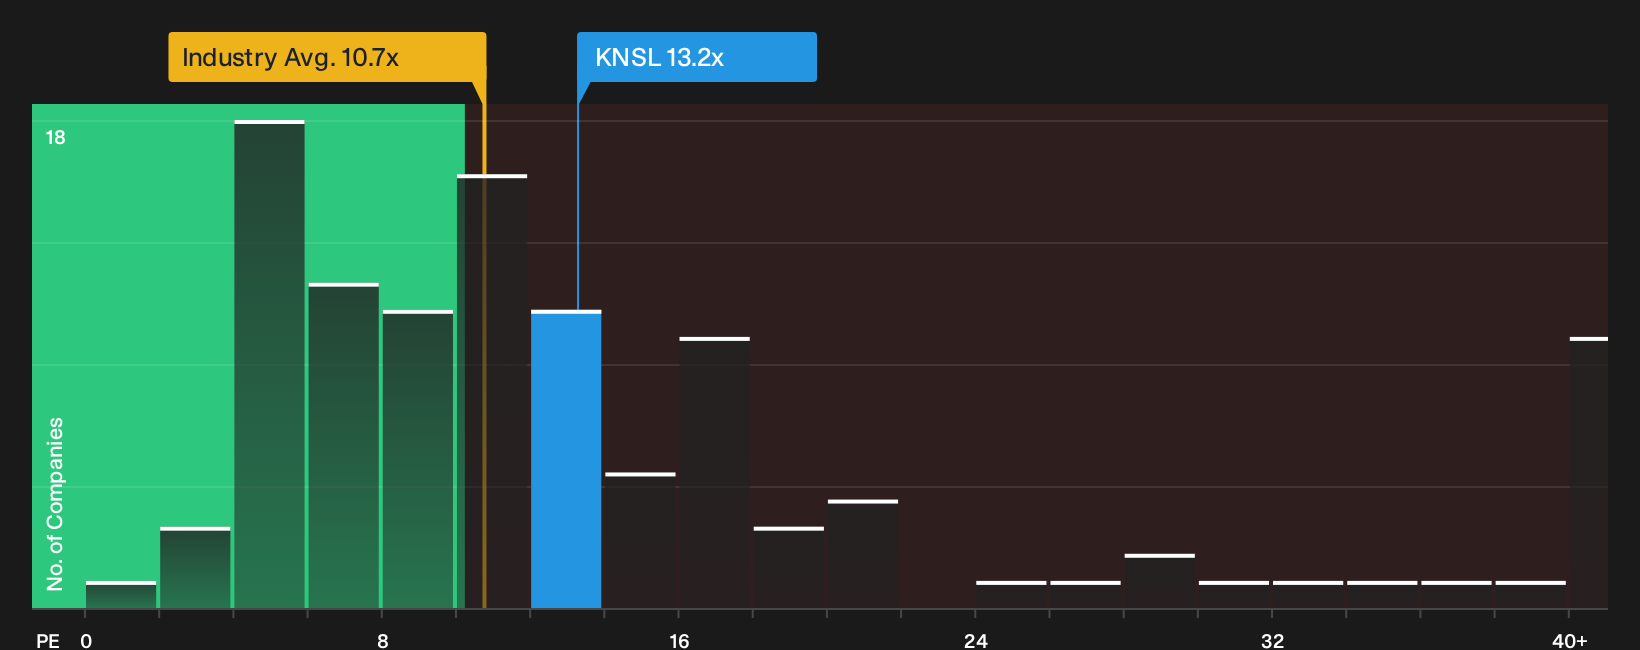
Kinsale Capital Group screens as cheap on cash flows, with our DCF model pointing to a fair value of $562.41, which is well above the current $330.49 share price and flagged as undervalued. Yet the same stock trades on a P/E of 13.2x, which is richer than the US Insurance sector on 10.7x, its peer group on 8.4x and even its own fair ratio of 11.3x. That mix of discounted cash flows and premium earnings multiple raises a practical question for you: which signal matters more in judging risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Kinsale Capital Group's valuation can feel confusing, so move quickly from headline moves to the underlying numbers and form your own judgment. To weigh both sides of the story, review the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Kinsale Capital Group?
If Kinsale Capital Group has you thinking harder about valuation and risk, do not stop here. Broaden your watchlist now so you are not chasing the next move after it happens.
- Target potential mispricing by reviewing a curated set of companies that currently screen as 32 high quality undervalued stocks.
- Strengthen your focus on balance sheet resilience by scanning the list of solid balance sheet and fundamentals (24 results).
- Stay informed by tracking 16 high quality undiscovered gems with strong fundamentals before they appear in every headline.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com