
Cui Dongshu: Auto industry revenue increased 2.9% year on year in January-August, profit decreased 16% year on year
The Zhitong Finance App learned that from January to August 2026, Cui Dongshu published an article saying that from January to August 2026, profits in the electronics industry, driven by artificial intelligence, increased 1.1 times, and profits in the upstream raw materials industry grew at a high rate, which contributed greatly to the improvement of the overall profit of the industry. The automobile industry faced the double pressure of rising costs and weak demand, and profit performance was poor. In August 2026, 2.7 million cars were produced, with sales revenue of 928.1 billion yuan increasing 4.2%, costs of 831.3 billion yuan increasing 5.3%, profit of 37.1 billion yuan increasing 24%, and sales margin of 4%. From January to August 2026, automobile production of 20.31 million units fell 3% year on year, revenue of 706.2 billion yuan increased 2.9% year on year, cost of 6237 billion yuan increased 4% year on year, profit of 253.4 billion yuan decreased 16% year on year, and sales margin 3.6%.
In 2026, various regions vigorously promoted the implementation of the “two new” policies to gradually and effectively release the vitality of domestic demand, but the improvement in efficiency in the automobile industry clearly lags behind other consumer goods. As the country's anti-domestic countervailing efforts continue to advance, the automobile industry is being severely squeezed upstream. The price problem is serious. Oil prices have skyrocketed, profits from non-ferrous metals and semiconductors have skyrocketed, end users have a serious wait-and-see mentality when buying cars, the operating pressure on car companies continues to increase, and high-quality development has been greatly impacted upstream.
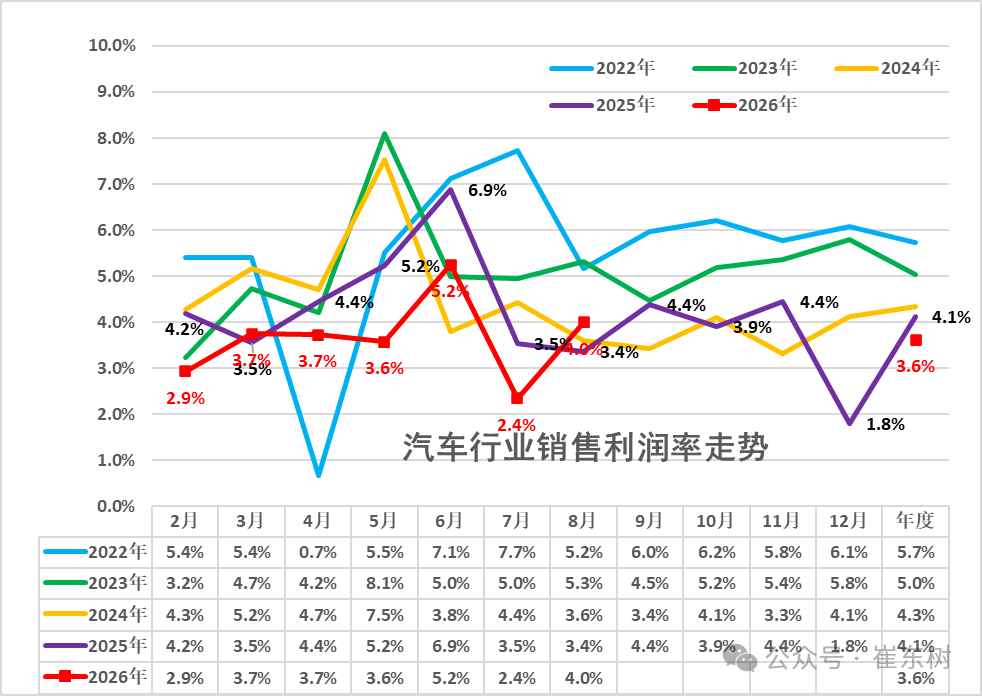
Judging from sales margin trends over the years, the profit performance of the automobile industry has weakened in 2024. The sales margin was only 4.3%, a sharp drop from the historical normal level; in 2025, the industry's sales margin fell to 4.1%. The industry's sales margin fell further to 3.6% in January-August 2026, and 4% in August, better than the lowest monthly performance of 1.8% in December 2025. August of previous years was generally a time when profit margins were low. Fuel vehicle production improved slightly in August of this year, but profit pressure is still huge.
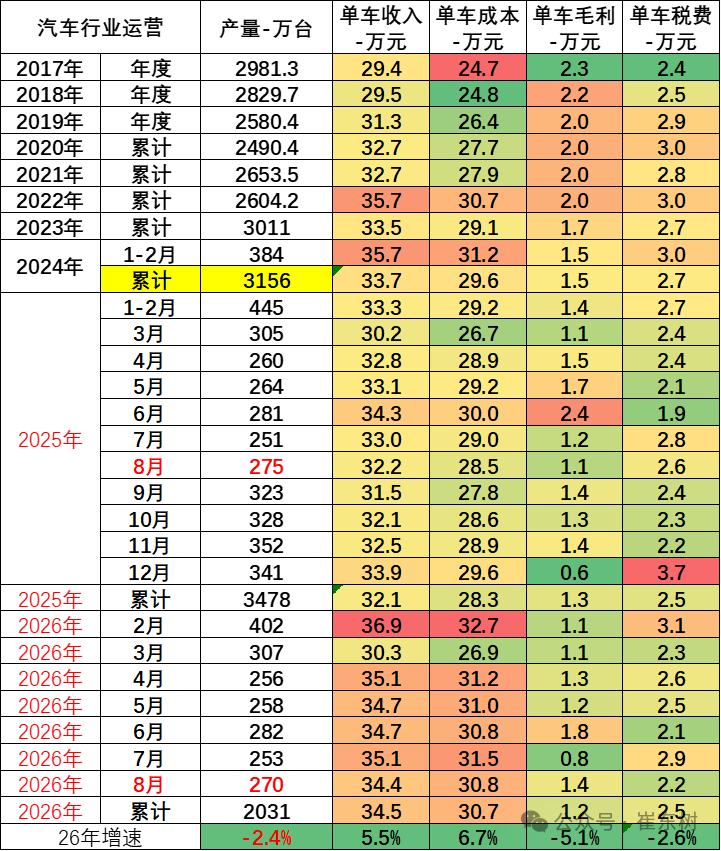
Since production and sales in the automobile industry are basically the same, the statistical caliber is consistent, and there is not much gap between production and sales, we use the output of the National Bureau of Statistics to estimate the Bureau of Statistics's bicycle economic indicators.
In January-August, overall industrial enterprise unit costs were under high pressure. Memory has skyrocketed, the price of lithium carbonate has doubled, commodity prices are running high, and the pressure on raw material costs in the middle and downstream industries has increased. From January to August, the overall bicycle revenue of the automobile industry chain increased by 5.5% to 345,000 yuan (with repeated calculation of the industry chain), bicycle costs increased by 6.7% by 307,000 yuan, bicycle taxes by 25,000 yuan decreased by 2.6%, and gross bicycle profit of the industrial chain by 12,000 yuan decreased by 5.1%.
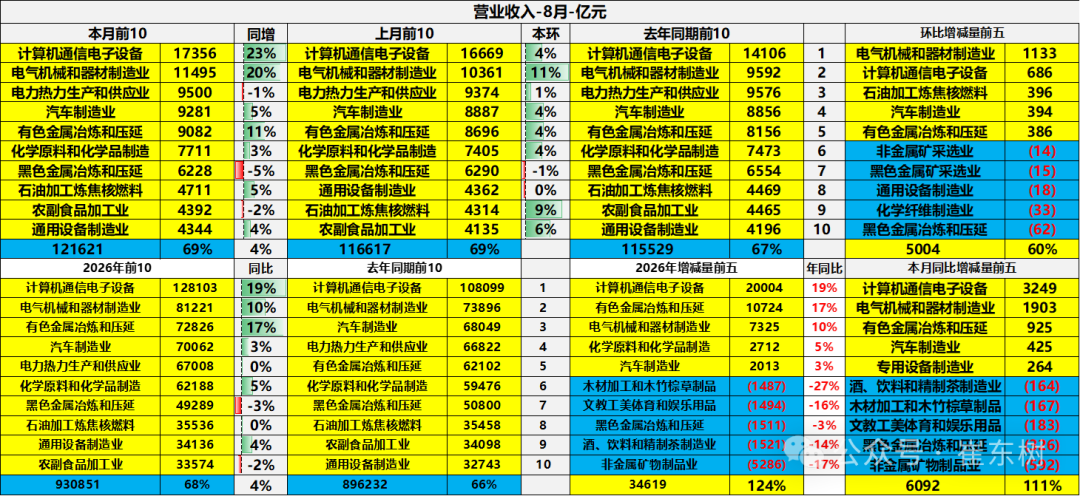
Industrial revenue data above the August scale shows that the industry is hot and cold. The two major tracks, computer communications and electrical machinery, grew at impressive rates, with year-on-year increases of 23% and 20%, driving the growth of the industrial market. The automobile manufacturing industry's revenue for the month was 928.1 billion yuan, up 5% year on year and 4% month on month, achieving a steady recovery, ranking fourth in the industry. However, compared to the electronics and electrical industries, automobile growth was clearly weak. Looking at the cumulative total of the previous eight months, automobile revenue was 706.2 billion yuan, an increase of only 3% over the previous year, and growth momentum was insufficient. Revenue from upstream ferrous metals and other industries has declined, and pressure on raw materials has eased somewhat. Although the revenue side of the automobile industry has maintained positive growth, the ongoing price war has reduced profit margins, showing a typical increase in revenue without an increase in profit. The industry's revenue is picking up, but profit recovery is lagging behind, and profit pressure still requires continued attention.
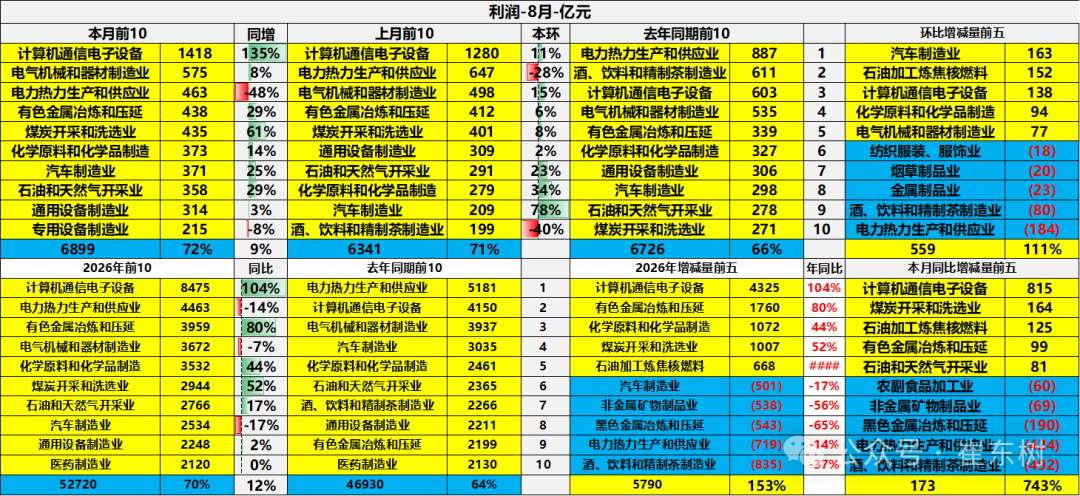
The auto industry's profit recovered sharply from month to month in August, but the cumulative profit still fell 17% year on year, and profit pressure has not abated at all. The automobile industry is being squeezed from both ends at the same time. On the one hand, the prices of electronic components such as memory and chips are rising, and on the other hand, the cost of raw materials such as non-ferrous metals is rising, continuing to erode the profits of car companies. Comparatively speaking, the computer communications industry benefits from an upward chip cycle and explosive profit growth; while automobiles are downstream consumers of chips and non-ferrous metals, the cost side is passively pressured. Although auto profits rebounded in the short term in August, it was more an improvement brought about by the decline in phased promotions, not a fundamental reversal. Fluctuations in chip and non-ferrous prices, compounded by industry price wars, are still the core factors limiting the continued recovery of profits in the automotive industry.
Specific analysis
1. Revenue and profit structure of various economies
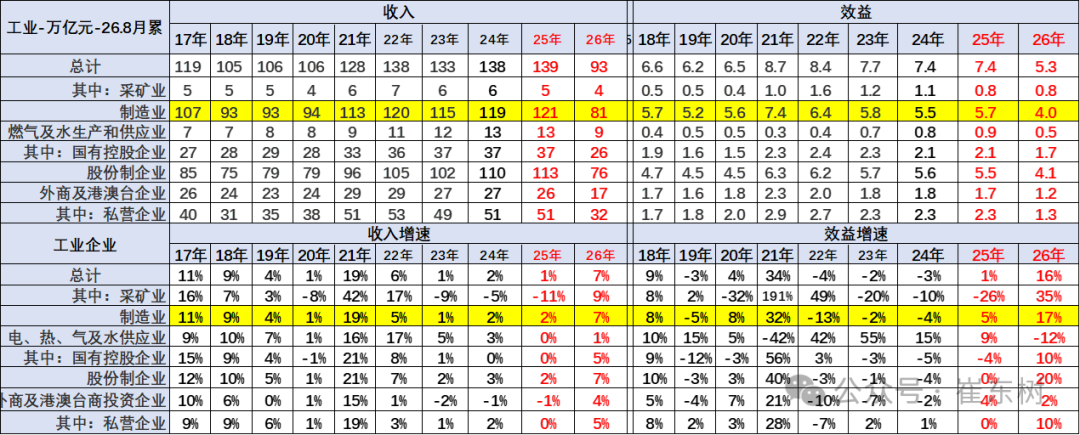
The cumulative revenue of the industry in 2017-2025 remained in the range of 105 trillion yuan to 139 trillion yuan for a long time. The manufacturing industry has always been an absolute pillar, accounting for about 90% of the revenue volume for a long time. In terms of ownership, the revenue scale of joint-stock enterprises led the way; the revenue scale of private enterprises rose steadily, and the volume of foreign companies, Hong Kong, Macao and Taiwan shrank slightly; the total volume of revenue from January to August 2026 was 93 trillion yuan, and revenue from all industries and forms of ownership shrank in half. Overall revenue rebounded to 7% year-on-year. The manufacturing industry also maintained a 7% revenue growth rate, and recovery efforts were strong.
On the profit efficiency side, the overall efficiency of the industry fluctuated between 6.2-8.7 trillion yuan from 2018 to 2025, and fell back to 5.3 trillion yuan in January-August 2026, but the efficiency growth rate rebounded sharply to 16%. Among them, the mining industry increased 35%, and the manufacturing efficiency growth rate reached 17%, becoming the core of profit restoration. By sector, the efficiency growth rate of the mining industry was as high as 35%, and the electricity, heat, and water supply industry turned slightly negative; in terms of ownership, the efficiency growth rate of joint-stock enterprises led the way by 20%, while profits of state-owned enterprises and private enterprises picked up at the same time. The growth rate of foreign-invested enterprises was only 2%, and the profit recovery efforts of different entities were clearly divided.
Revenue growth in the overall industrial sector has been steady this year, and profit performance has also been relatively divided. Among them, the revenue and profits of state-owned enterprises have fluctuated greatly in recent years. Upstream profits are squeezing downstream, mining companies are performing well, and profit growth is very strong.
Note: Underlying data interpretation
The growth rate of indicators such as total profit and operating income of industrial enterprises above scale is calculated on a comparable scale. There are incomparable factors between the data for the reporting period and the same indicator data released last year, and the growth rate cannot be directly compared. The main reason for this is: (1) According to the statistical system, the survey scope of industrial enterprises above scale is adjusted regularly every year. Every year, some enterprises meet the scale standard and are included in the scope of the investigation, others withdraw from the scope of the investigation due to a decrease in scale, and there are also changes such as new enterprises that have been put into operation, bankruptcy, and sales (suspension) sales enterprises. (2) Statistical law enforcement has been strengthened, enterprises found during statistical enforcement inspections that do not meet the requirements of industrial statistics above scale have been cleaned up, and the relevant base figures have been revised in accordance with regulations. (3) Strengthen data quality management and eliminate repeated statistics across regions and industries. According to the latest survey of enterprise organization structures carried out by the National Bureau of Statistics, starting in the fourth quarter of 2017, the repeated calculation of enterprise groups (companies) across regions and industries was examined. (4) After the implementation of the “business to increase” policy, service enterprises switched to value-added tax and the tax rate was lower. Industrial enterprises gradually divested internal non-industrial production and operation activities and switched to the service industry, which reduced the financial data of industrial enterprises. (5) According to the results of the comprehensive survey of the units in the fourth national economic survey, the survey units of industrial enterprises above scale were verified and adjusted.
2. Changes in revenue and profit structure
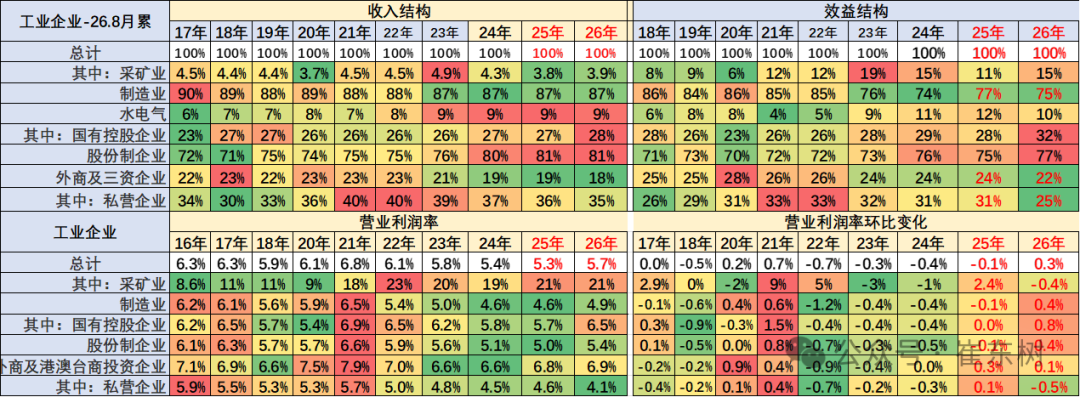
At present, state-owned enterprises are performing very well. The share of revenue and profit continues to grow, and the share of profit has reached 32%, an increase of 4 points. The share of profits of private enterprises fell by 6 points to 25%, and the operating profit margin of 4.1% was lower. The decline in profits of private enterprises was quite obvious compared to last year.
K-type differentiation of profit margin indicators for operating income is mainly due to the high index values of the mining industry and state-owned enterprises such as coal, hydropower, etc. The profit margin of private enterprises is very poor. The profit margin of the manufacturing industry accounts for 75%. Excluding semiconductors, there has been a marked decline recently.
Specific industry analysis
1. Profit differentiation in the mining industry
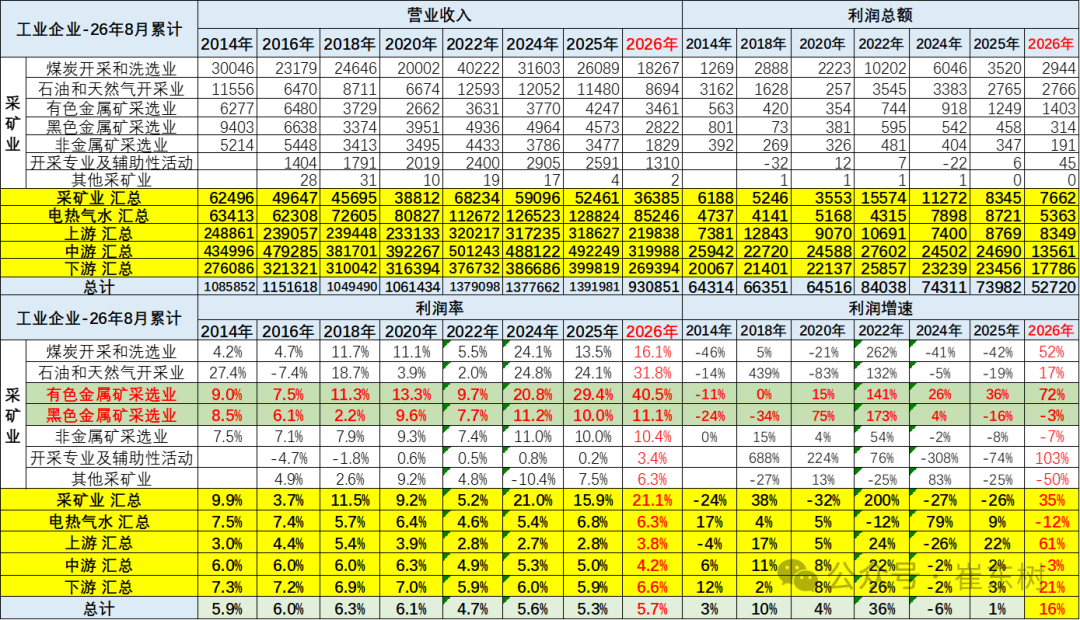
With a high base and rising prices from January to August 2026, mining profits increased by 35%, and there are still very good profits. The profit margin of the mining industry in January-August was also very good at 21.1%.
From January to August 2026, the profit margin of the non-ferrous industry soared to 40.5%, and the profit margin of the petroleum industry was 31.8%. Recently, the profit margin of the petroleum industry has increased astonishingly. Overall mining industry profits remain high. The impact on the downstream is huge.
2. The profit of the water and electricity industry remains high
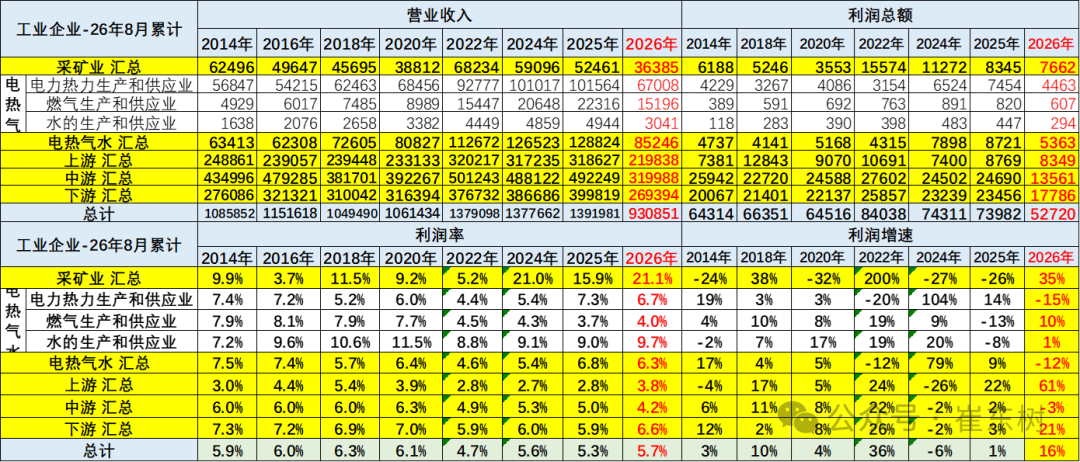
The profit margin in 2026 is 6.3%. Electric heating and water is a highly profitable service industry. Among them, the profit margin of the electric power industry is 6.7%, which is at an all-time high. In 2026, the profit of the electricity industry decreased by 15%, the profit of the water treatment industry increased by 1%, and the profit of the gas industry increased by 10%.
3. Upstream profit improvement
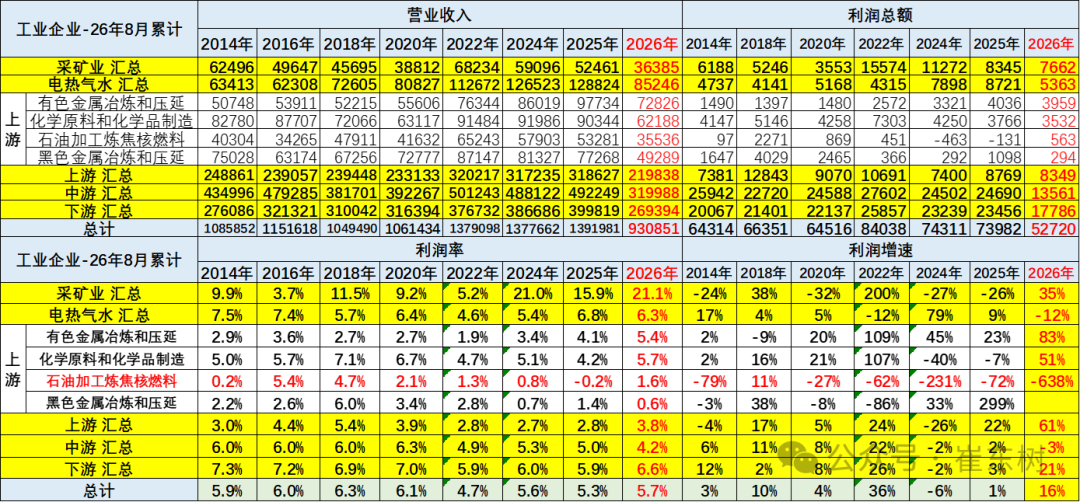
In 2026, the upstream industry experienced high sales revenue and profit growth, and in particular, the profit margin fell to 3.8%. Among them, sales margins, represented by non-ferrous metals, etc., have gradually reached a high level, and the steel industry's profit margin of 0.6% this year is still poor. The profits of industries such as chemical raw materials and non-ferrous metal smelting are quite good.
4. Midstream profit performance is relatively good
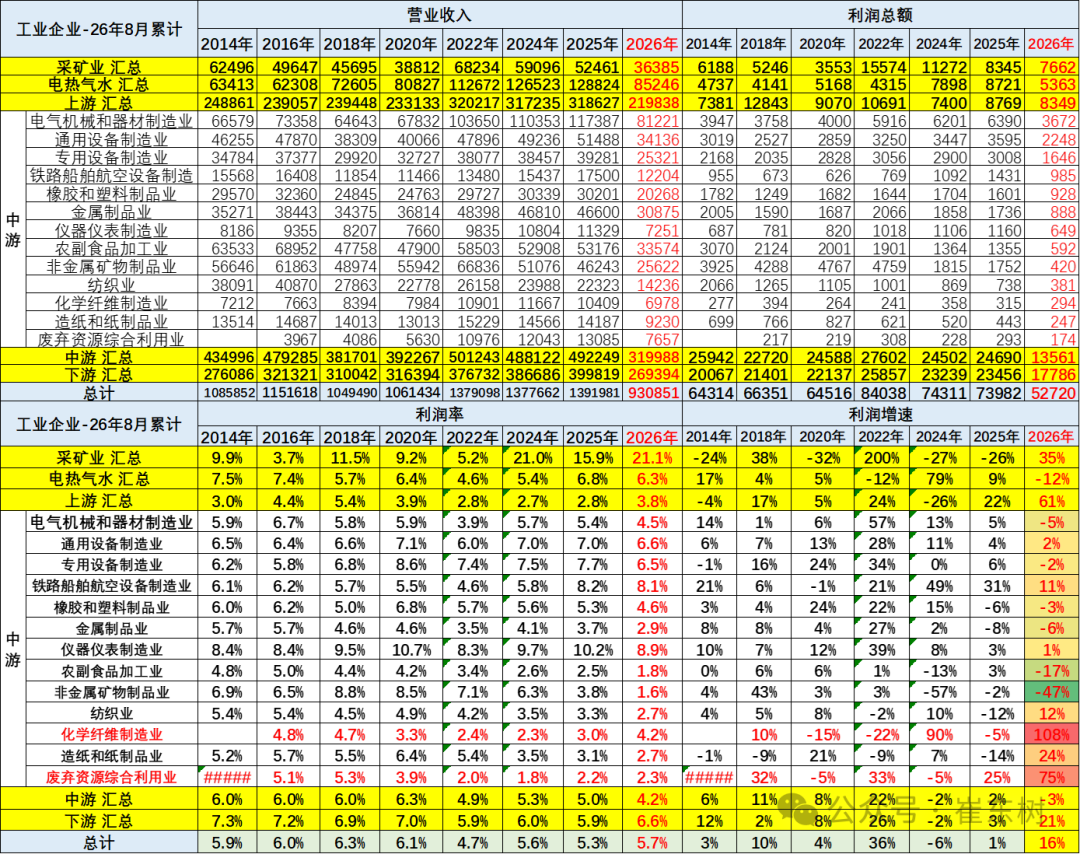
Sales revenue and profit growth in the midstream industry was good from January to August 2026. The sales margin of the midstream industry fell from 6% in 2018 to 4.2% in 2026, and has stabilized recently. Sales margins in major midstream industries have also declined in 2026. The benefits of shipbuilding and railways are good, and profits in the use of waste materials and non-metallic mineral products have increased significantly due to scrapping and renewal subsidies.
5. Gradual improvement of downstream profits
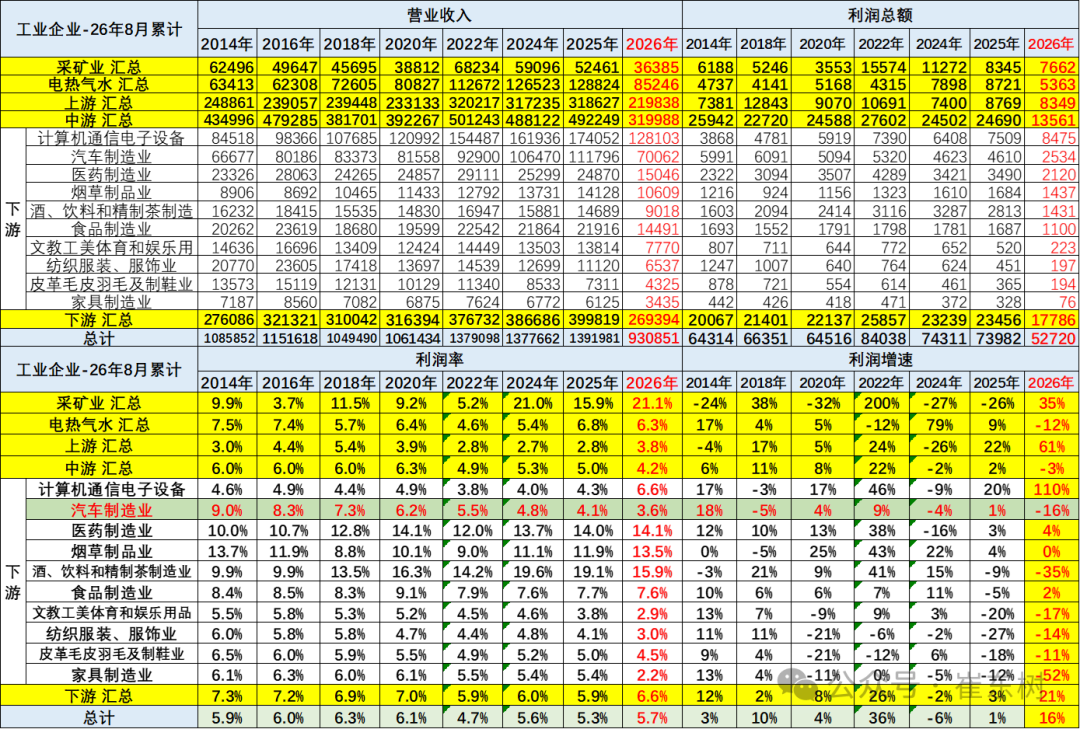
From January to August 2026, the overall profit of the downstream industry increased by 21%, and the profit of the computer communications industry showed an unusually good growth trend of 110%. However, the automobile industry's profit fell 16%, and the sales profit margin was 3.6% (9% in 2014), which is still lower than the overall downstream profit level of 6.6%, and also significantly lower than other downstream companies such as tobacco, alcohol, and pharmaceuticals.
Currently, the main high-profit industries are the tobacco, alcohol, and pharmaceutical industries, and the profits of the alcohol industry are much higher than those of other industries. Profits in the food industry are not strong, but there is also a significant year-on-year increase.
Automotive industry analysis
1. The scale of the automobile industry continues to expand
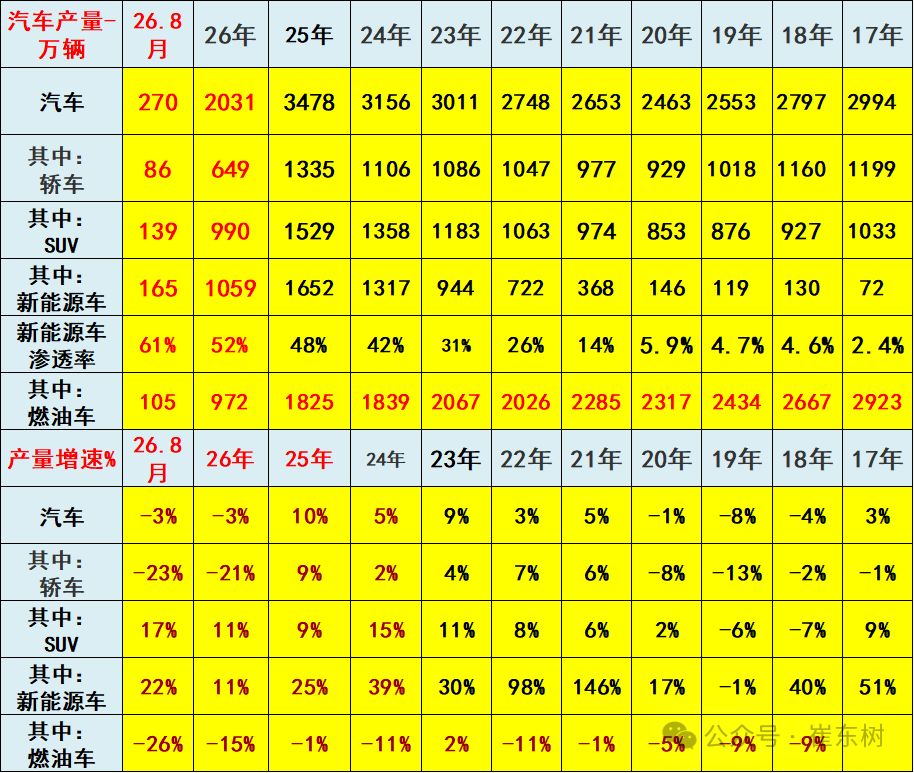
In 2022, automobile production was 27.48 million units, with a year-on-year increase of 3%; production of new energy vehicles was 7.22 million, an increase of 98%, with a penetration rate of 26%; production of fuel vehicles was 2.06 million units, a decrease of 11%.
In 2023, automobile production was 30.11 million units, up 9% year on year; new energy vehicle production was 9.44 million units, up 30% year on year, penetration rate 31%; fuel vehicle production was 20.67 million units, up 2% year on year.
In 2024, automobile production was 31.56 million units, up 5% year on year; new energy vehicle production was 13.17 million units, up 39% year on year, penetration rate 42%; fuel vehicle production was 18.39 million units, down 11%.
In 2025, automobile production was 34.78 million units, up 10% year on year; new energy vehicle production was 16.52 million units, up 25% year on year, penetration rate 48%; fuel vehicle production was 18.25 million units, down 1% year on year.
From January to August 2026, automobile production was 20.31 million units, down 3% year on year; new energy vehicle production was 10.59 million units, up 11% year on year, penetration rate 52%; fuel vehicle production was 9.72 million units, down 15% year on year.
In August 2026, automobile production was 2.7 million units, down 3% year on year; new energy vehicle production was 1.65 million units, up 22% year on year, penetration rate 61%; fuel vehicle production was 1.05 million units, down 26% year on year.
2. The automobile industry is under high pressure on efficiency
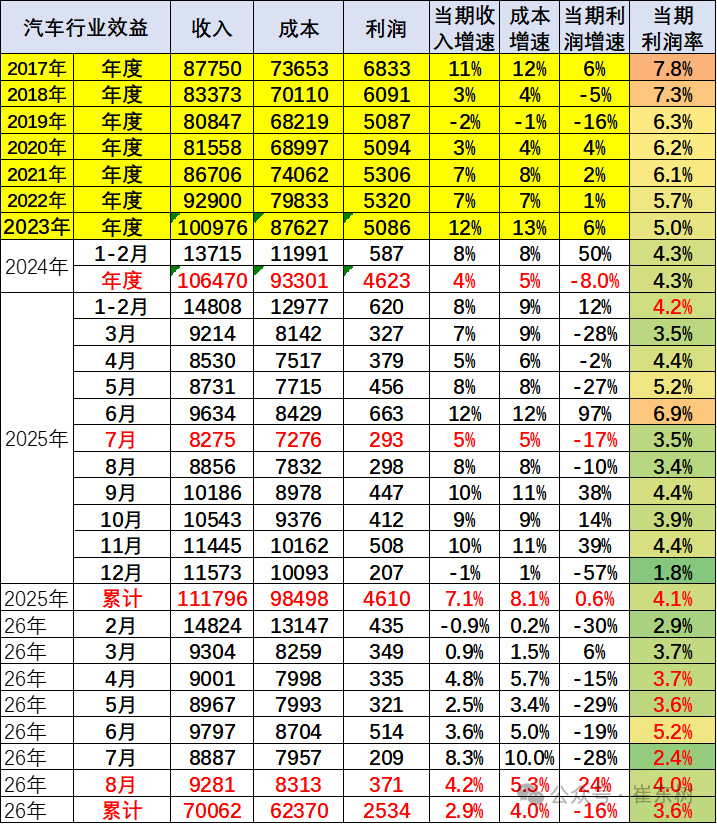
Profits in the automotive industry continue to be under pressure. The industry's profit margin declined all the way from 7.8% in 2017 to only 4.1% for the full year of 2025, and fell further to 3.6% cumulatively in 2026. The core contradiction is that the cost growth rate continues to be higher than the revenue growth rate, showing a typical increase in revenue without an increase in profit. Monthly profit fluctuates sharply, and the gap is huge during the off-peak season. Individual monthly profit margins have even fallen to 2%, and the profit base of the industry is very weak.
From January to August 2026, automobile production fell 3% year on year, revenue of 706.2 billion yuan increased 2.9% year on year, cost 6237 billion yuan increased 4% year on year, profit of 253.4 billion yuan decreased 16% year on year, sales margin 3.6%; of these, automobile production in August was 2.7 million units, sales revenue of 928.1 billion yuan increased 4.2%, cost of 831.3 billion yuan increased 5.3%, profit of 37.1 billion yuan increased 24%, and sales margin 4%.
The root cause is that the fierce price war suppresses the revenue side, and the rigidity of raw materials, R&D, and channels is difficult to reduce. It is already difficult to make money by simply splitting sales; car companies cannot continue to rely on price cuts. The industry needs to shift to supply chain optimization, refined cost control, and rely on technology premiums to improve bicycle profits. If the price inflow continues, the overall profit level of the industry will still be under downward pressure.