
Cousins Properties (CUZ) Could Be 17% Below Fair Value On Dividend News
Cousins Properties (CUZ) highlighted its third quarter income return after the board declared a cash dividend of $0.32 per common share, payable on October 15 to shareholders of record on October 5.
Although the dividend news is in focus, Cousins Properties’ recent price action tells its own story, with the share price at $28.65, a year-to-date share price return of 10.53% and a 3-year total shareholder return of 66.30%, suggesting that momentum has built over the longer stretch even as shorter-term share price moves have softened.
Scan beyond Cousins Properties and line up other dividend-focused real estate plays with resilient balance sheets using our hand-picked list of solid balance sheet and fundamentals (24 results) for comparison.
For Cousins Properties, a 10.53% year to date gain alongside softer 30 and 90 day returns raises a simple test. Are you seeing business resilience finally recognised, or sentiment cooling after a strong multi year run as valuation stretches?
Most Popular Narrative: 15% Undervalued
Cousins Properties is framed as undervalued in the most followed narrative, with a fair value estimate of $33.64 versus the latest close at $28.65. That gap rests on how Sun Belt office demand and capital recycling are expected to play out over time using a discount rate of 8.05%.
The migration of businesses and populations to Sun Belt cities is continuing to drive above-average demand for high-quality office space in Cousins' core markets (Atlanta, Austin, Dallas, Charlotte, Tampa, Phoenix), as evidenced by robust leasing activity, strong net absorption, and new-to-market tenant requirements. This is likely to support higher occupancy rates and drive revenue growth.
See why 3 investors see Cousins Properties as 15% undervalued.
Result: Fair Value of $33.64 (UNDERVALUED)
Still, the narrative around Cousins Properties can be tested quickly if Sun Belt leasing cools or if large tenants reduce space and lower cash flow expectations.
Find out about the key risks to this Cousins Properties narrative.
Another View on Cousins Properties Valuation
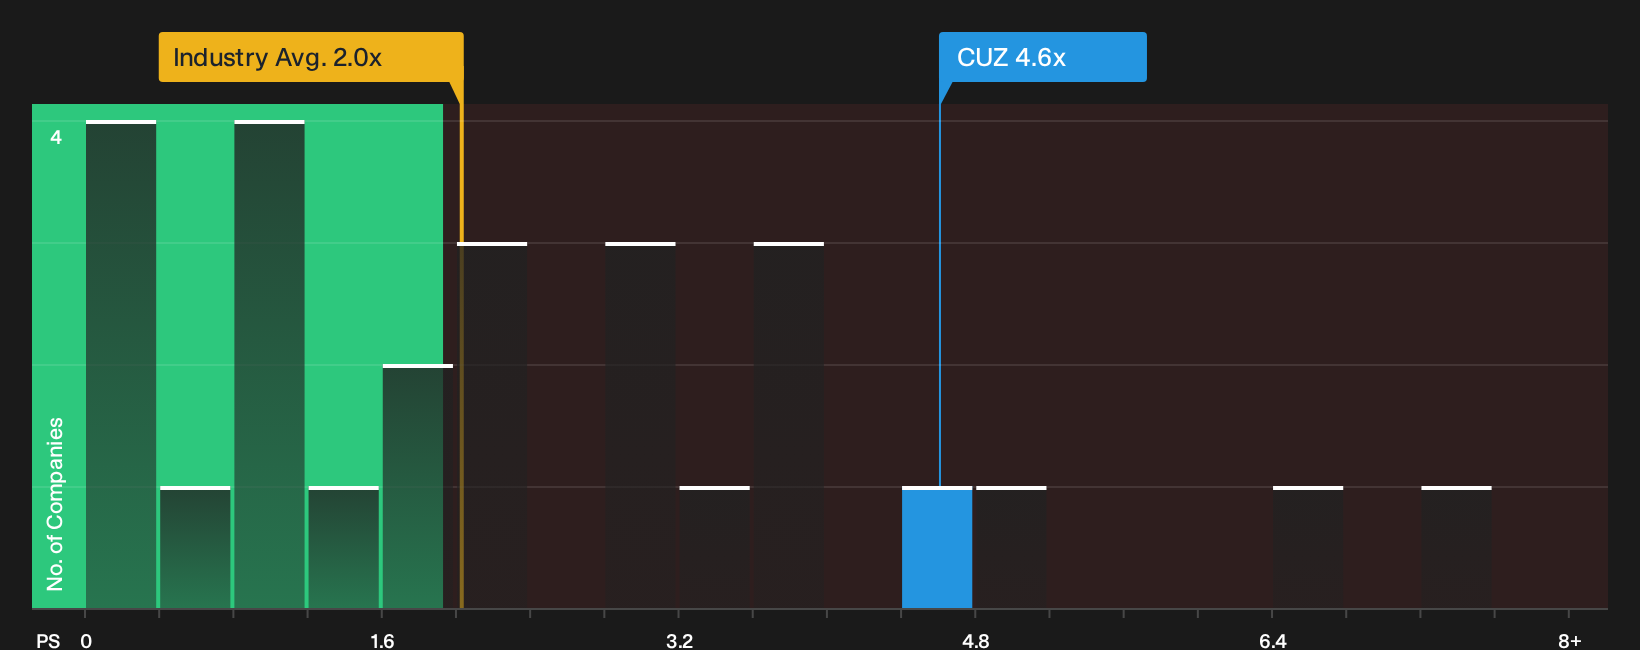
The first story around Cousins Properties leans heavily on fair value estimates tied to future cash flows and analyst forecasts. A different lens looks at today’s price tag. On a P/S multiple of 4.6x versus 2x for the US Office REITs group and 4x for peers, the stock screens expensive even though the fair ratio sits at 5x. That mix suggests more room for debate than clear consensus. Which yardstick do you trust when numbers pull in opposite directions?
For a closer look at how that price tag lines up against sales, margins and peer valuations, take a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Cousins Properties so far. Act while the data is fresh, weigh the upside against the concerns, and ground your view in the underlying 2 key rewards and 4 important warning signs.
Looking for more Cousins Properties style investment ideas?
Do not stop your research with Cousins Properties. Use the Simply Wall Street Screener to surface fresh ideas that fit your risk, return, and income goals.
- Target dependable income and compare high-yield opportunities by scanning a curated 8 dividend fortresses that puts cash returns front and centre for your watchlist.
- Hunt for mispriced opportunities by lining up a focused 32 high quality undervalued stocks that filters for quality businesses trading below their assessed worth.
- Prioritise resilience by reviewing a tight 30 resilient stocks with low risk scores that concentrates on companies with sturdier balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com