
FuelCell Energy (FCEL) Following Lawsuits Faces A Fair Value Debate
The recent wave of federal securities class action lawsuits against FuelCell Energy (FCEL) has put the stock under closer scrutiny, with allegations centering on disclosures about manufacturing capacity, production rates, costs, and CEPA-related risks.
FuelCell Energy’s recent lawsuits arrive after a sharp swing in performance, with the share price at US$16.49 and a year to date share price return of 101.84%, a 90 day share price return that declined 54.21%, a 1 year total shareholder return of 111.95%, and a 3 year total shareholder return that fell 54.19%.
Compare how FuelCell Energy’s risk profile stacks up against peers by scanning 30 resilient stocks with low risk scores, which have already cleared stricter balance sheet and volatility checks.
After a steep rise in FuelCell Energy followed by a sharp pullback and fresh legal risk on the table, the real puzzle is whether you lean into the volatility now or wait for a calmer entry as valuation comes into focus.
Most Popular Narrative: 20% Undervalued
FuelCell Energy’s most followed valuation story pegs fair value at $20.50, compared with the recent close at $16.49. This puts the legal overhang and sharp swings against a model that leans heavily on future execution.
The analysts have a consensus price target of $20.5 for FuelCell Energy based on their expectations of its future earnings growth, profit margins and other risk factors.
In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $690.6 million, earnings will come to $77.6 million, and it would be trading on a PE ratio of 34.2x, assuming you use a discount rate of 9.8%.
See why 51 investors see FuelCell Energy as 20% undervalued.
Result: Fair Value of $20.50 (UNDERVALUED)
Still, the FuelCell Energy story leans heavily on future execution, so continued losses and any stumbles on big data center or Fit Energy projects could quickly shake this narrative.
Find out about the key risks to this FuelCell Energy narrative.
Another View: FuelCell Energy Looks Expensive On Sales
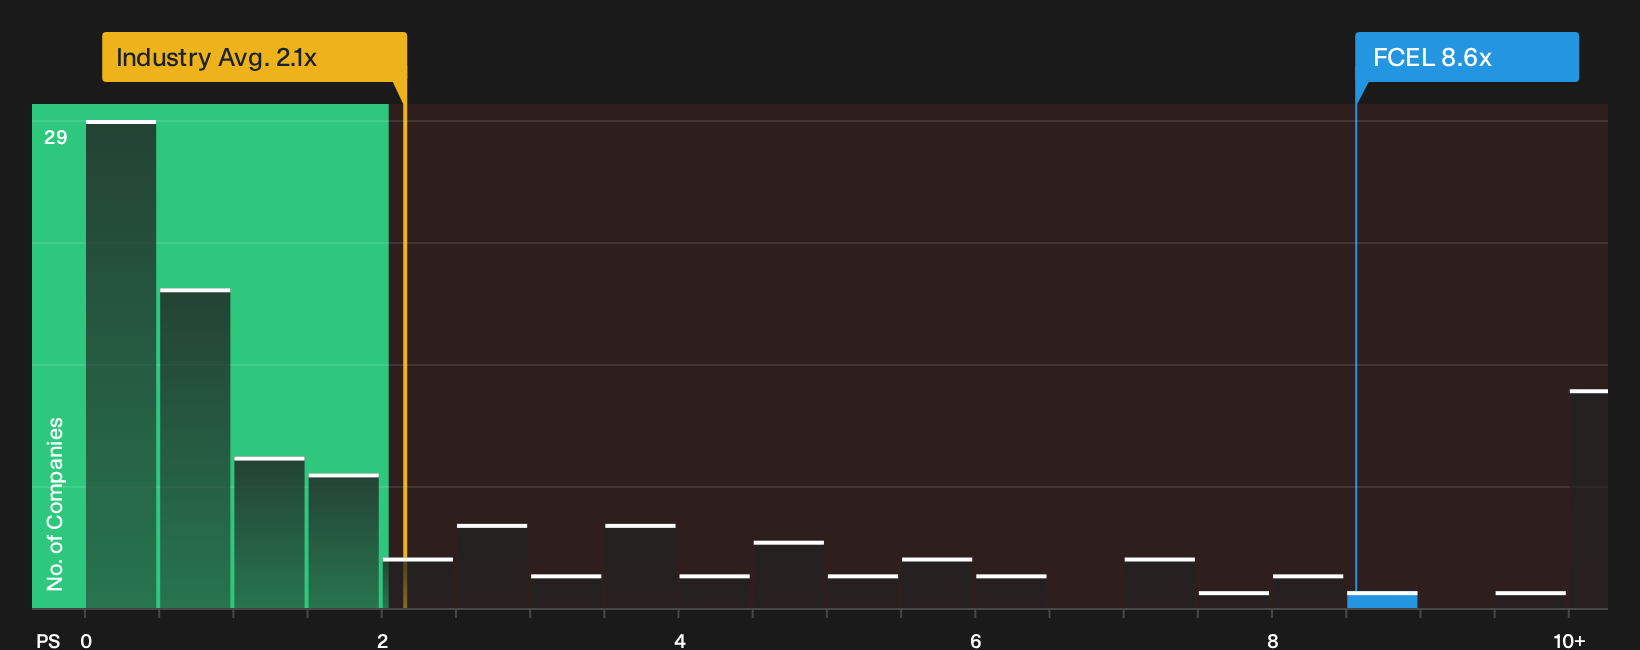
The fair value story for FuelCell Energy sits at $20.50, yet the share price already reflects a relatively high sales multiple. The stock trades at a P/S ratio of 8.6x, compared with 2.1x for the wider US Electrical group and a fair ratio estimate of 1.6x. This suggests there is far less margin for error if growth or execution weaken.
To see how much of this premium comes from the current sales multiple rather than cash flow expectations, take a closer look at our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings on FuelCell Energy after recent volatility and legal developments. Act while the data is current and pressure test the thesis yourself by weighing the 1 key reward and 3 important warning signs.
Looking for more FuelCell Energy style investment ideas?
If FuelCell Energy has you rethinking your next move, use this moment to widen your watchlist with fresh ideas that match your risk and return preferences.
- Target potential mispricing opportunities by scanning the 32 high quality undervalued stocks that combine quality fundamentals with compressed expectations.
- Strengthen the income side of your portfolio by reviewing the 8 dividend fortresses that focus on higher yields backed by resilient businesses.
- Protect against nasty surprises by screening the list of solid balance sheet and fundamentals (24 results) that already pass stricter debt and liquidity checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com