
Toho Bank (TSE:8346) Raised Earnings And Dividend Guidance, Has The Upside Already Been Priced In?
Toho Bank (TSE:8346) has put income and guidance in the spotlight after raising both its dividend outlook and profit forecasts, tying the move to higher expected interest income on loans and securities.
Theho Bank’s guidance update lands after a powerful run in the shares, with the 1-day share price return of 8.51% capping a 90-day share price return of 41.91% and a year-to-date share price return of 100.18%. This has gone hand in hand with very strong 1-year and multi year total shareholder returns, pointing to momentum that has been building rather than fading as investors reassess both earnings power and perceived risk around the story.
Scan how Toho Bank's guidance upgrade compares with a curated group of banks and financials that also screen well for balance sheet strength in our list of solid balance sheet and fundamentals (22 results)
After a move this quick in Toho Bank, the gap between the current ¥1,097 share price and the range of value estimates matters far more than the headline rally. Where does fair value really sit now?
Preferred P/E of 19.4x: Is it justified?
On valuation, Toho Bank now trades on a P/E of 19.4x, which puts a clear premium on the current ¥1,097 share price compared with both peer and broader Japanese bank averages.
The P/E ratio compares the market price of the stock with its earnings per share. For a lender like Toho Bank, that figure often reflects how investors weigh the durability of profits, the quality of the loan book, and the perceived risk around interest income.
Income trends offer some context. Earnings growth over the past year was 70.5%, which is faster than the business's 5 year average growth rate of 36.2% per year, and current net profit margins of 17.5% are higher than 12.5% last year. Those figures sit alongside an assessment of high quality earnings, yet they are paired with a low 6.3% Return on Equity, which suggests the premium multiple leans heavily on earnings strength rather than efficiency of capital.
Peer comparison is blunt. The 19.4x P/E is higher than the immediate peer average of 17.4x and also above the JP Banks industry average of 16x. That double premium signals the market is paying up for Toho Bank relative to both its direct group and the wider sector.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 19.4x (OVERVALUED)
DCF fair value gap for Toho Bank looks wide
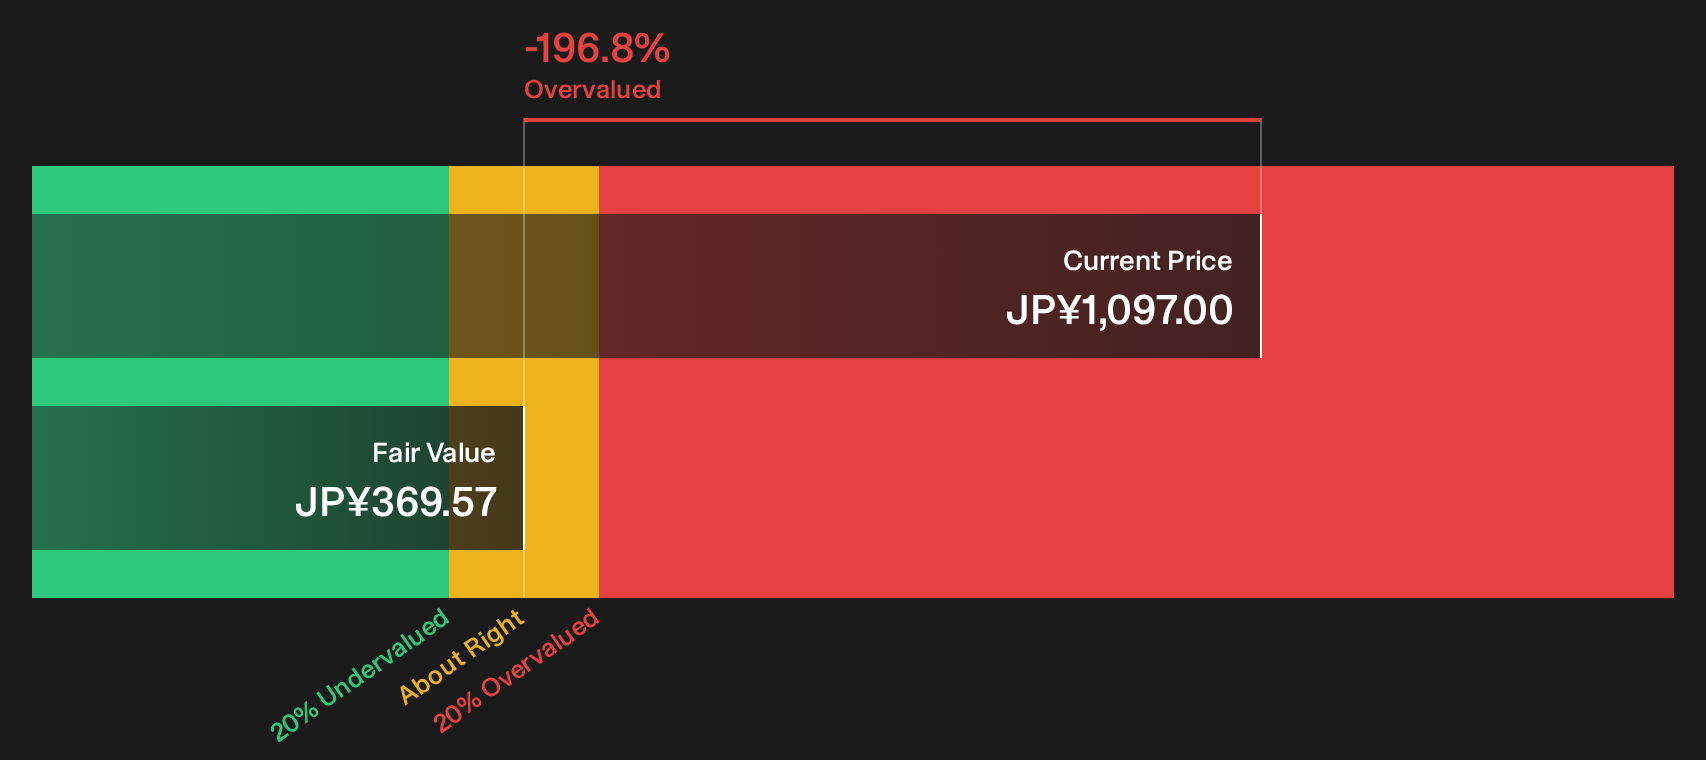
Using the SWS DCF model as a cross check, Toho Bank at ¥1,097 trades well above an estimated future cash flow value of ¥369.57, which implies the market price is roughly three times the model's fair value estimate.
The SWS DCF model projects future cash flows for the business and then discounts them back to today using a required rate of return. That process aims to put a single figure on what the projected stream of cash is worth now in ¥ terms, based purely on those projected flows rather than earnings multiples.
For a regional lender with a diversified banking, leasing, and credit guarantee mix, the DCF output can be sensitive to assumptions about interest income, credit costs, and loan growth. High recent earnings growth of 70.5% and improving margins sit next to a low allowance for bad loans at 44%, which may influence how conservative investors want future cash flows to be in their own work compared with this single model output.
Look into how the SWS DCF model arrives at its fair value.
Result: DCF Fair value of ¥369.57 (OVERVALUED)
Still, a sustained gap between Toho Bank's P/E and peers, combined with a DCF value far below the ¥1,097 price, leaves sentiment vulnerable to disappointment.
Find out about the key risks to this Toho Bank narrative.
Another view on Toho Bank’s valuation
The earlier P/E premium paints Toho Bank as expensive, yet the SWS DCF model goes further. At ¥1,097 the shares sit well above an estimated future cash flow value of ¥369.57, which screens as overvalued on this second method too. If both lenses are flashing rich, what is the market really pricing in?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Toho Bank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Toho Bank's valuation story are hard to ignore. If you want to move fast and decide where you stand, start by weighing the 1 key reward and 2 important warning signs flagged in our summary of the fundamentals and market risks through the 1 key reward and 2 important warning signs.
Looking for more Toho Bank sized investment ideas?
Do not stop with Toho Bank. Use the Simply Wall Street Screener to look for additional opportunities before prices move away.
- Target quality at a discount by scanning a curated pool of companies that screen well on valuation and fundamentals through the 19 high quality undervalued stocks.
- Focus on potential income streams by looking at companies with resilient dividend payments using the 15 dividend fortresses.
- Emphasise capital preservation by filtering for businesses with relatively lower risk profiles in the 21 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com