
UK Housing Policy Changes Put Grainger Stock And Homebuilders In Focus
Housing policy in the UK is shifting again, and the new “Your First Home” scheme, richer savings products and talk of ultra-high LTV mortgages are quietly rewiring the risk and reward profile across residential finance. These changes could reshape where capital flows next, which means missed homework today may feel costly later. This article unpacks three UK stocks exposed to the news and how these shifts might matter for your portfolio.
The three stocks covered next are only a sample from the wider opportunity set, and the full screen surfaced 7 more listed UK residential finance and homebuilding companies with equally compelling narratives that are not discussed in this article.
To go straight to the source and filter, analyze and identify your own highest conviction angles, head into the UK Residential Housing Finance & Homebuilders screener.
Grainger (LSE:GRI)
Overview: Grainger is a UK-based owner, developer and operator of rental homes, giving investors direct exposure to Britain’s housing market.
Operations: Grainger generates about £164 million from its Private Rented Sector portfolio, £74 million from reversionary assets and £2 million from other activities, all within the UK.
Market Cap: £1.2b
Grainger fits into the UK Residential Housing Finance & Homebuilders theme as a pure-play landlord in a housing system increasingly shaped by policy for first-time buyers. Rental income, asset values and dividend capacity all depend on how these schemes affect would-be buyers who keep renting for longer, particularly if there is any change in a key pressure point within its funding costs.
Those funding pressures are exactly why it helps to see the full Grainger financial health report before taking a view on how resilient Grainger really is.
Cairn Homes (LSE:CRN)
Overview: Cairn Homes is an Ireland-focused homebuilder creating large-scale housing developments, which links it to the UK Residential Housing Finance & Homebuilders theme through shared first-time buyer and mortgage trends.
Operations: Cairn Homes generates about €1.12 billion from building and property development activities in Ireland, its sole reported market.
Market Cap: £1.4b
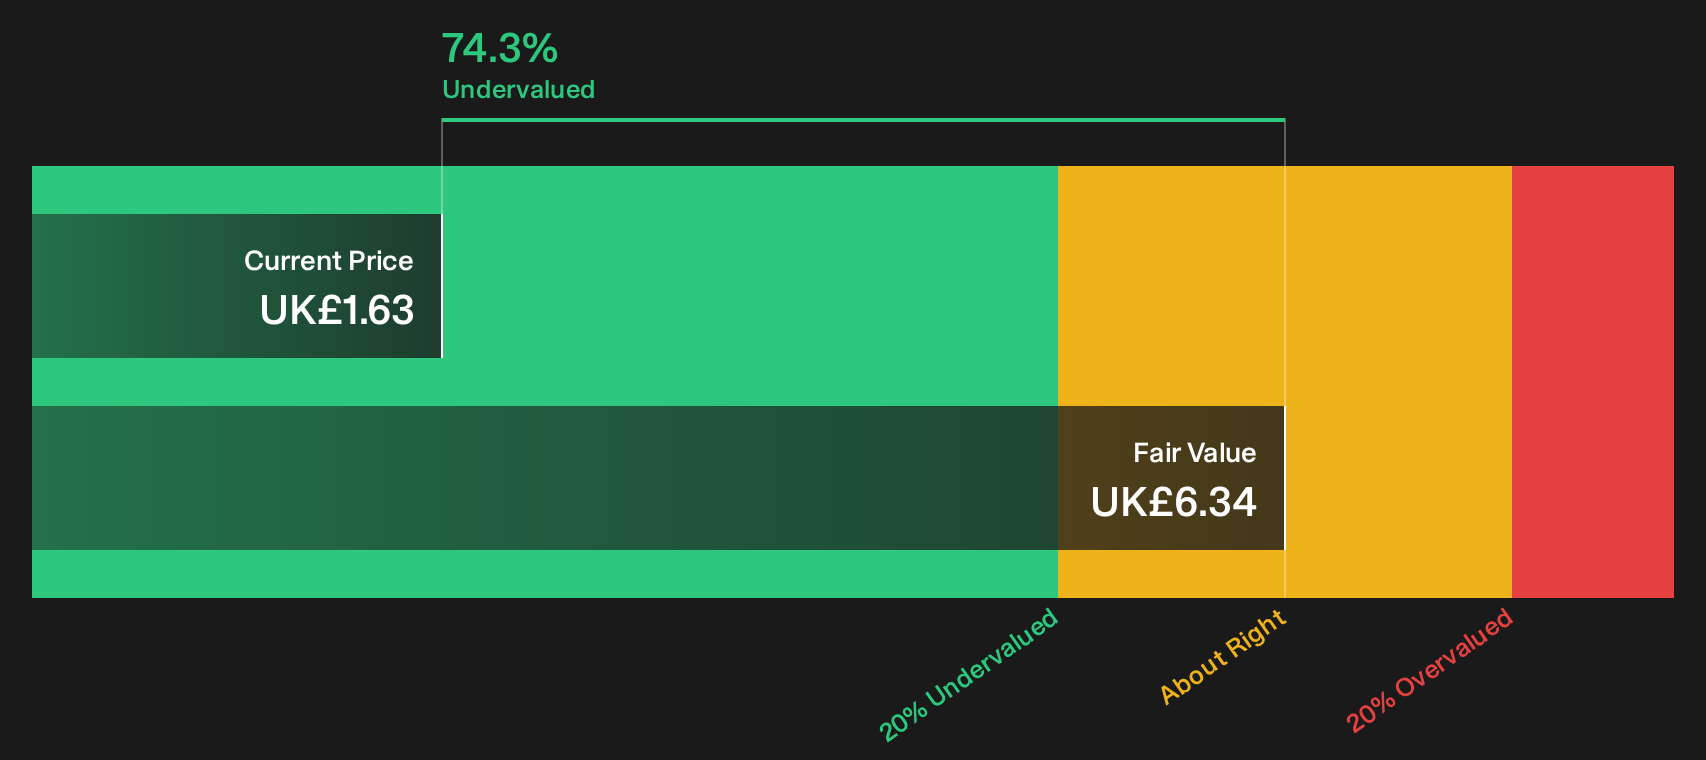
Where Grainger gives you rental exposure to UK housing policy, Cairn Homes offers pure new-build leverage to Ireland’s own mix of mortgage rules and buyer subsidies, which still rhyme with the forces shaping UK-focused lenders and builders.
"The ongoing acute housing shortage in Ireland, supported by robust population growth, urbanization, and high levels of first-time buyer demand, is allowing Cairn Homes to sustain high absorption and strong forward sales rates; this is reflected in a forward order book of €1.54 billion, which materially underpins near- and medium-term revenue growth."
What happens to Cairn Homes’ appeal if a single policy shift changes how easily those future buyers can actually fund their purchases?
If that funding puzzle is what you care about, read the full narrative for Cairn Homes to see how policy risk, pricing power and execution are really interacting.

Springfield Properties (AIM:SPR)
Overview: Springfield Properties is a UK housebuilder and land developer focused on new residential communities that directly tap first-time buyer demand.
Operations: Springfield Properties generates about £244 million from housing building activity in the United Kingdom, tying revenue closely to domestic new-build demand.
Market Cap: £138 million
Springfield Properties plugs straight into the UK Residential Housing Finance & Homebuilders theme because its new-build pipeline depends heavily on how easily first-time buyers and low-deposit borrowers can secure mortgages on its sites.
"The company executed profitable land sales of £28 million, above book values, demonstrating the ability to unlock value from its land bank efficiently."
What really moves the needle for Springfield Properties now is how one unresolved pressure on future buying power and pricing eventually plays out.
If that unresolved pressure is what you are weighing, the full narrative for Springfield Properties explains how Springfield Properties’ land bank, pricing and demand could be moving in different directions.

Seeking Fresh Alternatives Before Others?
Fresh ideas move first. Slow research often gets caught chasing momentum, while early movers ride quiet breakouts under the radar for now. Scan what is moving and act now.
- Spot strong income engines before yields get crowded by using the 1 dividend fortresses and see which payouts still look supported while it matters.
- Track real-world infrastructure behind the AI surge through the 85 AI infrastructure stocks and see where capital expenditure and data demand could already be building momentum.
- Hunt for early energy transitions with the 19 nuclear energy infrastructure stocks and check which infrastructure operators are still flying under the crowd’s attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com