
Top Japanese Value Stocks In September 2026
The Bank of Japan has just lifted interest rates to a 31 year high, which has sharpened the focus on cash generation and balance sheet resilience for Japanese companies. Higher borrowing costs can expose which businesses really produce dependable cash. That creates an opening for investors hunting Tokyo listed stocks where cash flows look strong relative to the current share price. This article walks through three such opportunities from our cash flow based value screen.
The three stocks highlighted below are only a first cut from this cash flow value idea. The full screen surfaced 39 more companies with similarly compelling cash generation stories that are not covered here. To identify and analyze the highest conviction setups straight away, head into the Undervalued Stocks Based On Cash Flows screener.
Canon (TSE:7751)
Overview: Canon develops and sells office printers, document solutions, cameras, medical imaging systems and industrial equipment that together generate sizeable global cash flows.
Market Cap: ¥3.9t
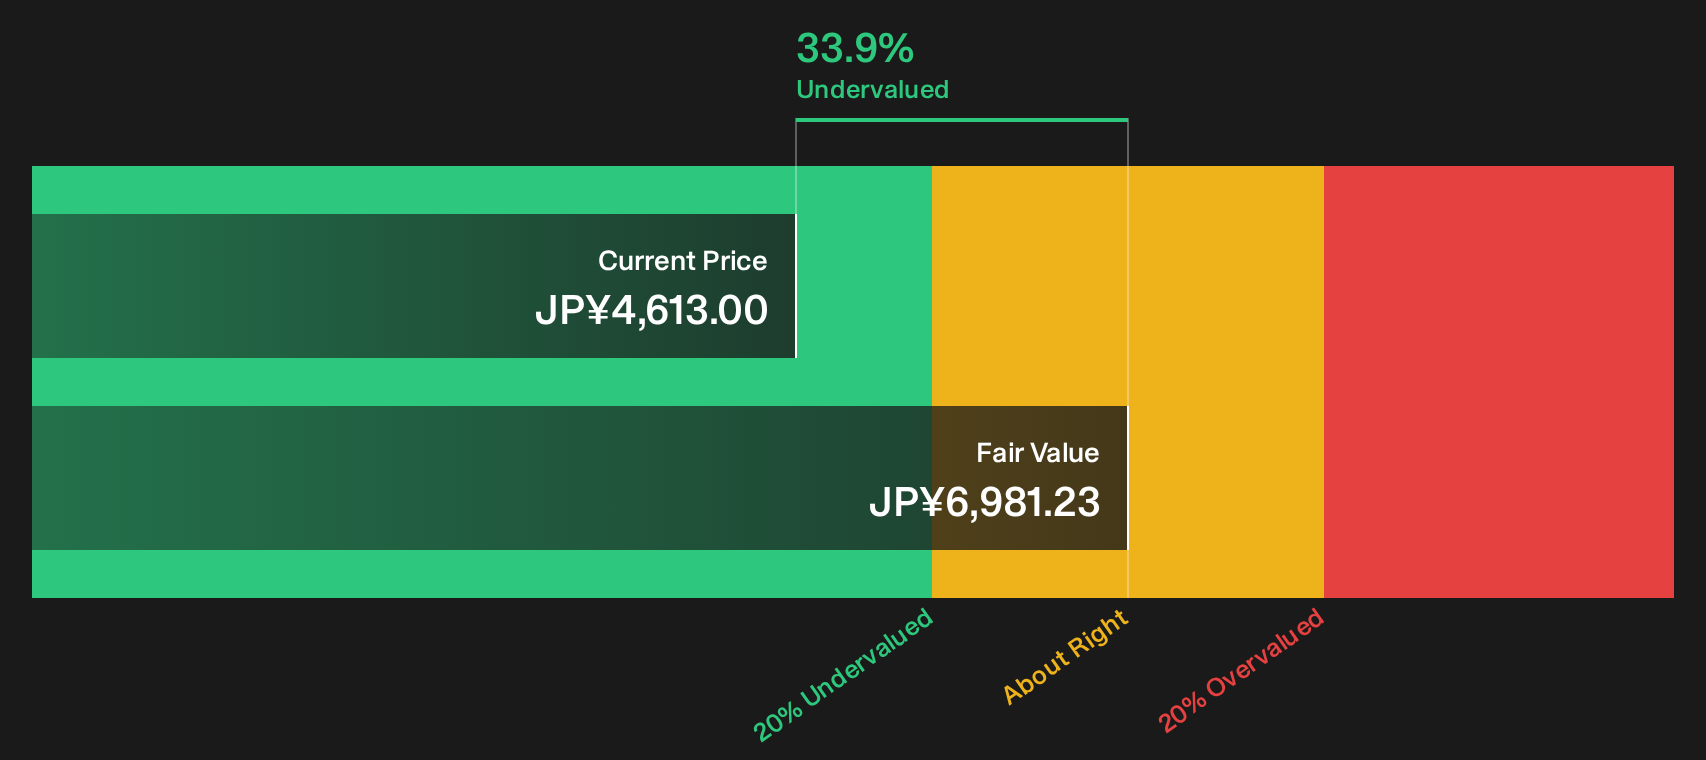
Canon fits the cash flow screen because its office printing and document solutions arm produces steady earnings that can be valued through a DCF model. The shares are quoted about 33.9% below that estimated fair value, with margins around 7.4% and earnings up about 109.1% year over year, depending on how one unseen pressure influences that cash conversion story.
That kind of earnings surge can mask as much as it reveals, so it is worth reading the 4 key rewards and 1 important warning sign to see what might be driving or capping Canon's cash engine.
Astellas Pharma (TSE:4503)
Overview: Astellas Pharma develops and sells prescription medicines worldwide, with a particularly strong oncology portfolio that supports its cash flow profile.
Operations: The group generates about ¥2.3t in pharmaceutical revenue, with sizeable contributions from the USA at roughly ¥1.0t and Japan at about ¥328b.
Market Cap: ¥4.3t
Astellas Pharma is relevant for this cash flow screen because its oncology therapies already generate recurring cash, while the pipeline and pricing environment continue to develop.
"Patent expirations for key drugs such as XTANDI and mirabegron may lead to revenue and earnings pressure if generic entrants reduce Astellas' market share in critical therapeutic areas in the coming years."
Investor outcomes will depend on how this ongoing pressure affects the balance between potential pricing power and cash generation.
That pressure point is exactly where the story gets interesting, and the full narrative for Astellas Pharma shows how Astellas Pharma could turn expiring patents into an accelerating reset.

Terumo (TSE:4543)
Overview: Terumo manufactures cardiac and vascular devices, hospital equipment, and blood and cell technologies that support recurring, procedure-driven cash flows worldwide.
Operations: Cardiac and Vascular contributes about ¥706.7b of annual revenue, with Medical Care Solutions and Blood and Cell Technologies adding roughly ¥222.3b and ¥240.2b.
Market Cap: ¥3.4t
Terumo matters for a cash flow focused investor because its Cardiac and Vascular products help turn everyday hospital procedures into repeat, high margin revenue streams that can underpin a discounted cash flow valuation when the market is fixated on shorter term headlines.
"Expansion of sales channels and volume commitments in China, especially in Neurovascular products, has enabled Terumo to gain market share and increase prices, counteracting typical negative VBP effects and positioning the company for future revenue growth in this key emerging market."
Much of the long term payoff will hinge on how one unresolved pressure shapes the balance between pricing power and profitability.
If that pressure point is what interests you, the full narrative for Terumo shows how Terumo's China exposure, pricing power and cash engine could be quietly accelerating.

Curious About What You Might Be Missing?
Fresh ideas move first. By the time momentum is obvious, the best entry points can already be flying. Scan under the radar for now, and consider acting before the crowd.
- Spot potential cash machines hiding behind slow headlines and sort through the list of solid balance sheet and fundamentals (22 results) before the crowd starts chasing the same resilient stories.
- Follow early breakout trends in automation by tracking companies inside the 92 robotics and automation stocks while capital is still rotating quietly into these operators.
- Review companies in the 40 power grid technology and infrastructure stocks while valuations can still reflect yesterday's narrative, not tomorrow's demand.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com