
Top Asian Growth Companies With Insider Ownership September 2026
As the Asian markets navigate through a period marked by global economic shifts and technological advancements, investors are increasingly focusing on growth stocks with strong insider ownership. In this context, companies that demonstrate robust growth potential while maintaining significant insider stakes can offer unique insights into confidence levels and alignment of interests between management and shareholders.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 119.7% |
| Meitu (SEHK:1357) | 23% | 26.9% |
| Meiko Electronics (TSE:6787) | 19.2% | 33.8% |
| L&C BIOLTD (KOSDAQ:A290650) | 20.9% | 163% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| HUMAN MADE (TSE:456A) | 23.9% | 29.8% |
| Fulin Precision (SZSE:300432) | 11.2% | 66.5% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's explore several standout options from the results in the screener.
TLB (KOSDAQ:A356860)
Simply Wall St Growth Rating: ★★★★★★
Overview: TLB Co., Ltd. manufactures and sells printed circuit boards (PCBs) across South Korea, China, the rest of Asia, and the United States, with a market cap of ₩867.26 billion.
Operations: The company's revenue from manufacturing and selling printed circuit boards amounts to ₩305.53 billion.
Insider Ownership: 27.9%
TLB Co., Ltd's strong growth prospects are underscored by its forecasted revenue and earnings growth, both significantly outpacing the KR market. Despite high volatility in share price, TLB is trading well below estimated fair value. Recent strategic moves include a substantial share repurchase program aimed at stabilizing prices and enhancing shareholder value. However, concerns about financial positioning due to insufficient operating cash flow coverage of debt remain pertinent for potential investors.
- Navigate through the intricacies of TLB with our comprehensive analyst estimates report here.
- Insights from our recent valuation report point to the potential undervaluation of TLB shares in the market.

Chengdu KSW TechnologiesLtd (SHSE:688283)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Chengdu KSW Technologies Co., Ltd. focuses on the research, development, manufacture, and sale of wireless channel simulators and radio frequency microwave signal generators in China, with a market cap of CN¥4.12 billion.
Operations: The company's revenue primarily comes from its Instruments and Meters Manufacturing segment, which generated CN¥238.23 million.
Insider Ownership: 36.8%
Chengdu KSW Technologies Ltd. is positioned for robust growth with earnings forecasted to grow 28.58% annually, surpassing the broader Chinese market's expectations. Despite recent declines in sales and net income, its revenue growth projection of 25.6% per year remains strong, outpacing the market significantly. The company's inclusion in the S&P Global BMI Index highlights its increasing prominence, although its low return on equity forecast (8.3%) may concern some investors seeking higher returns.
- Take a closer look at Chengdu KSW TechnologiesLtd's potential here in our earnings growth report.
- The valuation report we've compiled suggests that Chengdu KSW TechnologiesLtd's current price could be inflated.
Union Tool (TSE:6278)
Simply Wall St Growth Rating: ★★★★★☆
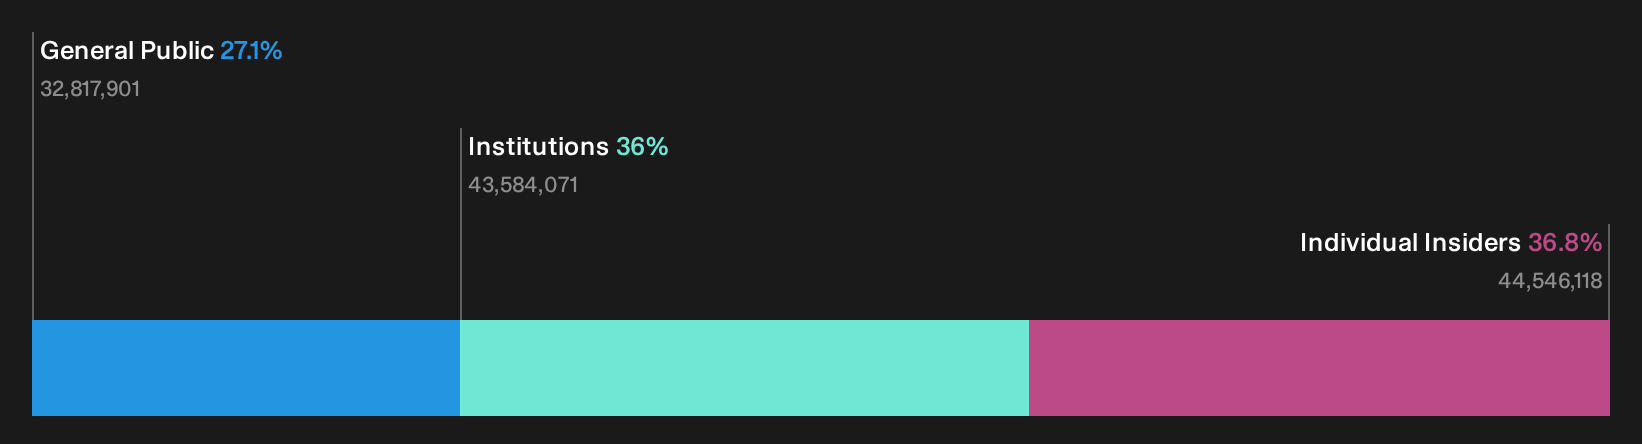
Overview: Union Tool Co. designs, manufactures, and sells cutting tools, linear motion products, and metal machining equipment in Japan, China, Taiwan, and internationally with a market cap of ¥279 billion.
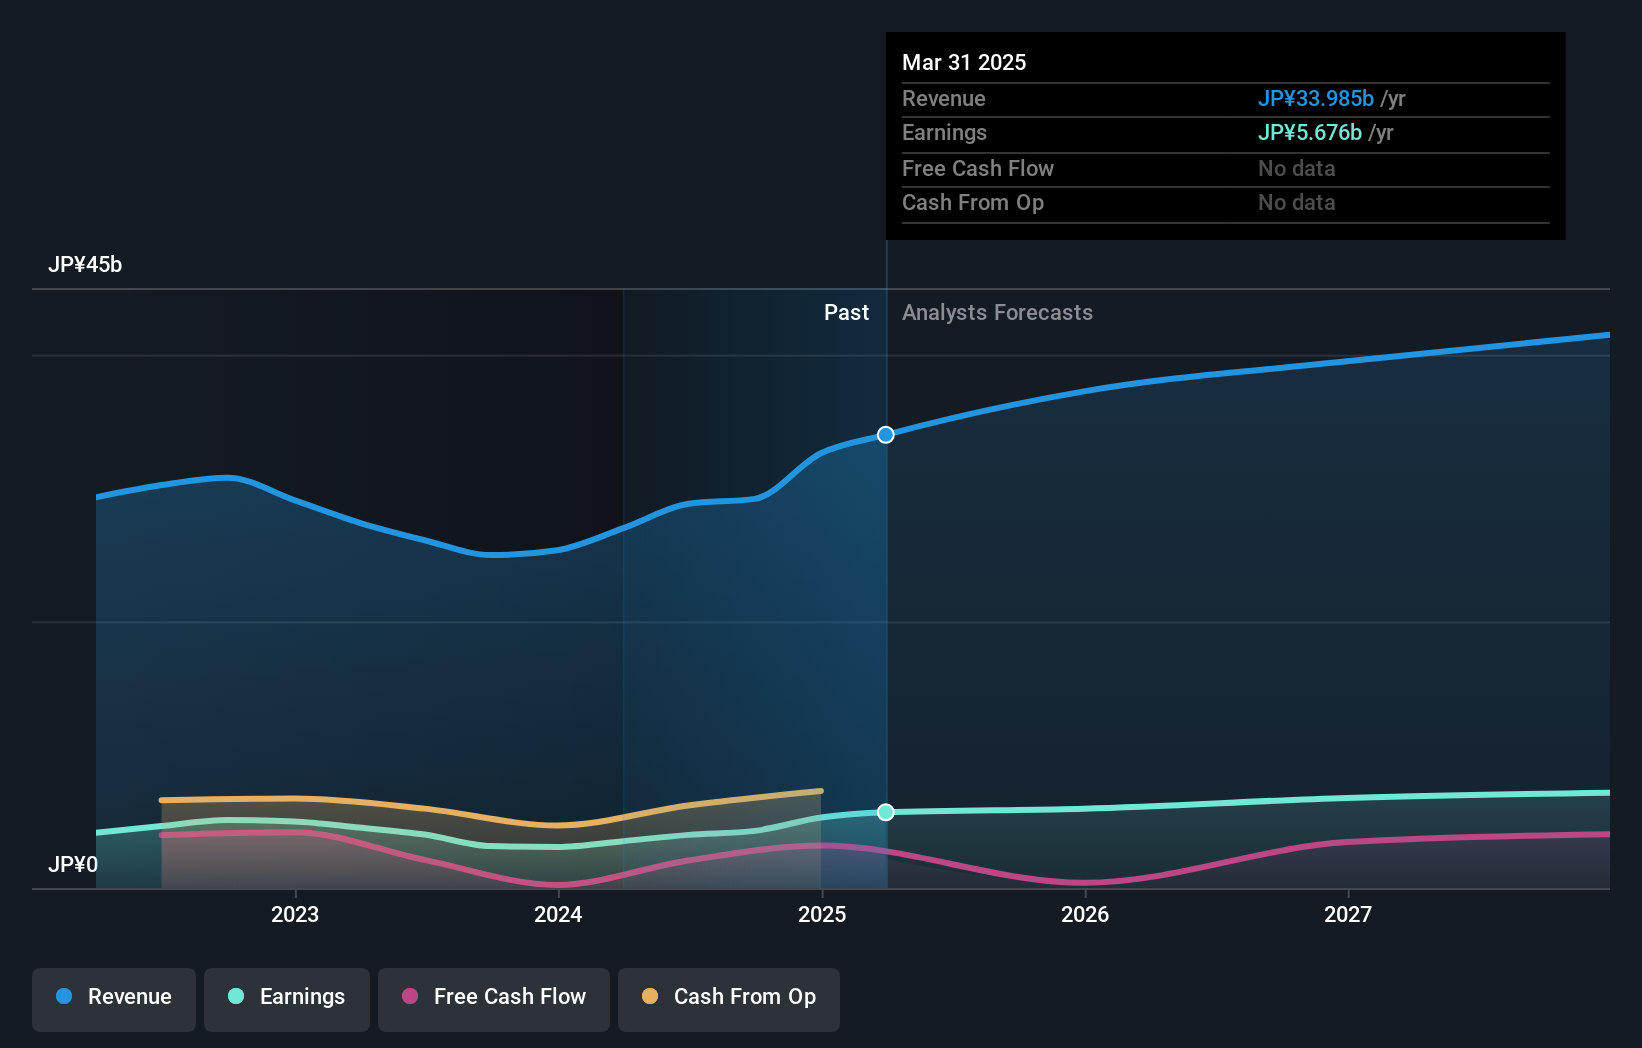
Operations: The company's revenue segments are ¥31.09 billion from Asia, ¥30.97 billion from Japan, ¥2.74 billion from Europe, and ¥2.41 billion from North America.
Insider Ownership: 34.6%
Union Tool is poised for significant growth with earnings expected to rise 27.5% annually, outpacing the Japanese market. Revenue is forecasted to grow at 23.4% per year, well above the market's 6.5%. Despite recent share price volatility, the company trades at a substantial discount to its estimated fair value. Recent revisions in earnings guidance and increased dividends reflect strong financial performance and commitment to shareholder returns amidst a stable insider ownership structure.
- Get an in-depth perspective on Union Tool's performance by reading our analyst estimates report here.
- The analysis detailed in our Union Tool valuation report hints at an deflated share price compared to its estimated value.
Taking Advantage
- Get an in-depth perspective on all 488 Fast Growing Asian Companies With High Insider Ownership by using our screener here.
- Curious About Other Options? AI is about to change healthcare. These 135 stocks are working on everything from early diagnostics to drug discovery. The best part - they are all under $10b in market cap - there's still time to get in early.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com