
Undiscovered Asian Gems with Strong Potential In September 2026
In September 2026, the Asian markets have shown resilience amid global economic shifts, with small-cap indices experiencing fluctuations due to inflation concerns and rising interest rates. Despite these challenges, the search for promising investments continues as investors look for stocks that demonstrate strong fundamentals and potential growth in this dynamic region.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Yahagi ConstructionLtd | 19.18% | 12.68% | 22.27% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Chengtun Mining Group | 99.24% | -6.93% | 33.44% | ★★★☆☆☆ |
| Primo Global Holdings | 70.93% | 9.87% | 28.79% | ★★★☆☆☆ |
Here's a peek at a few of the choices from the screener.
PC Partner Group (SGX:PCT)
Simply Wall St Value Rating: ★★★★★★
Overview: PC Partner Group Limited is an investment holding company that designs, develops, manufactures, and sells computer electronics with a market capitalization of SGD1.23 billion.
Operations: PC Partner Group generates revenue primarily through the design, manufacturing, and trading of electronics and PC parts and accessories, amounting to HK$14.05 billion.
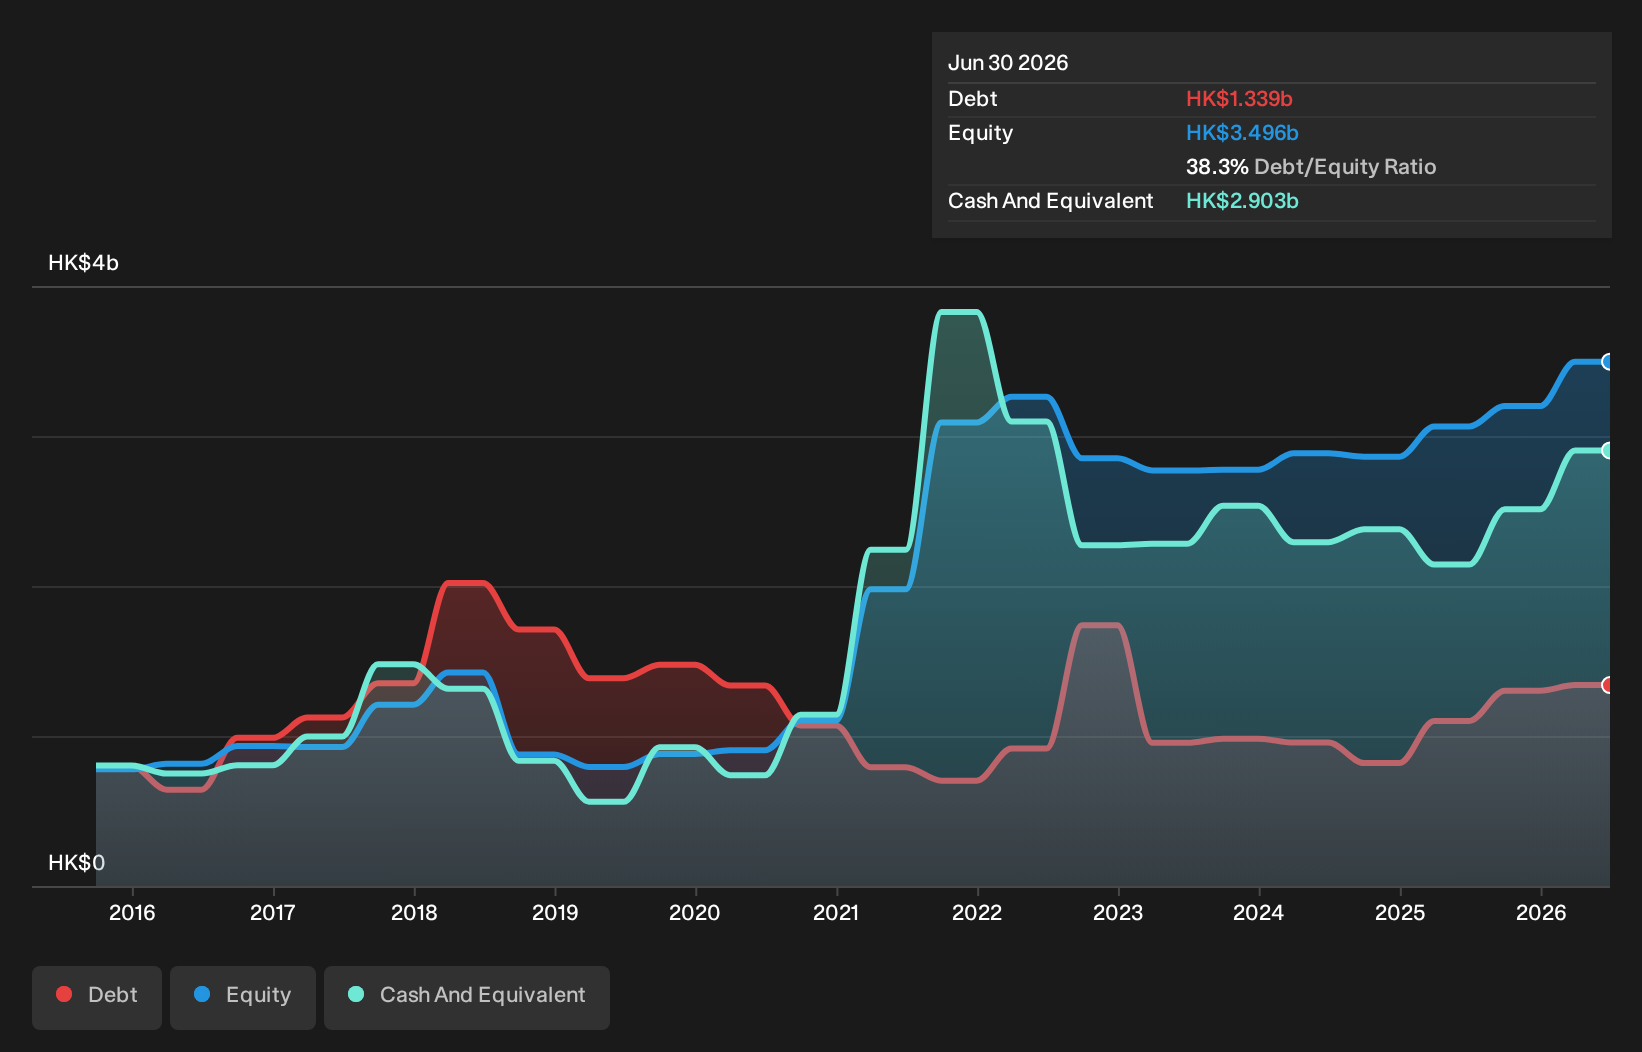
PC Partner Group, a tech player with a knack for high-quality earnings, has made waves by being added to the S&P Global BMI Index. The company reported impressive earnings growth of 147.9% over the past year, outpacing the tech industry's 36.5%. Its net income for the first half of 2026 hit HK$545.52 million, up from HK$250.36 million in 2025, reflecting an increase in branded product prices and improved gross profit margins. Trading at an attractive value—67.7% below estimated fair value—PCT's debt-to-equity ratio has decreased slightly over five years to 38.3%, indicating prudent financial management amidst volatility concerns.
- Click here to discover the nuances of PC Partner Group with our detailed analytical health report.
Evaluate PC Partner Group's historical performance by accessing our past performance report.
Smartsens Technology (Shanghai) (SHSE:688213)
Simply Wall St Value Rating: ★★★★★☆
Overview: Smartsens Technology (Shanghai) Co., Ltd. is a company that specializes in the design and manufacturing of semiconductor integrated circuit chips, with a market cap of CN¥37.53 billion.
Operations: Smartsens generates revenue primarily from semiconductor integrated circuit chips, amounting to CN¥9.84 billion.
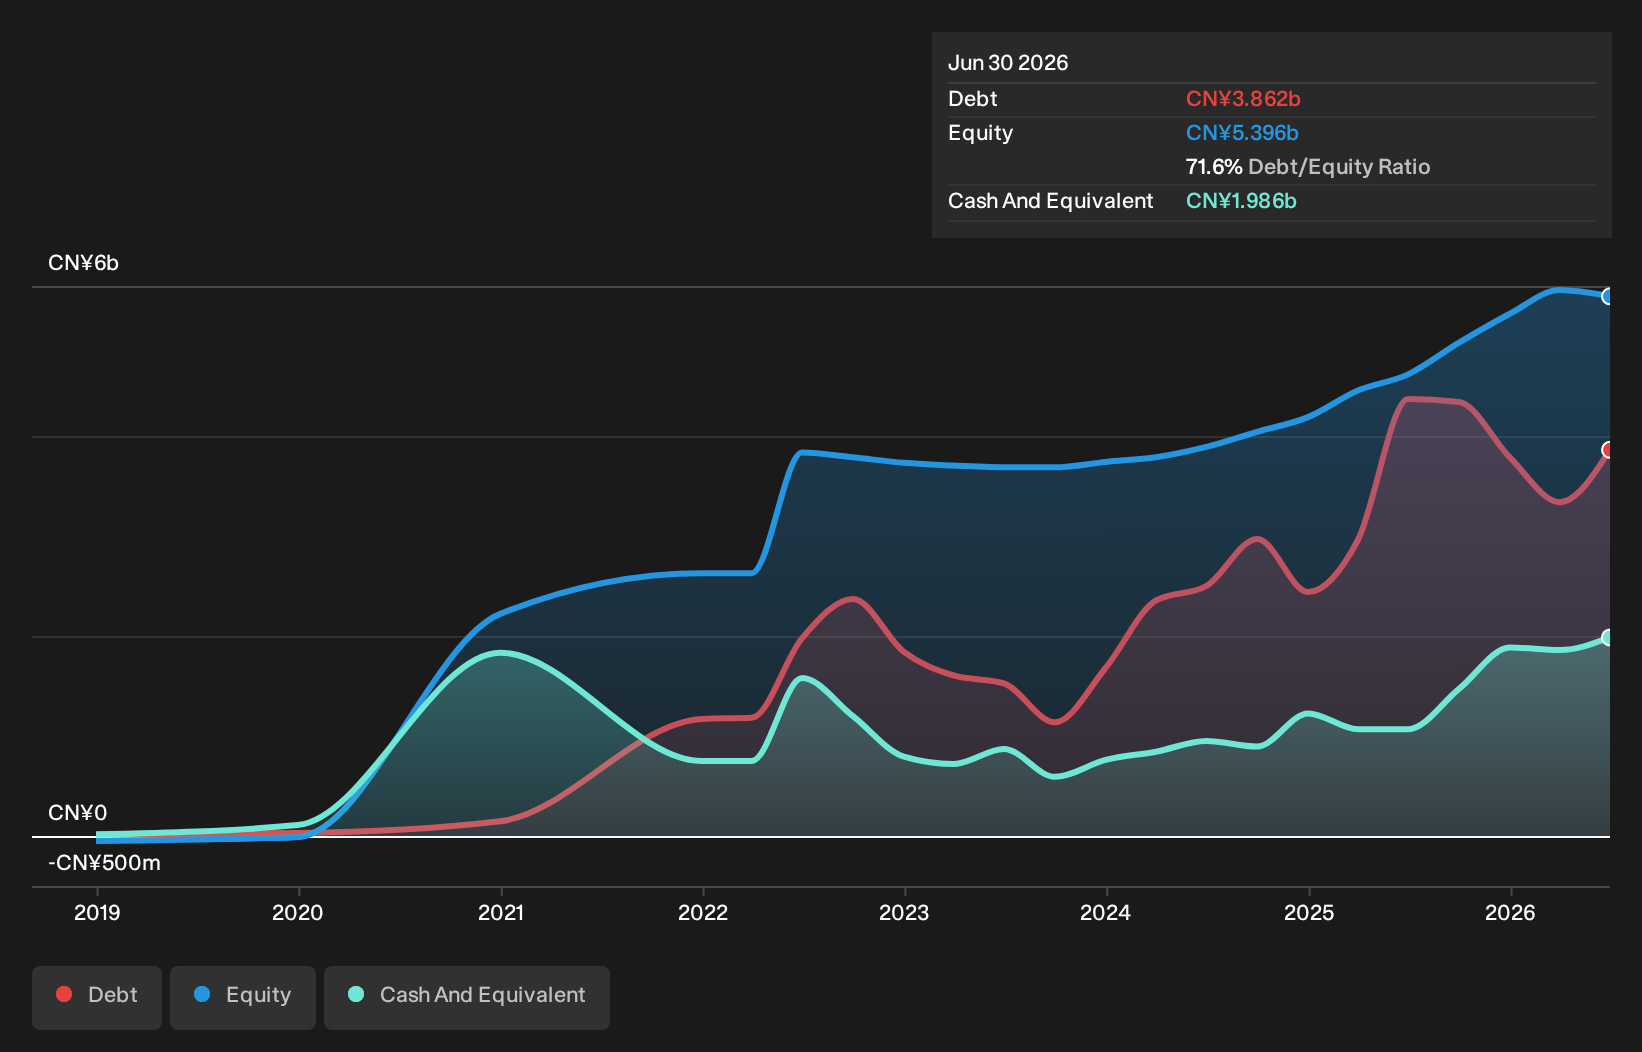
Smartsens Technology, a nimble player in the semiconductor industry, has shown promising growth with earnings surging 77.1% over the past year, outpacing the industry's 20.6% rise. The company's recent half-year sales reached CNY 4.60 billion from CNY 3.79 billion last year, while net income climbed to CNY 528 million from CNY 397 million. Despite a debt-to-equity ratio increase from 27.3% to 71.6% over five years, interest payments remain well-covered at a robust EBIT coverage of 19.5 times, suggesting financial stability amid expansion efforts and positioning it attractively below its estimated fair value by nearly half (55%).
- Click to explore a detailed breakdown of our findings in Smartsens Technology (Shanghai)'s health report.
Understand Smartsens Technology (Shanghai)'s track record by examining our Past report.
Guizhou Chanhen Chemical (SZSE:002895)
Simply Wall St Value Rating: ★★★★★☆
Overview: Guizhou Chanhen Chemical Corporation is involved in the mining and beneficiation of phosphate and the processing of phosphorus in China, with a market cap of CN¥18.28 billion.
Operations: The company generates revenue primarily through its operations in mining and beneficiation of phosphate, as well as processing phosphorus. It reported a gross profit margin of 25.3% for the latest period.
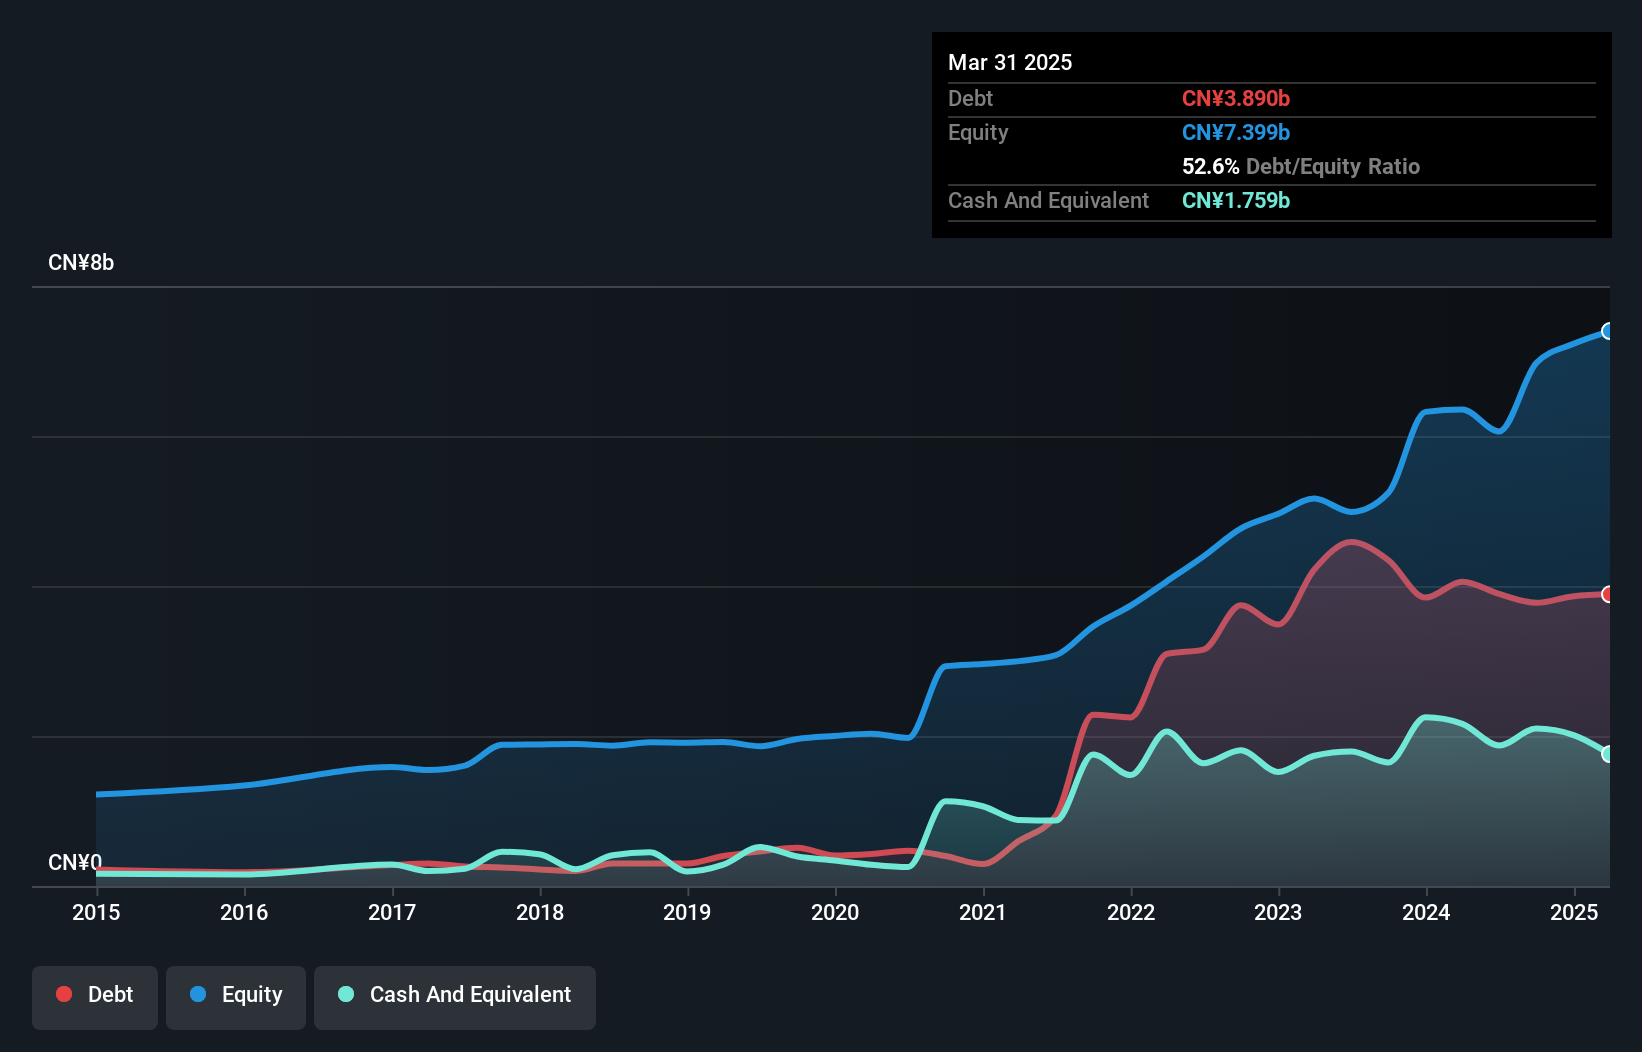
Guizhou Chanhen Chemical, a noteworthy player in the chemical sector, showcases robust financial health with its interest payments on debt well covered by EBIT at 264.7x. The company's earnings growth of 12.8% over the past year surpasses the industry average of 3.5%, reflecting strong operational performance. Trading at an impressive 70.9% below estimated fair value, it presents a compelling investment opportunity despite its increased debt to equity ratio from 30.4% to 39.2%. Recent half-year results highlight revenue growth from CNY 3,360 million to CNY 4,058 million and net income up slightly to CNY 560 million from CNY 536 million last year.
- Delve into the full analysis health report here for a deeper understanding of Guizhou Chanhen Chemical.
Gain insights into Guizhou Chanhen Chemical's past trends and performance with our Past report.
Summing It All Up
- Click this link to deep-dive into the 113 companies within our Asian Undiscovered Gems With Strong Fundamentals screener.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com