
Is HomeCo Daily Needs REIT (ASX:HDN) Undervalued Following Its Latest Distribution?
HomeCo Daily Needs REIT (ASX:HDN) has declared an unfranked quarterly cash distribution of A$0.0215 per unit, with the ex date on 29 September and payment scheduled for 24 November 2026.
The confirmed A$0.0215 distribution lands at a time when HomeCo Daily Needs REIT’s share price has slipped to A$1.06, with the 90 day share price return down 18.46% and the 1 year total shareholder return declining 17.66%, even though the 3 year total shareholder return remains positive. This suggests that recent weakness has softened what had previously been a stronger run.
Scan beyond HomeCo Daily Needs REIT and compare this distribution story with other income-focused opportunities using our curated list of 3 dividend fortresses.
HomeCo Daily Needs REIT now trades below both analyst targets and some fair value estimates after this pullback. Is that a genuine margin of safety, or a warning that the market’s caution is justified?
Preferred P/E of 6.1x for HomeCo Daily Needs REIT: Is it justified?
On A$1.06, HomeCo Daily Needs REIT screens as good value on several counts, with a P/E of 6.1x that sits below both its peer group and some fair value estimates.
The P/E ratio compares the current unit price with earnings per unit and gives a quick sense of how much investors are paying for each dollar of profit. For a real estate investment trust such as HomeCo Daily Needs REIT, this lens sits alongside metrics like distribution yield and net asset backing. However, a low P/E can still signal that the market is pricing in muted profit expectations.
HDN is flagged as good value based on that 6.1x P/E relative to the peer average of 8.1x, and it trades even further below the Global Retail REITs industry average of 12.2x. The same ratio also sits below an estimated fair P/E of 10.5x, which points to a level that the market could potentially gravitate toward if sentiment and fundamentals align with that benchmark.
Explore the SWS fair ratio for HomeCo Daily Needs REIT.
Result: Price-to-earnings of 6.1x (UNDERVALUED)
Still, the recent 1 year total return decline and annual revenue contraction signal that softer demand or operational pressures could challenge the HomeCo Daily Needs REIT recovery story.
Find out about the key risks to this HomeCo Daily Needs REIT narrative.
Another view on HomeCo Daily Needs REIT
The SWS DCF model offers a second lens. On this framework, HomeCo Daily Needs REIT screens as modestly undervalued, with an estimated future cash flow value of A$1.13 per unit compared with the A$1.06 market price. That is a gap, but is it big enough to compensate for forecast earnings declines?
Look into how the SWS DCF model arrives at its fair value.
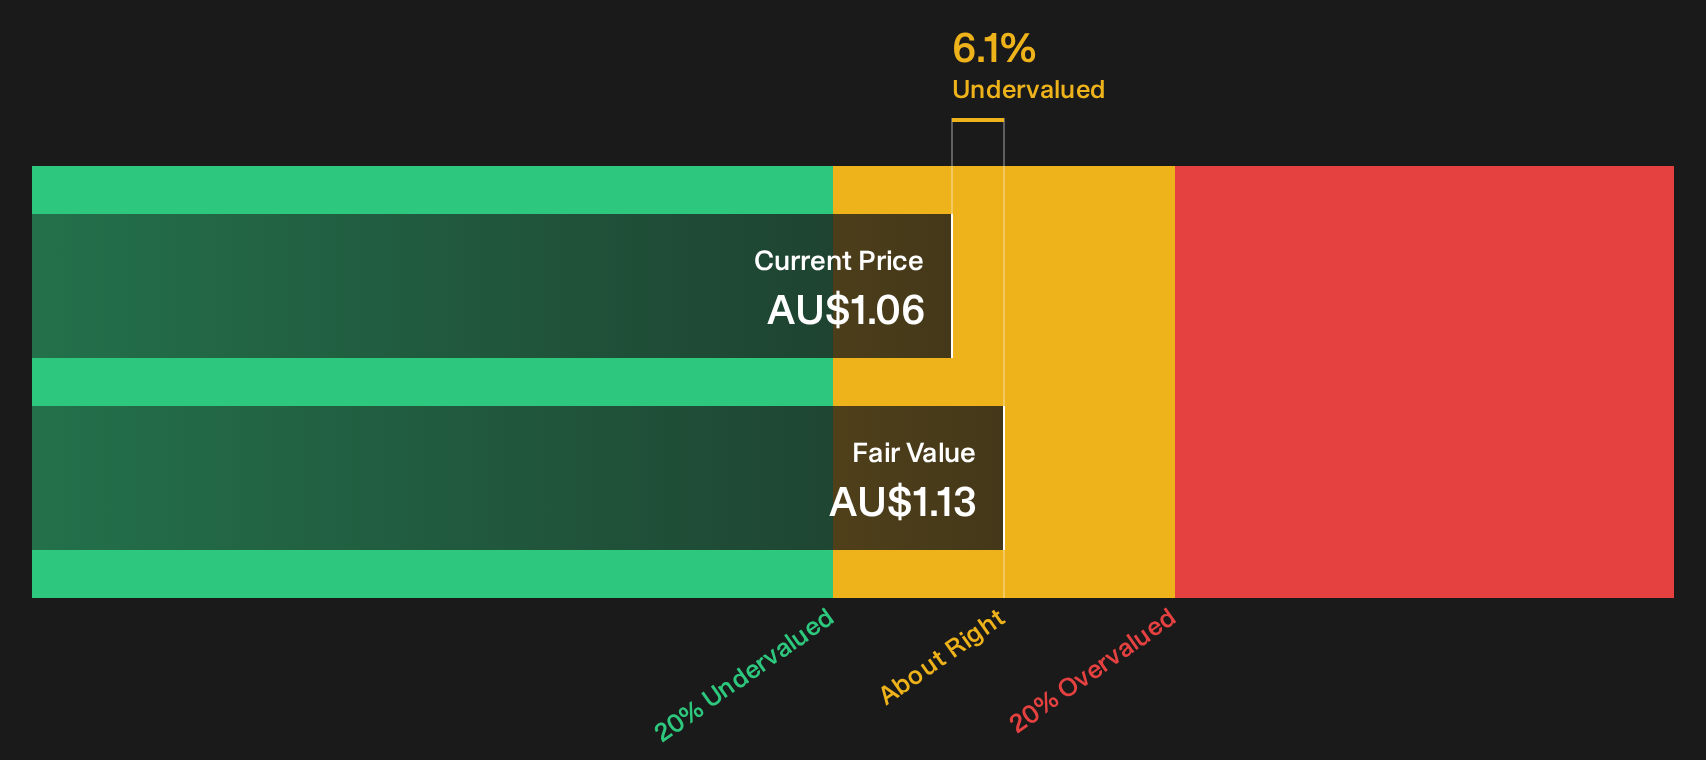
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out HomeCo Daily Needs REIT for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals on HomeCo Daily Needs REIT leave you on the fence, move quickly to test the data against your own expectations and risk appetite. Then weigh up the balance of risk and upside by checking the 4 key rewards and 4 important warning signs
Looking for more investment ideas beyond HomeCo Daily Needs REIT?
If HomeCo Daily Needs REIT has your attention, do not stop there. Broader context from other opportunities can sharpen your decisions and reveal gaps in your portfolio.
- Target resilient performers with steadier profiles by scanning a 7 resilient stocks with low risk scores that filters for companies with more measured risk scores.
- Hunt for quality at a discount by using the 4 high quality undervalued stocks to spot stocks where solid fundamentals meet more modest valuations.
- Pinpoint robust balance sheets by reviewing the list of solid balance sheet and fundamentals (11 results) that highlights businesses with stronger financial footing and cleaner fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com