
Kyushu Railway (TSE:9142) Slides Into Focus As Valuation Signals Split
Kyushu Railway (TSE:9142) has come back into focus after a recent share price slip over the past month, with the stock closing at ¥3,539 as investors reassess its long term return profile.
Over the past year Kyushu Railway has seen its share price return fall 13.26% year to date, even as the 5 year total shareholder return of 53.60% and 3 year total shareholder return of 20.69% point to a sturdier long run record. This suggests the recent pullback may reflect a cooler view on near term prospects rather than a complete break with its longer history.
Scan how Kyushu Railway compares with other transport and infrastructure plays under pressure this year by checking our curated list of 19 high quality undervalued stocks.
Kyushu Railway now trades below analyst targets after the recent slide, yet the stock screens as expensive on some intrinsic measures. Is the market rightly cautious, or mispricing a long term operator in its region?
Preferred P/E of 12.2x for Kyushu Railway: Is it justified?
On simple earnings terms, Kyushu Railway trades on a P/E of 12.2x at a share price of ¥3,539, which screens as inexpensive relative to several reference points, even as the stock has fallen behind both the broader Japanese market and the transportation sector over the past year.
The P/E multiple compares what investors are currently paying for each unit of profit to both the wider market and industry peers. For a mature transport and infrastructure operator like Kyushu Railway, this ratio is a common yardstick because earnings quality and stability tend to matter more than rapid expansion.
At 12.2x earnings, the valuation sits below the estimated fair P/E of 15.3x. It is also slightly under the JP Transportation industry average of 12.3x, the peer average of 12.9x, and the broader JP market level of 14.1x. Taken together, these gaps indicate that the market is assigning a discount relative to where similar businesses trade and to where regression based analysis suggests the multiple could gravitate over time.
Explore the SWS fair ratio for Kyushu Railway.
Result: Price-to-earnings of 12.2x (UNDERVALUED)
Still, Kyushu Railway faces risks if passenger volumes or its real estate and hotel income soften, or if analyst expectations embedded in price targets reset lower.
Find out about the key risks to this Kyushu Railway narrative.
Another View on Kyushu Railway’s Valuation
The P/E workup paints Kyushu Railway as modestly cheap, yet the SWS DCF model points the other way. On that cash flow view, the current price of ¥3,539 sits above an estimated value of ¥2,207.34, which frames the shares as overvalued on this second yardstick.
For investors who rely on long term cash flows rather than earnings multiples, that gap raises a simple question. Is the earnings based discount enough to offset DCF downside risk, or is the cash flow view the one to lean on next time you reassess the stock?
Look into how the SWS DCF model arrives at its fair value.
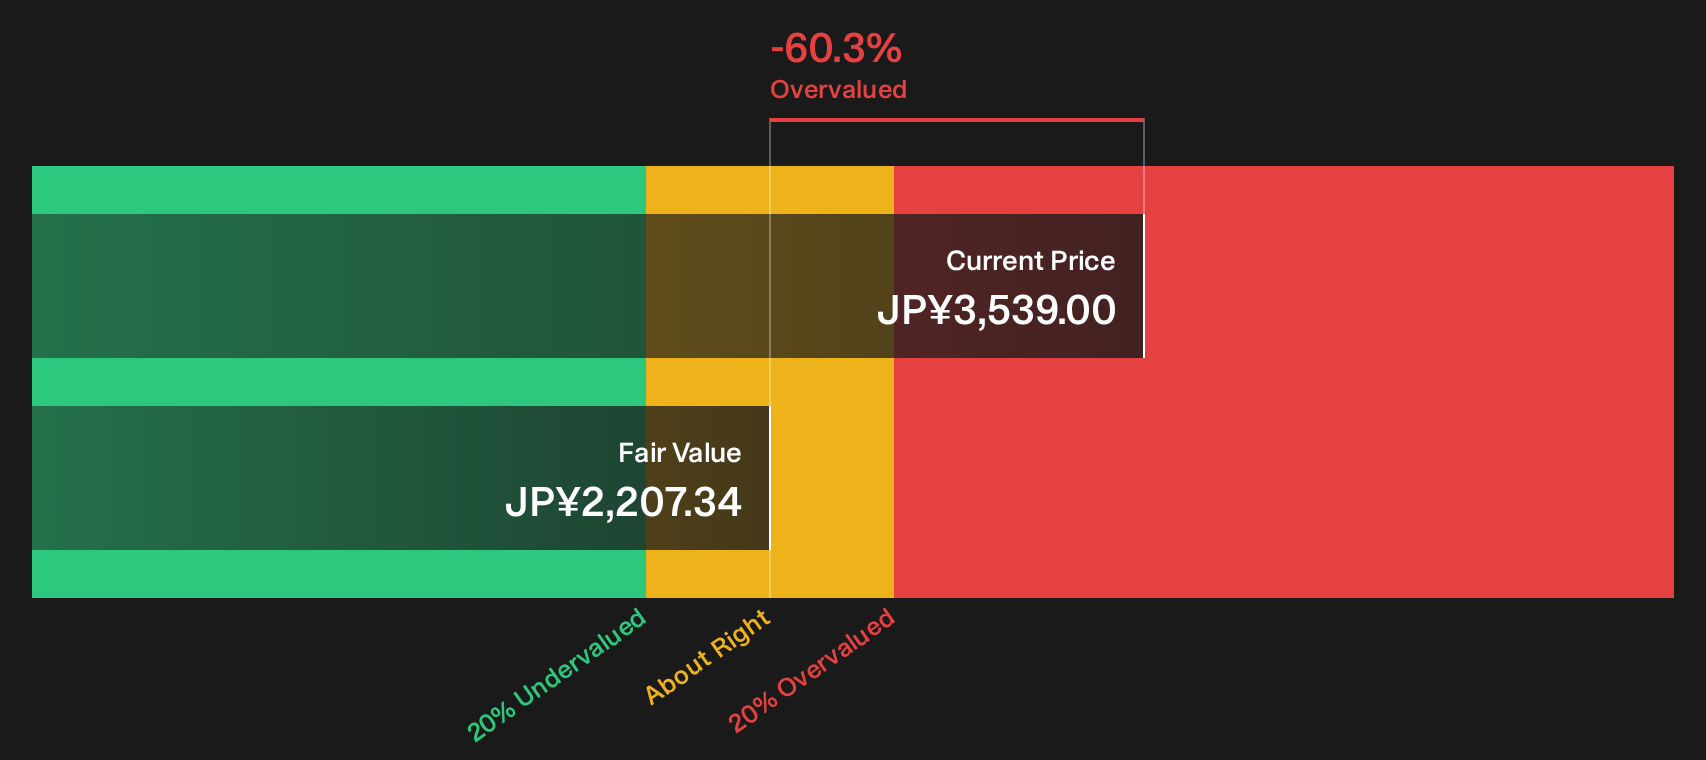
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kyushu Railway for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Kyushu Railway’s value story do not have to leave you on the fence. Act while the details are fresh, stress test the thesis yourself, and then round out that view with the 3 key rewards and 2 important warning signs
Looking for more Kyushu Railway investment ideas?
If Kyushu Railway has sharpened your focus on valuation and risk, do not stop here. Fresh ideas now could shape your next decade of returns.
- Target stability first and see which companies pass our stringent balance sheet and fundamentals checks through this focused list of solid balance sheet and fundamentals (22 results).
- Hunt for potential mispricing and compare Kyushu Railway with a curated 19 high quality undervalued stocks that combine quality metrics with appealing valuations.
- Prioritise resilient compounding income by reviewing a hand picked 14 dividend fortresses designed to spotlight higher yielding payouts with supportive fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com