
Palo Alto Networks (PANW) Could Be 5% Undervalued After Its New AI Defense Launch
Palo Alto Networks (PANW) just rolled out its Unit 42 Continuous Frontier AI Defense service, using advanced models from OpenAI and Anthropic to patrol customer systems, as its stock adjusts alongside a broader cybersecurity sector rethink.
Recent trading shows that sentiment around Palo Alto Networks is cooling from an earlier surge. The share price slipped 3.9% in the latest session, even after a 12.9% 90 day share price return and a 3 year total shareholder return of 219.7%. This suggests strong long term momentum but a near term reset as investors reassess how much AI driven cybersecurity growth they are willing to pay for.
Scan how Palo Alto Networks fits into the AI security story alongside other potential breakout plays with our hand-picked 85 AI infrastructure stocks today.
Bulls point to Palo Alto Networks’ AI subscriptions, 33.6% revenue growth outlook and multi-year share gains. Bears highlight rich expectations after this pullback. Which side does the current valuation actually support?
Most Popular Narrative: 5% Undervalued
The most followed narrative currently pins Palo Alto Networks’ fair value at $395.38, only modestly above the last close at $374.74. This frames the stock as pricing in a lot of its AI security story already while still leaving a small valuation gap tied to execution.
Strategic investments in AI-driven security, automation, and differentiated product innovation (e.g., AI firewalls, SASE, secure browser, Cortex Cloud, XSIAM) are driving rapid ARR growth in high-value segments (>32% NGS ARR growth and over 2.5x AI ARR YoY), supporting a move towards higher-margin, recurring revenue streams and improved long-term net margins.
See why 367 investors see Palo Alto Networks as 5% undervalued.
Result: Fair Value of $395.38 (UNDERVALUED)
Still, the bullish Palo Alto Networks story could be challenged if large platform deals slow, or if rising R&D and integration costs squeeze profitability more than expected.
Find out about the key risks to this Palo Alto Networks narrative.
Another View on Palo Alto Networks Valuation
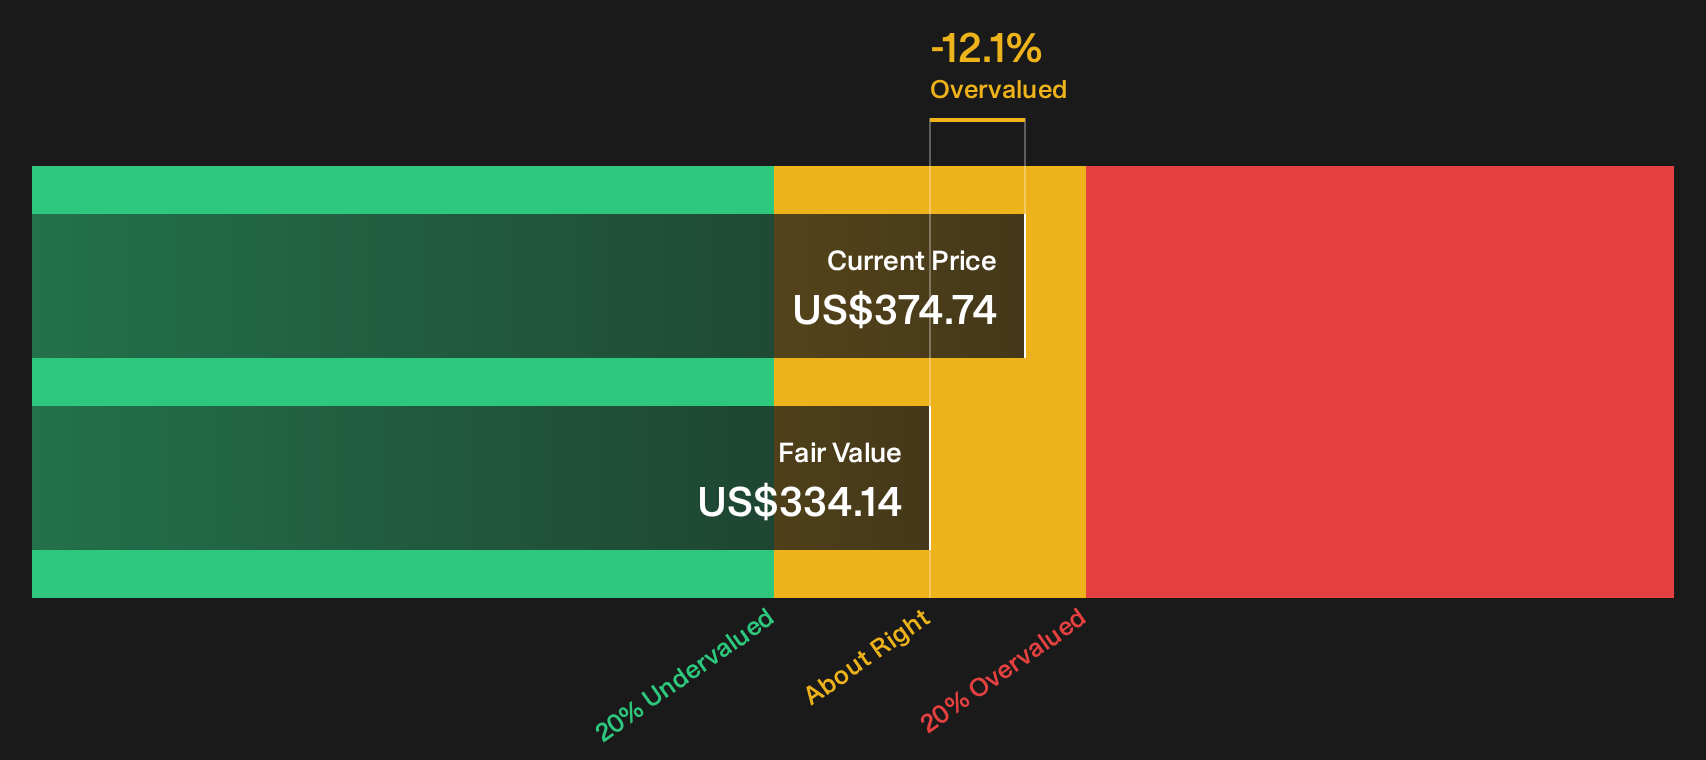
While the popular narrative frames Palo Alto Networks as about 5% below fair value, the SWS DCF model points the other way. On that cash flow view, the stock at $374.74 sits above an intrinsic value estimate of $334.14, which raises the question of how much future AI upside is already reflected in the price.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the Palo Alto Networks story so far feels split between optimism and caution, move quickly to check the data and sharpen your own view with 1 key reward and 3 important warning signs.
Looking for more Palo Alto Networks style investment ideas?
Do not stop your research with Palo Alto Networks alone. Use the Simply Wall Street Screener to uncover fresh opportunities that match your risk profile and return goals.
- Target potential mispricings by hunting for quality businesses that still trade at appealing valuations through the 32 high quality undervalued stocks.
- Focus on resilience by filtering for companies with strong financial footing using the list of solid balance sheet and fundamentals (24 results).
- Boost your income plans by zeroing in on payout heavy opportunities with the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com