
Cui Dongshu: China's automobile imports of 23,000 vehicles fell 51% year on year in August
The Zhitong Finance App learned that Cui Dongshu, Secretary General of the Passenger Transport Association, published an article stating that in August 2026, 23,000 imported cars were imported, down 51% year on year and 48% month-on-month, an astonishing drop. From January to August 2026, 270,000 cars were imported, a year-on-year decrease of 17%. Imported cars accounted for 49% of passenger cars from January to August 2026, but the share of imports fell to 38% in August; imported passenger cars with 9 seats or less performed well at 24% in January-August 2026; imported four-wheel drive SUVs accounted for 25% of imports this year, which rebounded to 46% of passenger car imports in August. The performance of imported hybrid vehicles increased by 8% from January to August 2026. The performance of pure electric passenger cars decreased by 37%, plug-in hybrid cars decreased by 62%, and the performance of imported new energy passenger vehicles was weak.
The downward pressure on imported cars was still strong in August. The top 10 countries with the highest imports in August 2026 were: Germany with 7,393 vehicles, the United States with 4,972 vehicles, Slovakia with 3,645 vehicles, the United Kingdom 2,366, Japan with 681 vehicles, Italy 335, Austria 306, Thailand 246, and Poland with 67 vehicles. Among them, the top five that increased in the current period over the same period were: the US 2,070, Mexico 258, Thailand 246, and Austria 124.
The top 10 countries with the highest imports from January to August 2026 were: Japan with 12,9253 vehicles, Germany with 59,183 vehicles, the United States 27,559, Slovakia 19004, the United Kingdom 16,315, Mexico 4156, Austria 3838, Thailand 2,260, Italy 696, and Sweden 675 vehicles. Among them, the top five that increased over the same period were: Japan 3825, Thailand 2021, Austria 1,841, Mexico 1,269, and China 530.
Against the backdrop of a continuous decline in imported cars in recent years, Lexus's retail share of the imported luxury car market was 44.6% in August 2026, up about 7 percentage points from 37.6% in 2025. The overall performance of BMW, Porsche, and Land Rover was relatively good.
Demand in the domestic and imported luxury car markets is generally weak. Among them, luxury car markets in traditional wealthy regions such as Beijing, Ningbo, Hangzhou, and Chengdu are under high pressure.
I. Overall trend of China's automobile imports
1. Characteristics of the growth rate of automobile imports
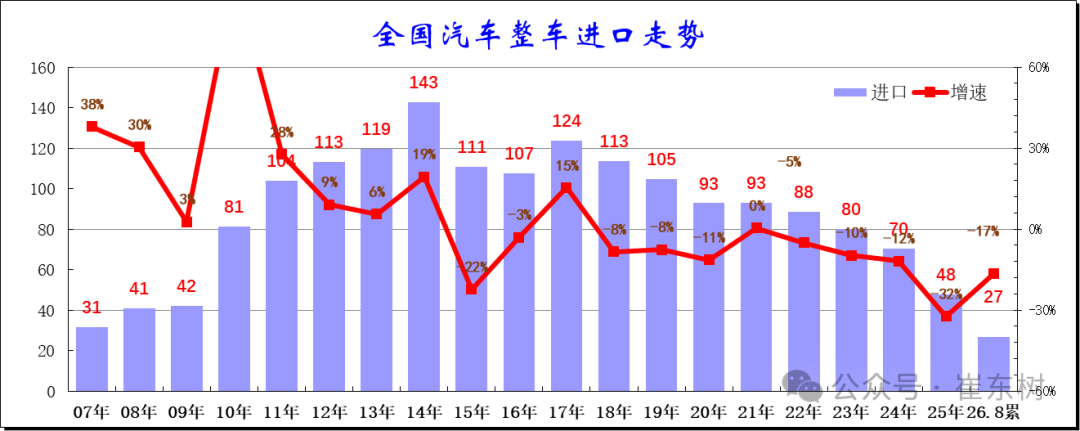
After reaching a peak of 1.43 million imported cars in 2014, the import growth rate improved slightly steadily in 2016-2017, and continued to decline since 2018. The import scale continued to decline sharply in 2024. The annual imports were only 700,000 vehicles, down 12% from the previous year. However, in 2025, the number of imported cars was 480,000, a decrease of 32% over the previous year, and the pressure on imported cars to continue to shrink is strong. From January to August 2026, 270,000 cars were imported, down 17% year on year. Under a low base, the decline in imported car imports in 2026 is still quite drastic.
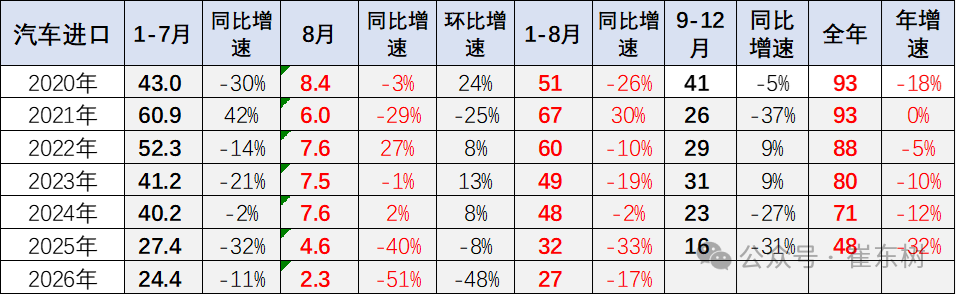
In August 2026, 23,000 imported cars were imported, down 51% year on year and 48% month on month. The decline was astonishing. From January to August 2026, 270,000 cars were imported, a year-on-year decrease of 17%. The beginning of 2026 was still a relatively good performance in January-August, which is rare recently, mainly due to the low base at the end of 2025. However, due to the low base in January 2025, although transportation was blocked due to the war between the US and Iran, the overall decline in imported cars in 2026 was small. With the rise of domestic cars and the acceleration of localization of international brands, automobile imports have continued to be sluggish in recent years. Imported cars have continued to grow negatively for 3 years. If the fluctuations are ironed out, this is 8 consecutive years of negative growth.
2. Monthly trend of vehicle imports
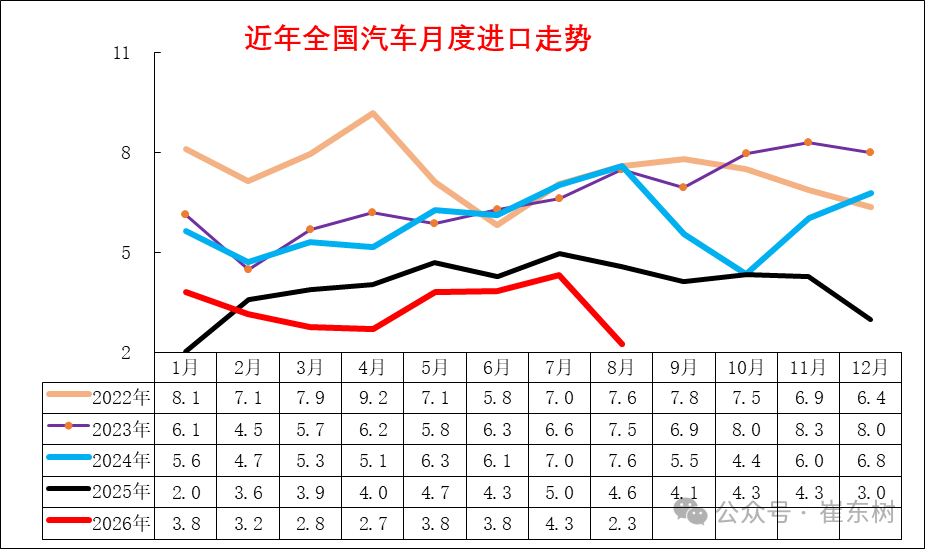
The decline in imports at the beginning of 2025 was astonishing. As trade between China and the US can be expected, imported cars gradually picked up in 2025 and hit a new high in July. However, with the rise of independent high-end cars, imported cars continued to be sluggish in August/November, and the abnormal decline fell back in December 2025, driving growth in January 2026.
The sharp drop in imports in August 2026 was due to a sharp decline in Japanese imports. The fuel vehicle market has returned to a dull, steady downward trend.
3. Structural characteristics of automobile imports
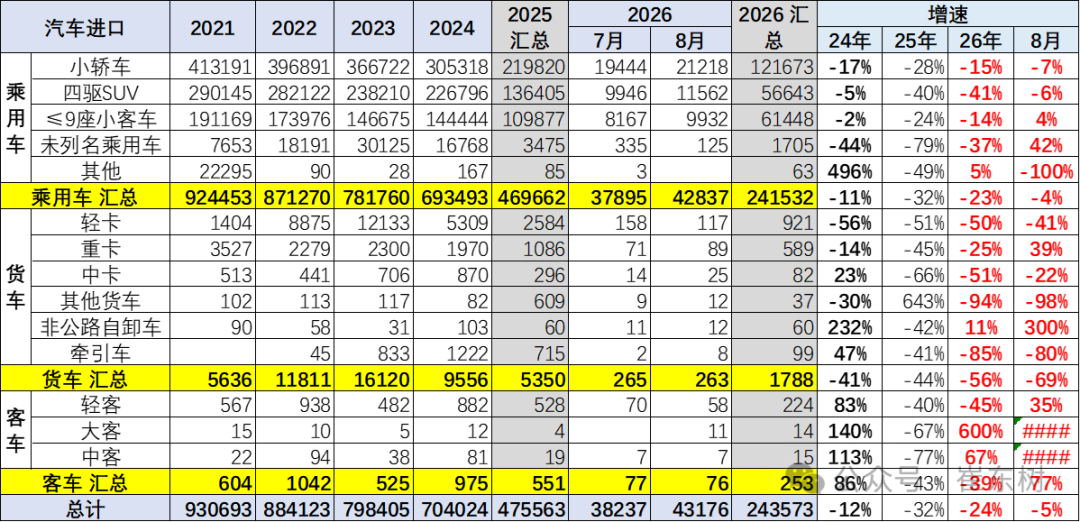
Since 2019, all types of imported models have declined across the board. Traditional trucks are currently falling back rapidly and markedly. Passenger car imports were less than demand in August 2026, and inventories declined.
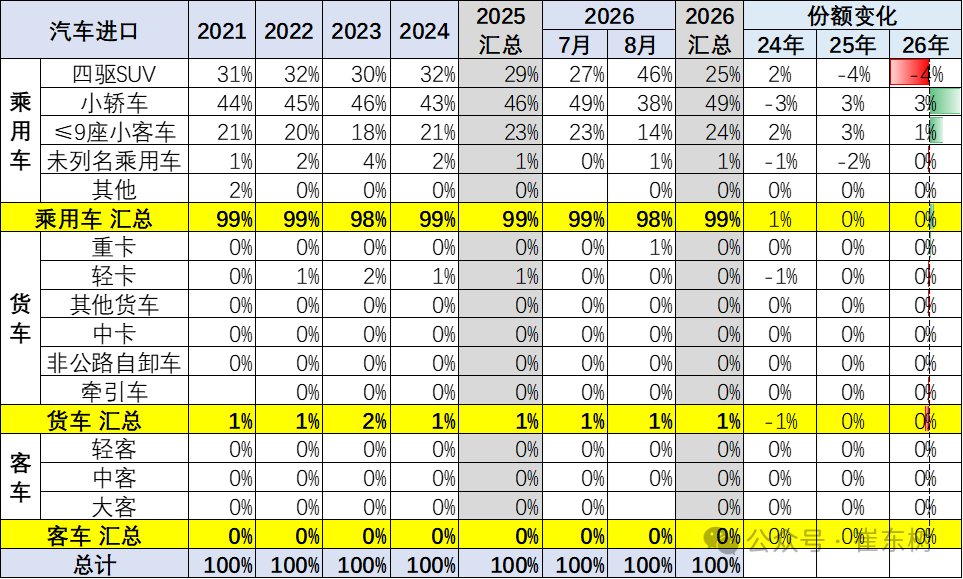
Passenger cars account for over 99% of the automobile import structure this year. If pickups in light trucks are included, the number of passenger cars is even higher.
Imported cars accounted for 49% of passenger cars from January to August 2026, but the share of imports fell to 38% in August; imported passenger cars with 9 seats or less performed well, accounting for 24% in January-August 2026; imported four-wheel drive SUVs accounted for 25% of imports this year, which rebounded to 46% of passenger car imports in August; while unlisted motor vehicles accounted for 1% of imports. Commercial vehicle import performance in 2026 was average. In particular, imports of light trucks did not decline much, and recently imported pickup trucks were also weak.
4. Characteristics of the import structure of new energy vehicles
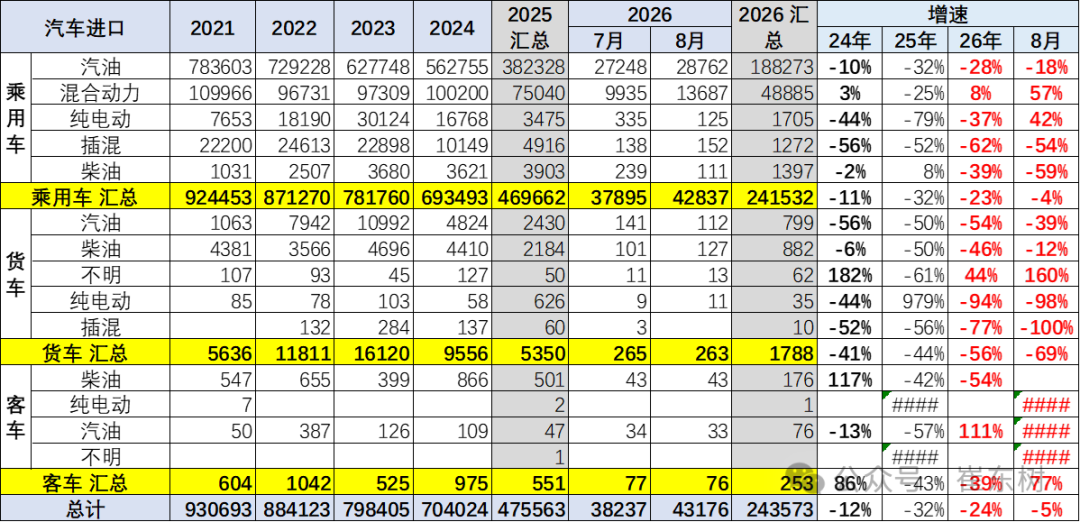
Imported new energy passenger vehicles achieved continued high growth in 2021-2023, and there was a sharp decline in 2025. The performance of imported hybrid vehicles increased by 8% from January to August 2026. The performance of pure electric passenger cars decreased by 37%, plug-in hybrid cars decreased by 62%, and the performance of imported new energy passenger vehicles was weak.
The traditional fuel imported car market for passenger cars has rebounded significantly, and the share of hybrid vehicles has rebounded. However, the decline in the share of gasoline trucks is related to the demand for tractors.
The import performance of high-end gasoline pickups in 2026 was poor. Recently, the domestic NEV pickup market has performed relatively well, but the imported pure electric pickup truck market has performed relatively poorly.
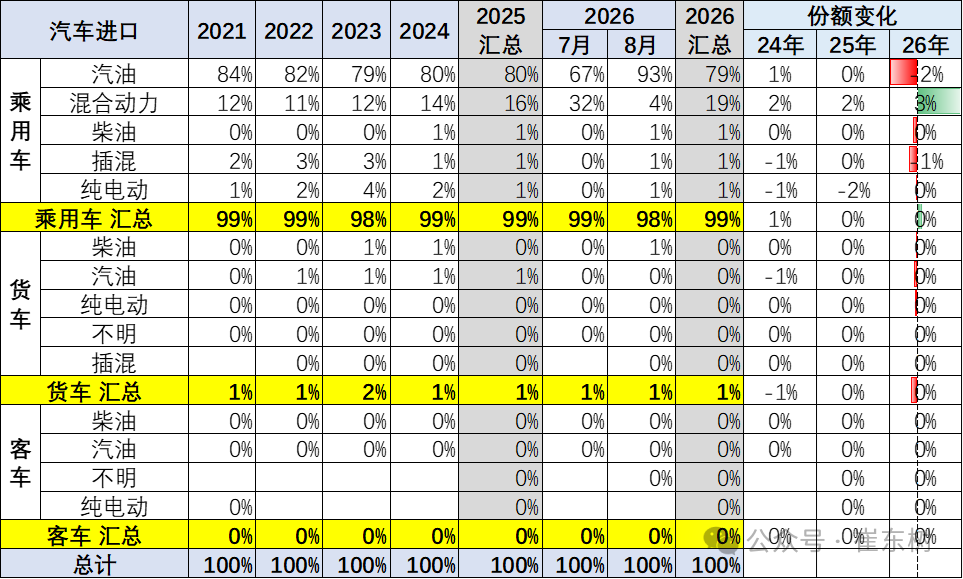
In 2024, imported passenger cars accounted for 3% of new energy imports. From January to August 2026, the share of imported new energy vehicles dropped to 2%. Pure electric vehicles dropped sharply compared to last year, and fuel-fuel passenger cars are still the absolute main force. The proportion of gasoline vehicles among trucks is still high, and the decline in pure electric trucks is huge.
5. Structural characteristics of passenger vehicle import emissions
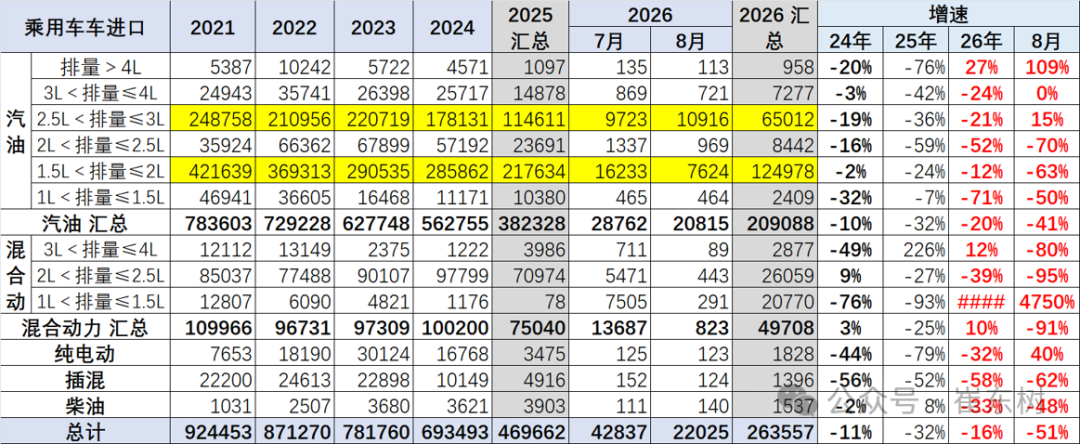
The displacement of imported models of passenger cars is concentrated on gasoline models below 2 liters. Last year, 3-4 liters had a better ability to withstand falling, and 1.5-2 liters was relatively good this year.
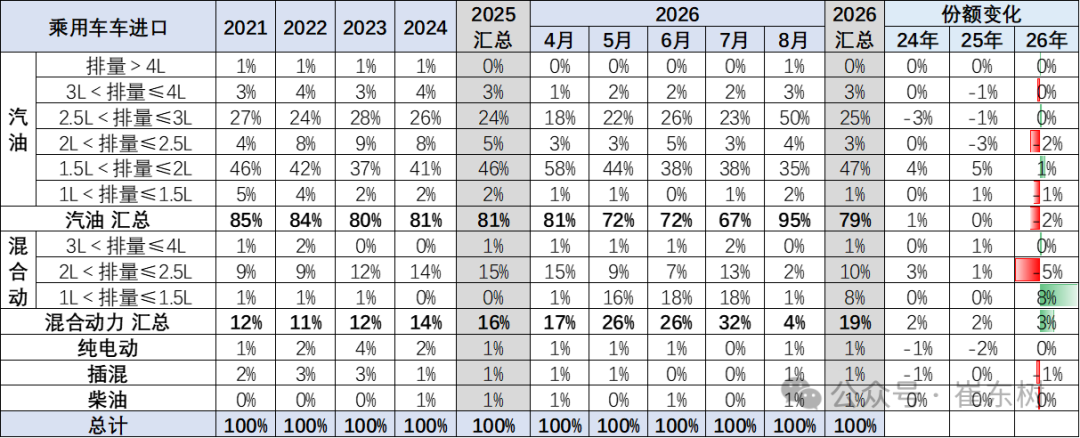
The displacement of imported passenger cars is concentrated on gasoline models below 2 liters. January-August 2026 accounted for more than half of the total import volume of imported cars, which is basically the same as last year.
There is a clear trend of moving imported hybrid models from 2.5 to 1.5 liters.
II. The pattern of the automobile import market
1. Import characteristics by country
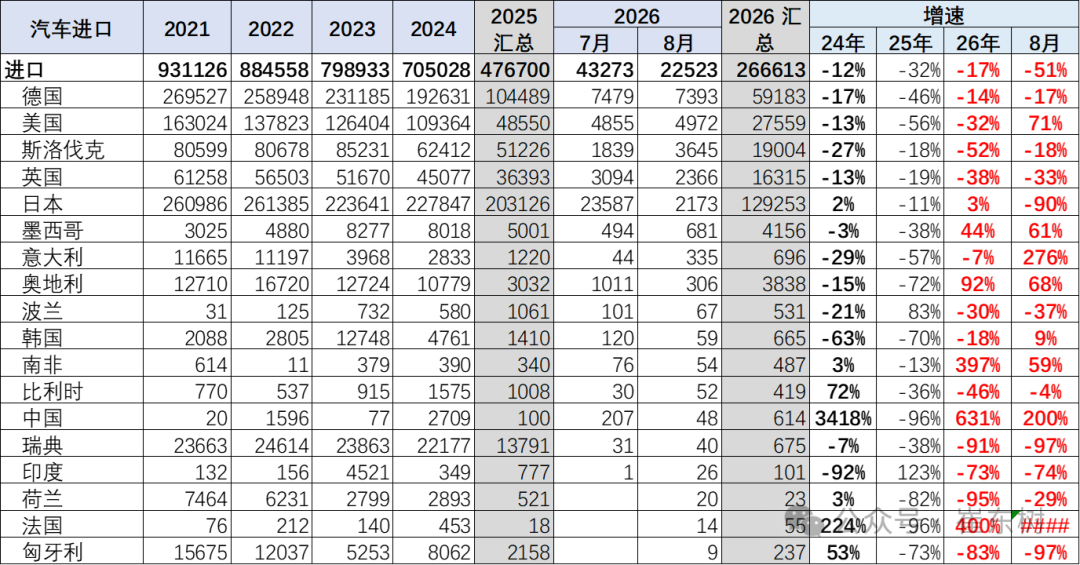
China's passenger car importers are still centered around Germany, Slovakia, the United States, and the United Kingdom. Recently, Japan's import performance has changed dramatically, and Japanese car imports lost a lot in August.
2. Monthly trend of vehicle imports
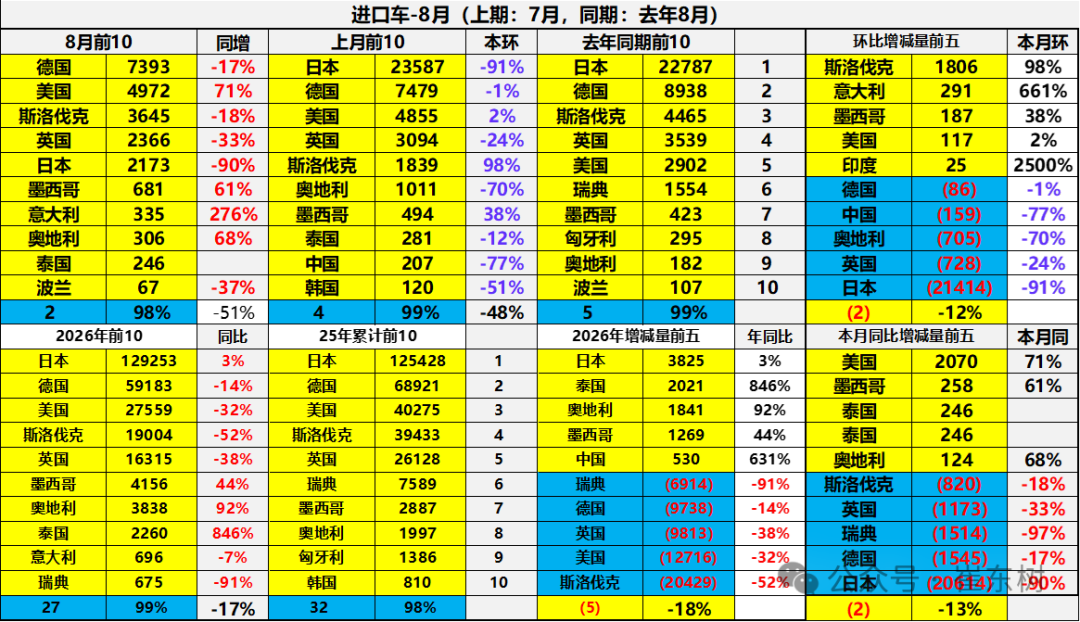
The downward pressure on imported cars was still strong in August. The top 10 countries with the highest imports in August 2026 were: Germany with 7,393 vehicles, the United States with 4,972 vehicles, Slovakia with 3,645 vehicles, the United Kingdom 2,366, Japan with 681 vehicles, Italy 335, Austria 306, Thailand 246, and Poland with 67 vehicles. Among them, the top five that increased in the current period over the same period were: the US 2,070, Mexico 258, Thailand 246, and Austria 124.
The top 10 countries with the highest imports from January to August 2026 were: Japan with 12,9253 vehicles, Germany with 59,183 vehicles, the United States 27,559, Slovakia 19004, the United Kingdom 16,315, Mexico 4156, Austria 3838, Thailand 2,260, Italy 696, and Sweden 675 vehicles. Among them, the top five that increased over the same period were: Japan 3825, Thailand 2021, Austria 1,841, Mexico 1,269, and China 530.
3. National characteristics of new energy vehicle imports
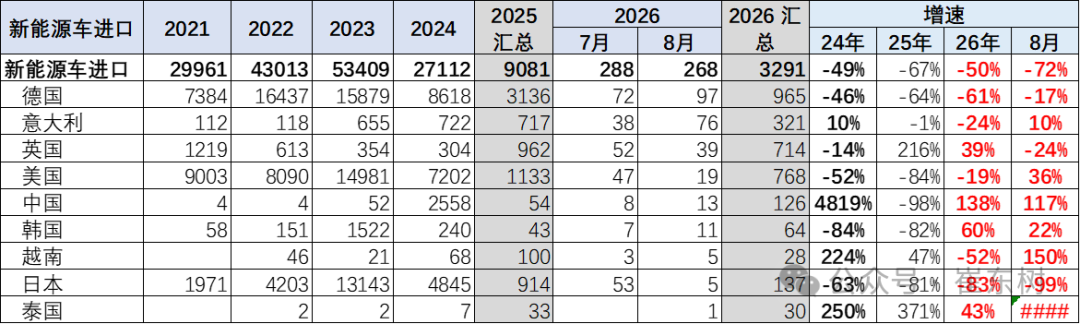
Domestic cars are more competitive in 2025, and imports of new energy vehicles from major importers fell by 50%. In 2026, the pressure to import new energy passenger cars further increased. Cars imported from Germany were very poor, and there was almost no sales volume of new energy imported from Japan and the US.
III. The sales pattern of the automobile market
1. Overall sales volume of imported cars
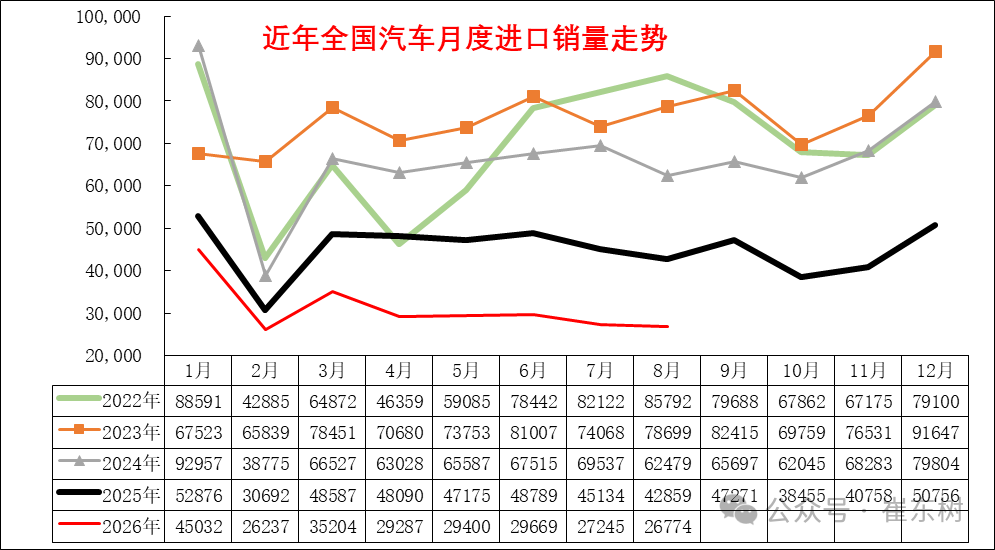
Imported cars were slightly lower than last year's trend in January-August. The decline was less than the trend in previous years. At the beginning of the year, imported fuel vehicles performed well, sales were poor in the 2nd quarter, and the trend continued to decline in August.
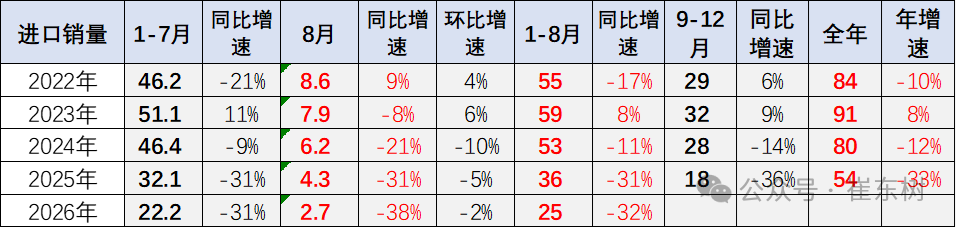
Due to the strength of China's autonomous car companies, the sales performance of imported cars continues to deteriorate, and it is also weaker than the trend in the domestic luxury car market.
The sales volume of imported cars from 2022 to 2024 is hovering between 800,000 and 900,000 units, and market pressure is gradually increasing. In 2025, the imported vehicle traffic insurance data was 540,000 vehicles, a decrease of 33% over the previous year. Due to the promotion of a low base in early 2025, imported cars sold 250,000 units in January-August this year. The performance was poor. The decline of 32% to 27,000 vehicles in August was poor, and the performance of falling 38% was very poor, and the pressure is still high in the future.
2. Characteristics of imported car brands
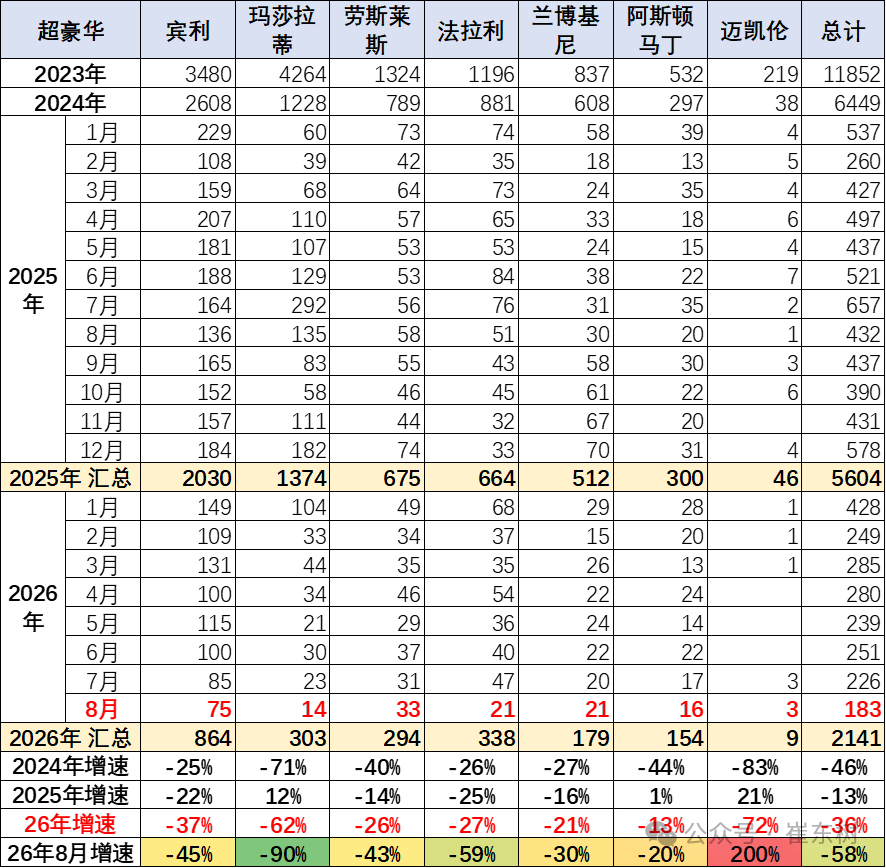
Imported ultra-luxury cars have continued to grow in the past few years, but there has been a major decline since 2023. The decline accelerated in 2024, and the decline in January-August 2026 is still severe. The trend of ultra-luxury fluctuated greatly. Maserati's overall trend in 2025 was abnormally high and declined in 2026. The trend of Bentley and Rolls-Royce is sluggish, but they have returned to leading positions in ultra-luxury. Lamborghini and Ferrari performed stronger. The overall weakening of ultra-luxury reflects a temporary slowdown in the purchasing power of ultra-high-end consumers, abnormal sales of ultra-luxury cars caused by early sell-offs, and a reasonable return to market prices.
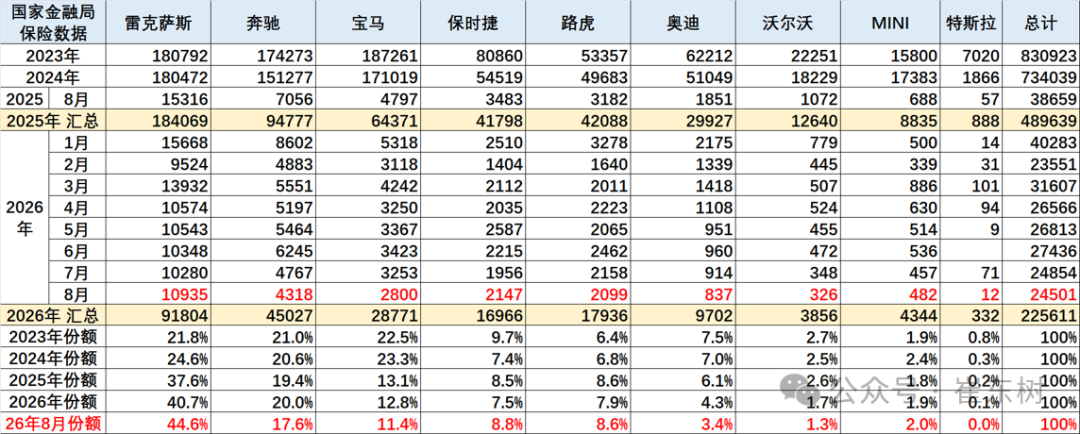
Currently, imported cars are mainly supported by demand for luxury cars, and non-luxury imported cars are shrinking sharply. Among imported cars, the share of the main imported luxury cars has increased dramatically. Imported cars from joint venture brands are shrinking rapidly, and imported cars from some brands, such as European cars imported from Volkswagen, are shrinking drastically.
Lexus's retail sales data for imported insurance in 2025 was 184,000 units, up 2% year on year. The share reached 37.6% of imported luxury cars, and Lexus' sales volume in 2025 was higher than 2022 sales, and remained at the level of 180,000 units for three consecutive years from 2022 to 2024.
Lexus's retail share of the imported luxury car market was 44.6% in August 2026, up about 7 percentage points from 37.6% in 2025. The overall performance of BMW, Porsche, and Land Rover was relatively good.
3. Characteristics of regional changes in imported ultra-luxury car brands
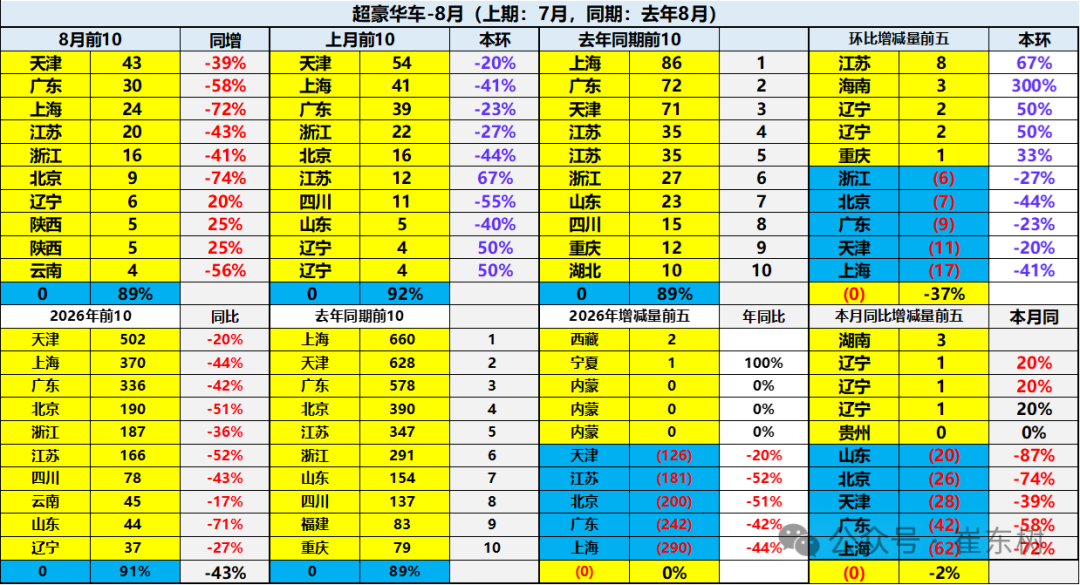
Demand in the ultra-luxury market for imported cars is generally weak. Tianjin has maintained the number one ultra-luxury ranking. Recently, Beijing has declined significantly.
The imported ultra-luxury car market is under high pressure in traditional affluent regions such as Beijing, Xi'an, Suzhou, Xiamen, and Fuzhou. The impact of new energy vehicles on ultra-luxury is reflected in the fact that due to the contraction of the ultra-luxury market, market demand is generally poor, and the price system is under high pressure.
4. Regional change characteristics of luxury cars
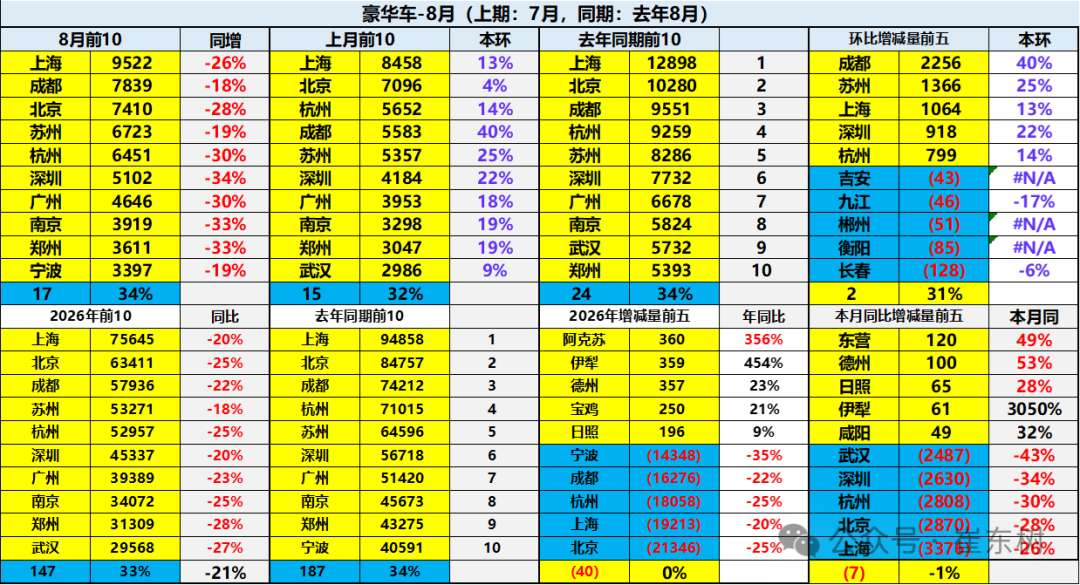
Demand in the domestic and imported luxury car markets is generally weak. Among them, luxury car markets in traditional wealthy regions such as Beijing, Ningbo, Hangzhou, and Chengdu are under high pressure. This year, petroleum producing regions in northern and central western China, such as Xinjiang and Shandong, are strong.