
Learn Why The Bull Case For Credito Emiliano Stock Could Change Following 1b Covered Bond Issue
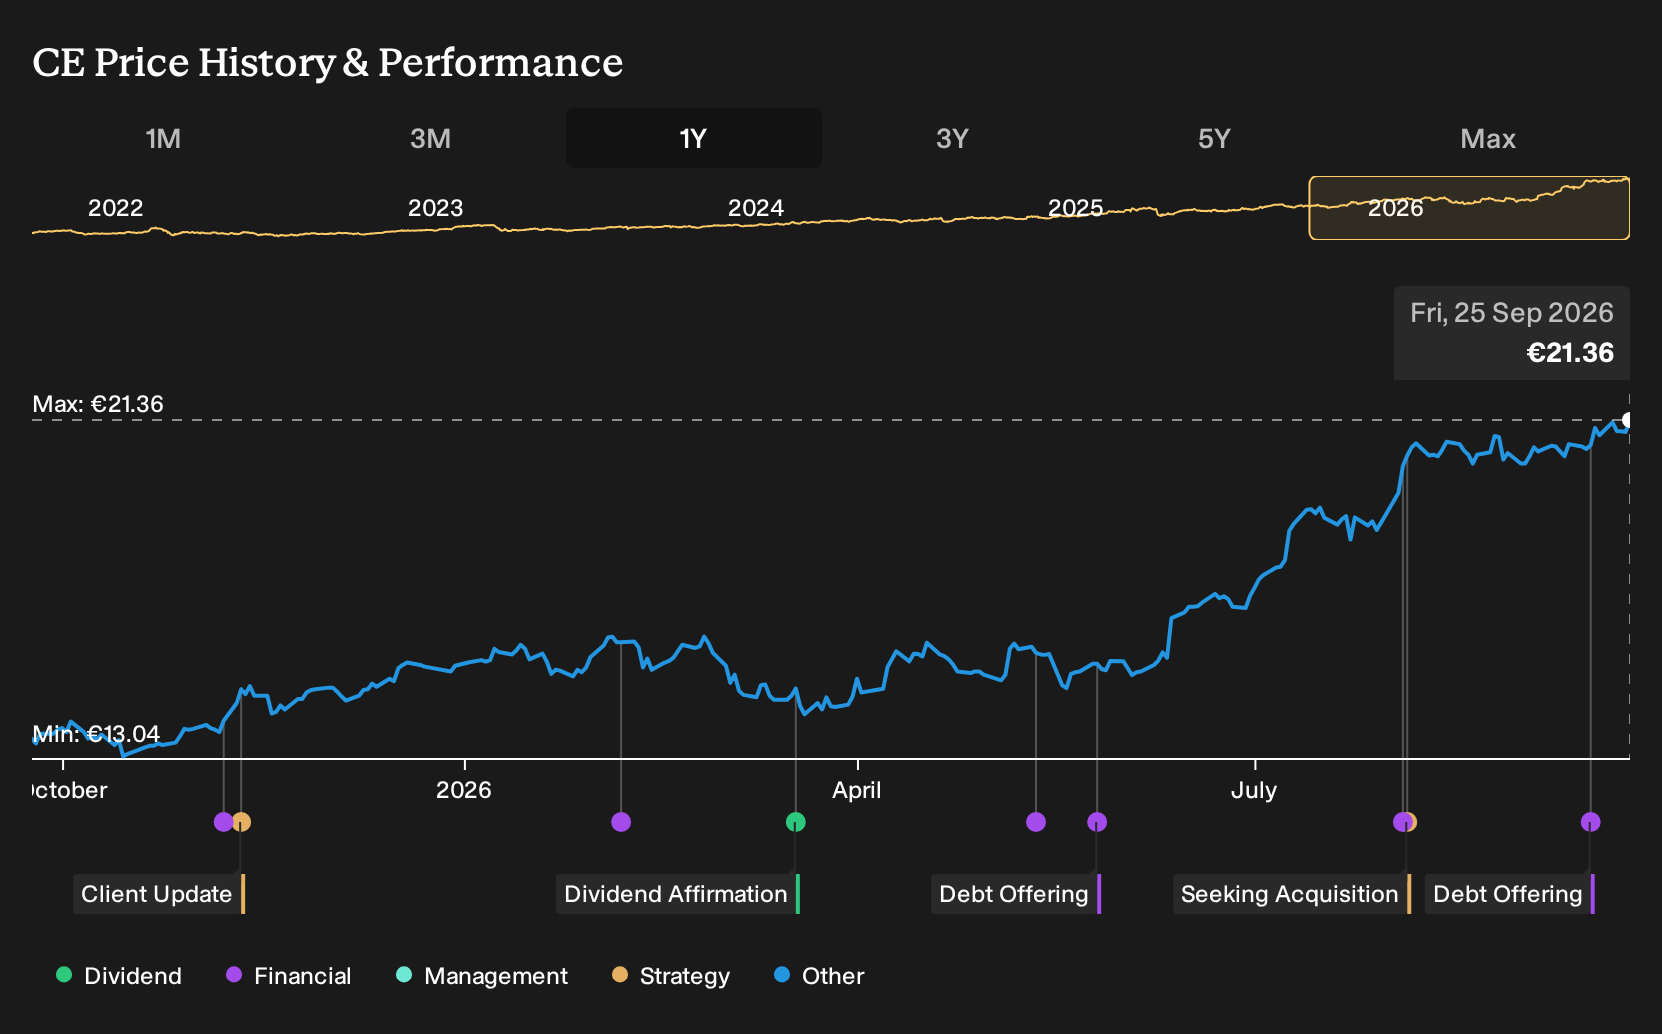
- Credito Emiliano has completed a €1b fixed to floating rate covered bond due September 18, 2031, issued at 100% with guarantees and senior secured status under Regulation S.
- The mix of secured structure, attached guarantees and variable coupon gives Credito Emiliano additional flexibility in shaping its future funding profile.
- This article examines how Credito Emiliano's investment narrative is affected by the €1b fixed to floating covered bond that has just priced.
Scan how Credito Emiliano’s covered bond move compares with other balance sheet focused plays by reviewing the curated list of solid balance sheet and fundamentals (201 results) that could reshape your watchlist.
Credito Emiliano Investment Narrative Recap
To own Credito Emiliano, you need to buy into an Italian bank that focuses on commercial banking and wealth management, with earnings that analysts expect to grow but not at high double digit rates. The key short term swing factor is how net interest income holds up as rates evolve and how fee income continues to support overall revenue.
The biggest risk is pressure on margins from higher regulatory and digital costs, while credit quality still needs strong provisioning given a 74% allowance for bad loans. The new €1b covered bond affects the funding mix more than day to day operations, so the near term earnings catalyst appears largely unchanged.
Among recent developments, the €1b fixed to floating covered bond is a clear link to Credito Emiliano’s current story. It adds term funding that is senior, secured and guaranteed, with a variable coupon that can adjust as interest conditions move. For an equity holder, this highlights how the bank refines its liability structure rather than signaling a radical shift in its business mix.
An important angle is how this funding tool fits within a balance sheet where analysts already focus on net interest margin resilience, fee income consistency and credit provisions. A covered bond of this size can support loan book funding and liquidity, while investors still need to monitor whether regulatory costs, digital spending and loan loss charges put pressure on returns on equity from here.
Credito Emiliano's narrative projects €2.2b revenue and €599.5 million earnings by 2029. This assumes 4.2% yearly revenue growth and an earnings increase of about €36.9 million from €562.6 million today.
Uncover how Credito Emiliano's fair value indicates a 10% potential downside to its current price, suggesting that the current premium may not be sustainable.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between €19.19 and €19.37, so community models around Credito Emiliano are closely aligned. Those views were formed before the €1b fixed to floating covered bond. Review several alternative opinions, since changing funding costs and regulation could shift how future returns are assessed.
Explore another Credito Emiliano fair value estimate, including one that suggests it could be worth as much as €19.37.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Credito Emiliano research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Credito Emiliano. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Credito Emiliano's overall financial health at a glance.
Looking for more Credito Emiliano style investment ideas?
If the Credito Emiliano story has sharpened your thinking on funding, risk and income resilience, you can use that same framework across a wider opportunity set with the Simply Wall St Screener.
- For investors who want quality at a discount, review a curated pool of companies that score well on fundamentals but trade below intrinsic value through the 182 high quality undervalued stocks.
- If stability and capital preservation sit higher on your priority list, you may focus on businesses that combine stronger balance sheets with lower risk profiles by scanning the 226 resilient stocks with low risk scores.
- Income focused readers can look at stocks that pair higher yields with sturdy cash flows by working through the 160 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com