
Pinnacle Financial Partners (PNFP) Could Be 21% Undervalued On Fed Rate Concerns
Recent remarks from Fed Chair Kevin Warsh on broad financial conditions have prompted investors to recheck how banks handle client cash and short term rates, putting fresh focus on Pinnacle Financial Partners (PNFP) and its pending Synovus merger.
The recent Fed commentary has landed on a stock that has been treading water near US$94.97, with Pinnacle Financial Partners showing a 30 day share price return that declined 6.5% and a 3 year total shareholder return of 47.1%. This points to longer term investors still sitting on sizeable gains even as near term momentum fades.
Scan regional banks that are under similar pressure from funding costs and short-term rates by jumping into our hand picked 30 resilient stocks with low risk scores alongside Pinnacle Financial Partners today.
Pinnacle Financial Partners now trades at a clear discount to both analyst targets and one estimate of intrinsic value after a choppy month. Is that simply mispricing, or is it a fair warning label on the Synovus merger and potential funding risks ahead?
Most Popular Narrative: 21% Undervalued
Pinnacle Financial Partners is framed as undervalued in the most widely followed narrative, with a fair value of about $120.32 against the recent $94.97 close. This puts the focus squarely on whether execution and capital choices can close that gap.
The main thing that has to go right is successful integration of the Synovus merger while preserving Pinnacle Financial Partners’ high-touch culture, maintaining strong credit quality, and delivering the full revenue synergy and productivity benefits of its specialty platforms and technology investments.
See why 23 investors see Pinnacle Financial Partners as 21% undervalued.
Result: Fair Value of $120.32 (UNDERVALUED)
Still, higher funding costs from US$750 million of senior debt and the longer Synovus integration timeline could pressure Pinnacle Financial Partners’ margins and earnings delivery.
Find out about the key risks to this Pinnacle Financial Partners narrative.
Another View: What Multiples Say About Pinnacle Financial Partners
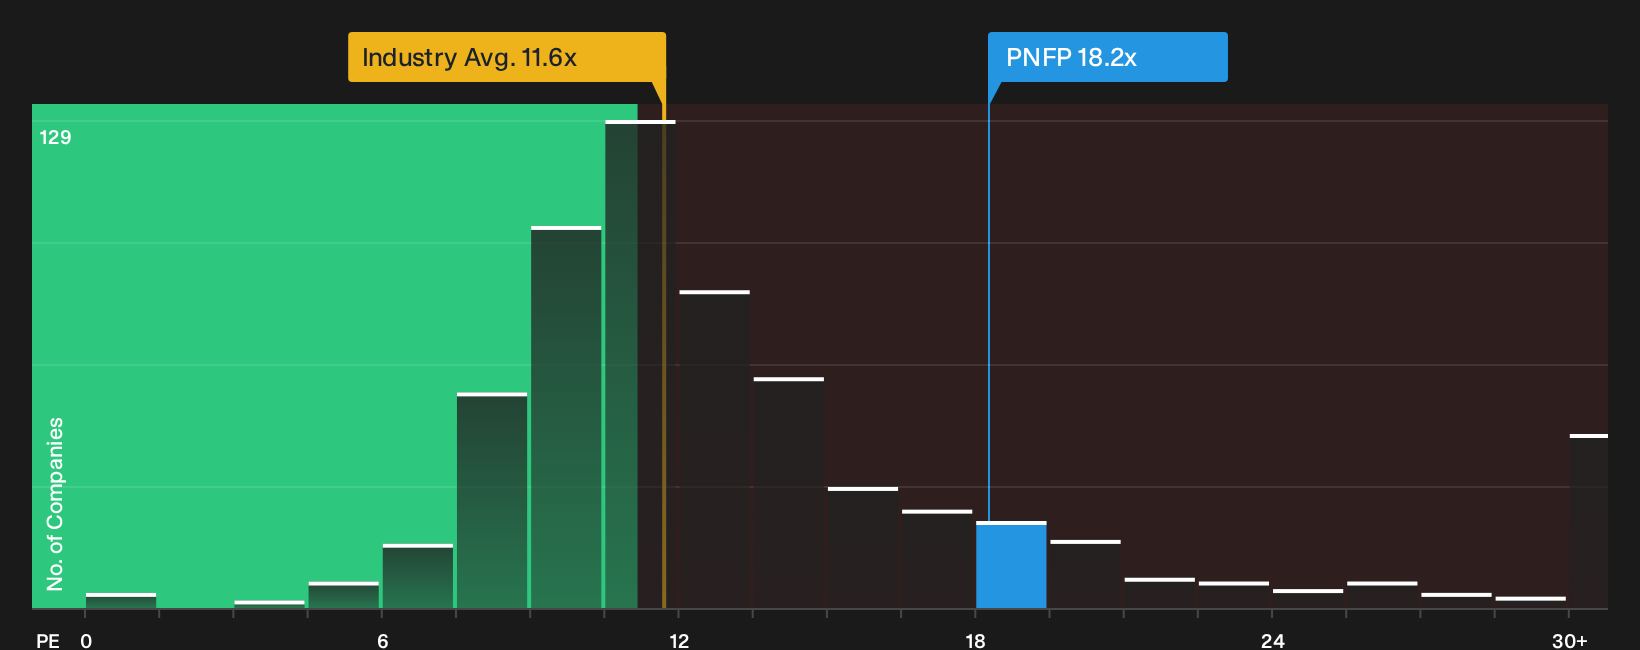
The first narrative leans heavily on Pinnacle Financial Partners looking undervalued on cash flow and analyst targets. Stepping back, the P/E picture feels less forgiving. PNFP trades on about 18.2x earnings, compared with roughly 11.6x for the wider US Banks industry and 11.2x for close peers.
That is a sizeable premium for a regional lender that is still working through a major Synovus integration and carrying a fresh US$750 million in senior debt. The fair ratio estimate of 20.8x suggests the market could move closer to that level, which leaves room on paper, but also adds valuation risk if expectations on earnings or returns reset.
Investors weighing the 46.3% discount to one fair value estimate against this richer P/E profile need to decide which signal matters more before leaning in or stepping back from PNFP at today’s price. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and risk often signal a split market view. Move quickly, study the numbers yourself, and then decide where you stand by weighing the 5 key rewards and 2 important warning signs.
Ready For More Ideas Beyond Pinnacle Financial Partners?
If Pinnacle Financial Partners has your attention, do not stop here. Use the same disciplined approach to uncover fresh opportunities that could reshape your portfolio.
- Target potential value opportunities by scanning companies that combine quality fundamentals with meaningful valuation gaps through our curated 32 high quality undervalued stocks.
- Build a portfolio around income by focusing on businesses with robust payouts using the high yield filter in the 8 dividend fortresses.
- Prioritise financial resilience by hunting for companies with strong balance sheets and solid fundamentals inside the tailored list of solid balance sheet and fundamentals (24 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com