
Fonterra Co Operative Group (NZSE:FCG) Lifts Earnings As Investors Ask If Value Remains
Fonterra Co-operative Group (NZSE:FCG) put fresh numbers on the table on 24 September, reporting full year 2026 results that lifted net income, earnings per share and underlying earnings.
That earnings backdrop has been met with strong share price momentum, with Fonterra Co-operative Group delivering a 24.5% year to date share price return and a 39.13% total shareholder return over the past year, while the 3 year total shareholder return above 300% signals that longer term investors have already been rewarded.
Capitalize on the momentum around Fonterra Co-operative Group by lining it up against our hand picked 182 high quality undervalued stocks, which combine strong cash generation with solid balance sheets poised for a breakout.Fonterra Co-operative Group now carries a strong recent run and fresh earnings in its back pocket. The real call for investors is whether to lean into that strength today or wait for a calmer entry.
Preferred P/E of 5.9x: Is it justified?
Valuation on Fonterra Co-operative Group is anchored by a P/E of 5.9x at a last close of NZ$4.98, while its earnings profile and recent share price gains suggest investors are still pricing it at a discount to peers.
The P/E multiple compares the current share price with earnings per share and is a quick way to see how much investors are paying for each dollar of profit. For a large dairy exporter such as Fonterra Co-operative Group, that lens matters because earnings quality, return on equity and growth history all feed into what the market is usually prepared to pay.
Fonterra Co-operative Group combines a P/E of 5.9x with high quality earnings and a 21.5% Return on Equity, so the current tag implies the market is assigning a relatively low price to those profits. The firm has also grown earnings by 12.1% per year over the past 5 years, with the latest year running ahead of that average, which makes the low multiple look even more compressed against that track record.
The discount is clearest when stacked against benchmarks. The same 5.9x P/E compares with 15x for the global food sector and 18.3x across its peer set, which signals a much lower valuation than both the wider industry and direct comparables.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 5.9x (UNDERVALUED)
Still, the story around Fonterra Co-operative Group can shift quickly if global dairy demand softens or if input costs put pressure on current earnings.
Find out about the key risks to this Fonterra Co-operative Group narrative.
Another view on Fonterra Co-operative Group's value
There is a very different message coming from the SWS DCF model. On that framework, Fonterra Co-operative Group at NZ$4.98 sits well below an estimated future cash flow value of NZ$35.79, which screens as deeply undervalued and raises fresh questions about how patient investors want to be.
Look into how the SWS DCF model arrives at its fair value.
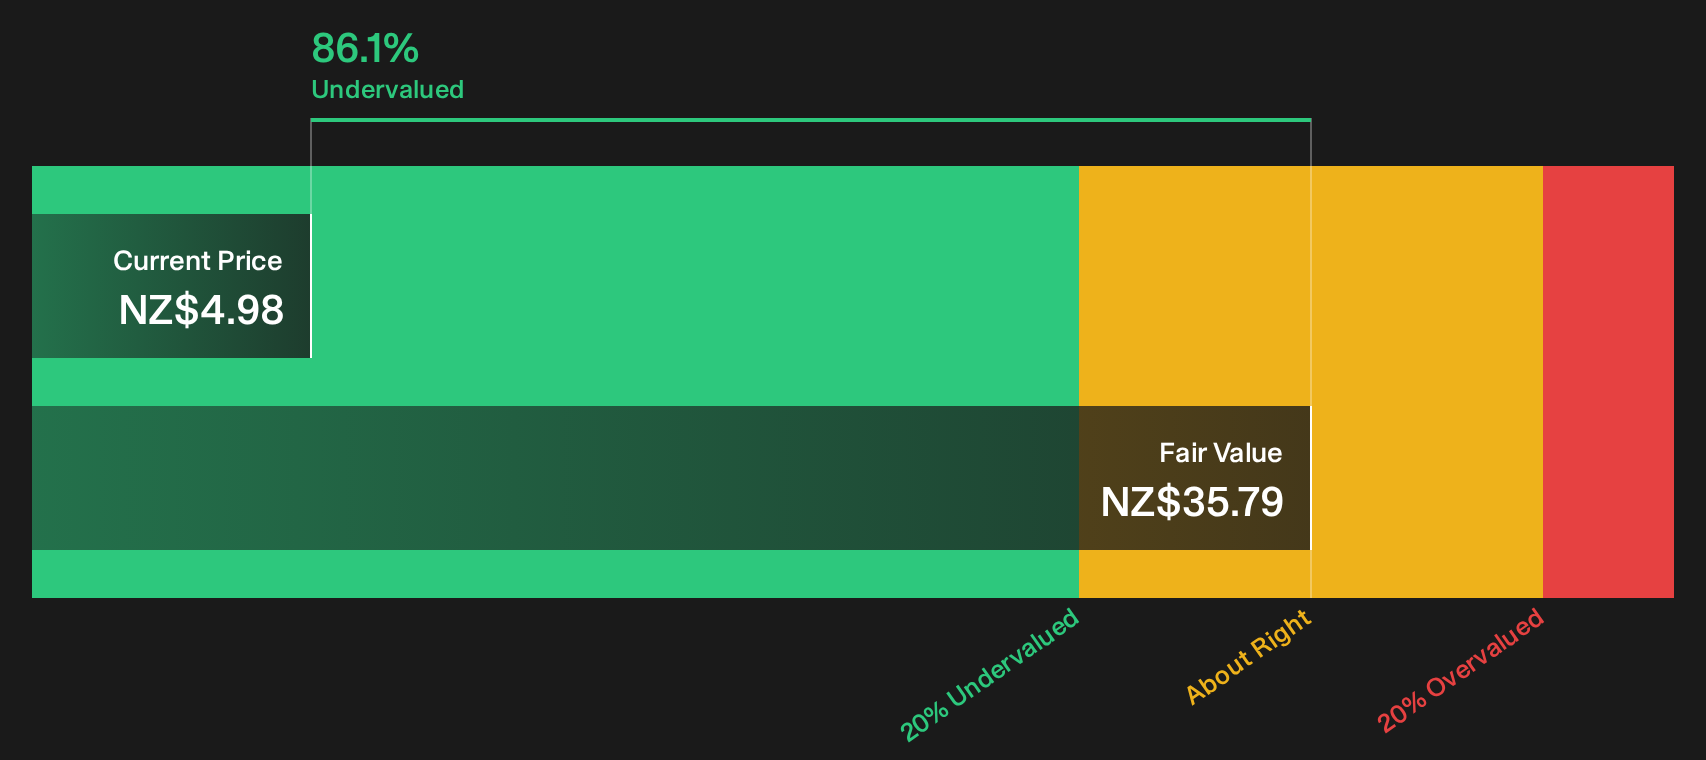
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fonterra Co-operative Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 182 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Strong numbers and a low P/E can feel convincing, yet mixed sentiment around Fonterra Co-operative Group means the picture is not one sided. Act while the data is fresh, compare the upside and downside for yourself and sharpen your thesis with the 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Fonterra Co-operative Group?
If the Fonterra Co-operative Group story has sharpened your thinking, do not stop there. Broader opportunities often sit just outside your current watchlist.
- Target potential comeback stories by scanning for beaten down opportunities with strong financials through the 129 elite penny stocks with strong financials.
- Prioritise quality at a discount by focusing on businesses that pair resilient cash flows with appealing valuations using the 182 high quality undervalued stocks.
- Build a steadier core by hunting for companies with strong balance sheets and fundamentals in the list of solid balance sheet and fundamentals (202 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com