
Did Sole Source Contract Just Shift Everforth (EFOR) Investment Narrative?
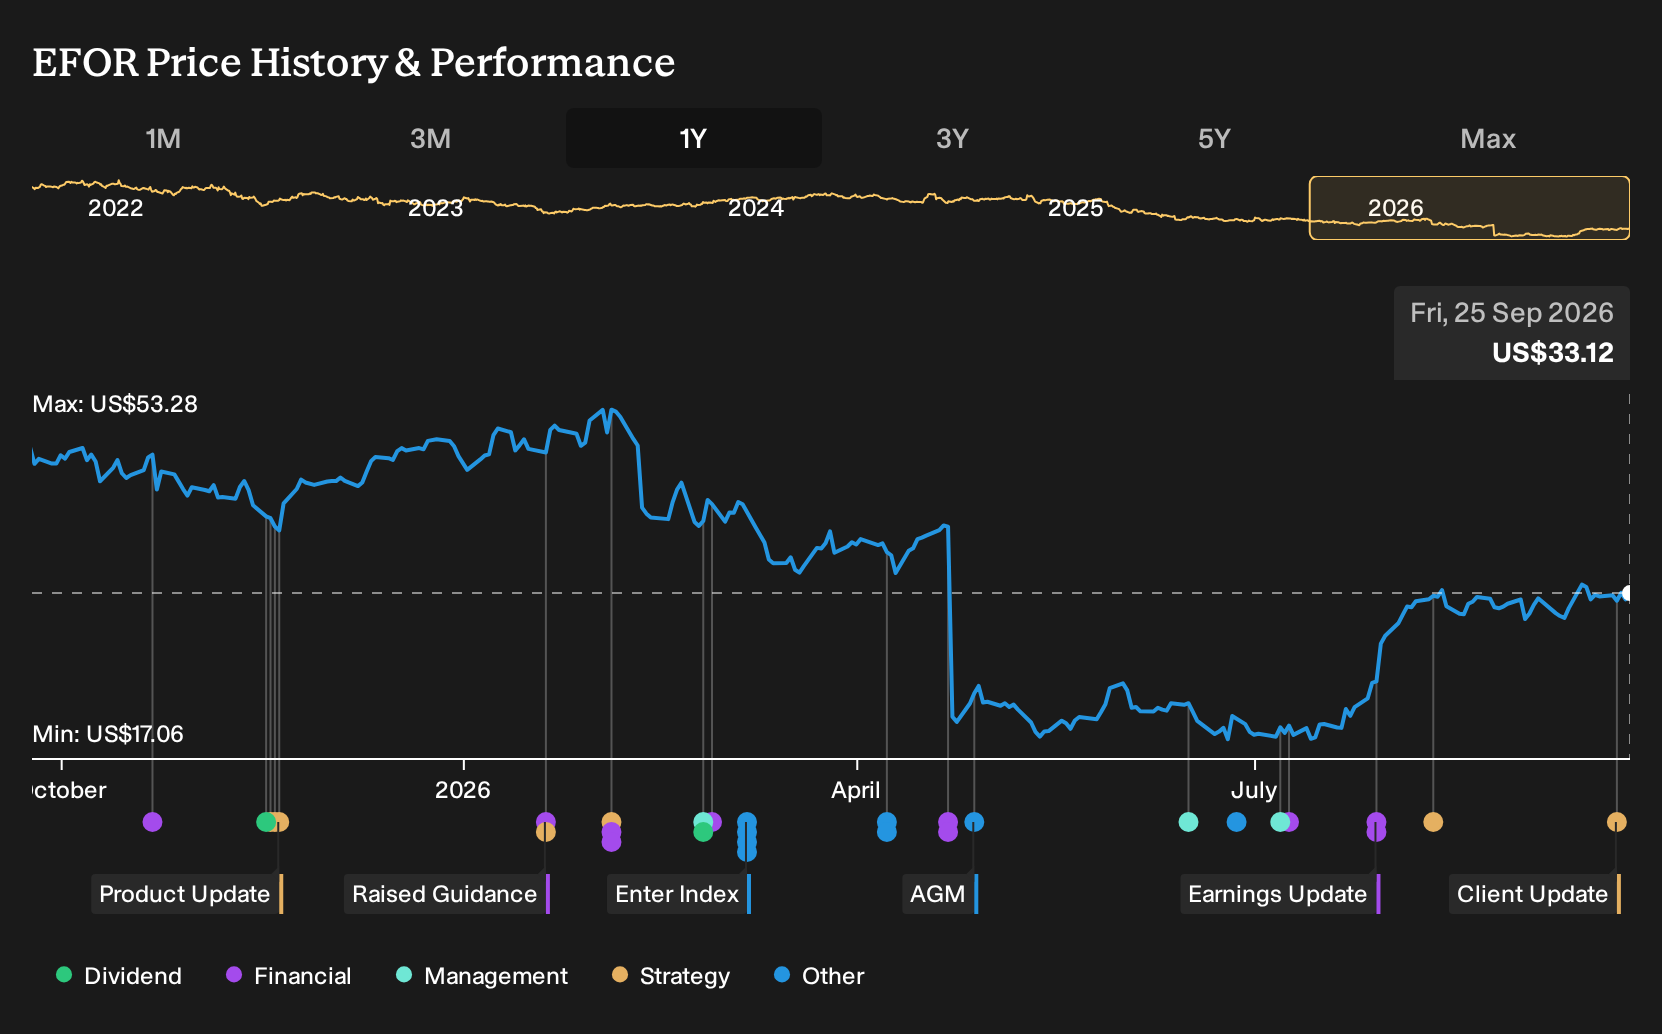
- Everforth, Inc. recently expanded its Microsoft partnership and secured a three-year, sole-source federal contract extension for SUNet, reinforcing its role in AI driven digital transformation across commercial and government clients.
- The combination of more than 1,500 Microsoft certifications, a unified commercial and federal model, and the SUNet 2.0 mandate points to heavier demand for Everforth’s AI, cloud, and cybersecurity services at enterprise and mission scale.
- We will now look at how Everforth's investment narrative could be influenced by the SUNet 2.0 contract and deeper Microsoft alignment.
Scan how Everforth’s AI and cloud story compares with other potential movers by reviewing the hand-picked 87 AI infrastructure stocks shaping the next phase of enterprise and government computing.
Everforth Investment Narrative Recap
To own Everforth, you need to believe its pivot toward higher value AI, cloud, and cybersecurity work can offset pressure in lower margin staffing and federal contracts. The expanded Microsoft partnership and SUNet 2.0 extension both support that mix shift, but they do not remove near term issues such as thinner 2.1% net margins and softer recent earnings.
The key short term catalyst is execution on complex AI and cloud programs without further margin compression or heavy one off items. The biggest risk is that rising SG&A, weaker cash coverage of debt, and contract mix in the Federal segment keep profitability subdued even as Everforth leans harder into consulting and IP rich services.
The SUNet 2.0 sole source award looks most relevant here. It reinforces Everforth’s decade long role inside sensitive federal digital and AI infrastructure and connects directly to the Microsoft Cloud Solutions Partner initiative. For investors, the question is whether that kind of work shifts the Federal segment toward steadier, higher quality consulting revenue or keeps Everforth tied to lower margin delivery.
The enlarged Microsoft relationship supports the same thesis. More than 1,500 Microsoft certifications, three cloud and AI designations, and a unified commercial and federal model position Everforth to pitch repeatable solutions across clients. Execution risk lies in delivery complexity, contract profitability, and the firm’s ability to translate this partnership into better margins rather than just higher volume.
Everforth's narrative projects US$4.2b revenue and US$141.8m earnings by 2029. This implies 1.6% yearly revenue growth and an earnings increase of about US$43.7m from current earnings of US$98.1m.
Uncover why Everforth's fair value indicates a 17% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts think Everforth’s deep AI push could matter far more than the SUNet 2.0 contract alone. Before this news, they were already penciling in revenue of about US$4.4b and earnings of roughly US$200.9m by 2029. You can compare those bullish assumptions with your own and decide which story fits best.
Explore another Everforth fair value estimate, including one that suggests as much as 93% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Everforth research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Everforth. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Everforth's overall financial position at a glance.
Looking For More Ideas Beyond Everforth?
Once you have a view on Everforth, it can help to line it up against other candidates that fit different roles in your portfolio. The Simply Wall St Screener is built for exactly that kind of comparison, so you can quickly scan for businesses with the traits you care about most.
- If you want potential mispricings backed by solid fundamentals, start by reviewing a curated 32 high quality undervalued stocks that may warrant a closer look.
- If resilience matters more than excitement, filter for stability first by running through a 30 resilient stocks with low risk scores that score well on downside protection.
- If you are hunting for overlooked potential, broaden your watchlist with a 16 high quality undiscovered gems that are not yet heavily followed but show strong underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com