
Board Appointment Might Change The Case For Investing In Sanmina (SANM)
- Sanmina appointed Shanker Trivedi to its board of directors on September 14, 2026, adding more than 30 years of enterprise technology, data center, and cloud infrastructure leadership, including senior roles at NVIDIA, Sun Microsystems, IBM, and other major providers.
- Trivedi's track record in go to market execution for data center and AI infrastructure aligns with Sanmina's push into complex electronics manufacturing for cloud, communications, and advanced computing clients.
- This development provides additional context for understanding how Sanmina's investment narrative may be influenced by this board appointment and Trivedi's extensive data center leadership experience.
Scan beyond Sanmina and size up other potential beneficiaries of the same data center and AI buildout story with our hand picked list of 87 AI infrastructure stocks.
Sanmina Investment Narrative Recap
For Sanmina, the core belief is that complex electronics manufacturing, especially for cloud, communications, and data center customers, can keep supporting revenue and earnings expansion. The big near term swing factor is how well the business executes on higher value, AI centric system builds while managing working capital and inventory tied to fast moving hardware cycles.
The largest immediate risk remains execution around large projects, concentrated customers, and the planned ZT Systems acquisition, where $2b of inventory and product mix create real downside if demand shifts. Shanker Trivedi's appointment looks additive for expertise but does not materially change those short term operational risks on its own.
The planned acquisition of ZT Systems is the announcement that lines up most directly with Trivedi joining the board. Sanmina is positioning itself deeper into data center and AI infrastructure, with ZT expected to add an estimated $5b to $6b of annual run rate revenue once integrated, according to analyst assumptions.
That move raises both the potential upside and the execution bar. Integration of ZT, expansion in the U.S., India, and Mexico, and heavy investment in automation and full system builds all tie into the same thesis that Sanmina can handle more complex AI hardware at scale. Trivedi's data center background fits that operational challenge, even as customer concentration and inventory risk stay front of mind.
Sanmina's narrative projects US$20.6b revenue and US$792.1m earnings by 2029. That profile assumes 17.2% yearly revenue growth and roughly a US$484m earnings increase from US$308.1m today.
Uncover why Sanmina's fair value indicates a 16% potential upside to its current price that could narrow quickly.
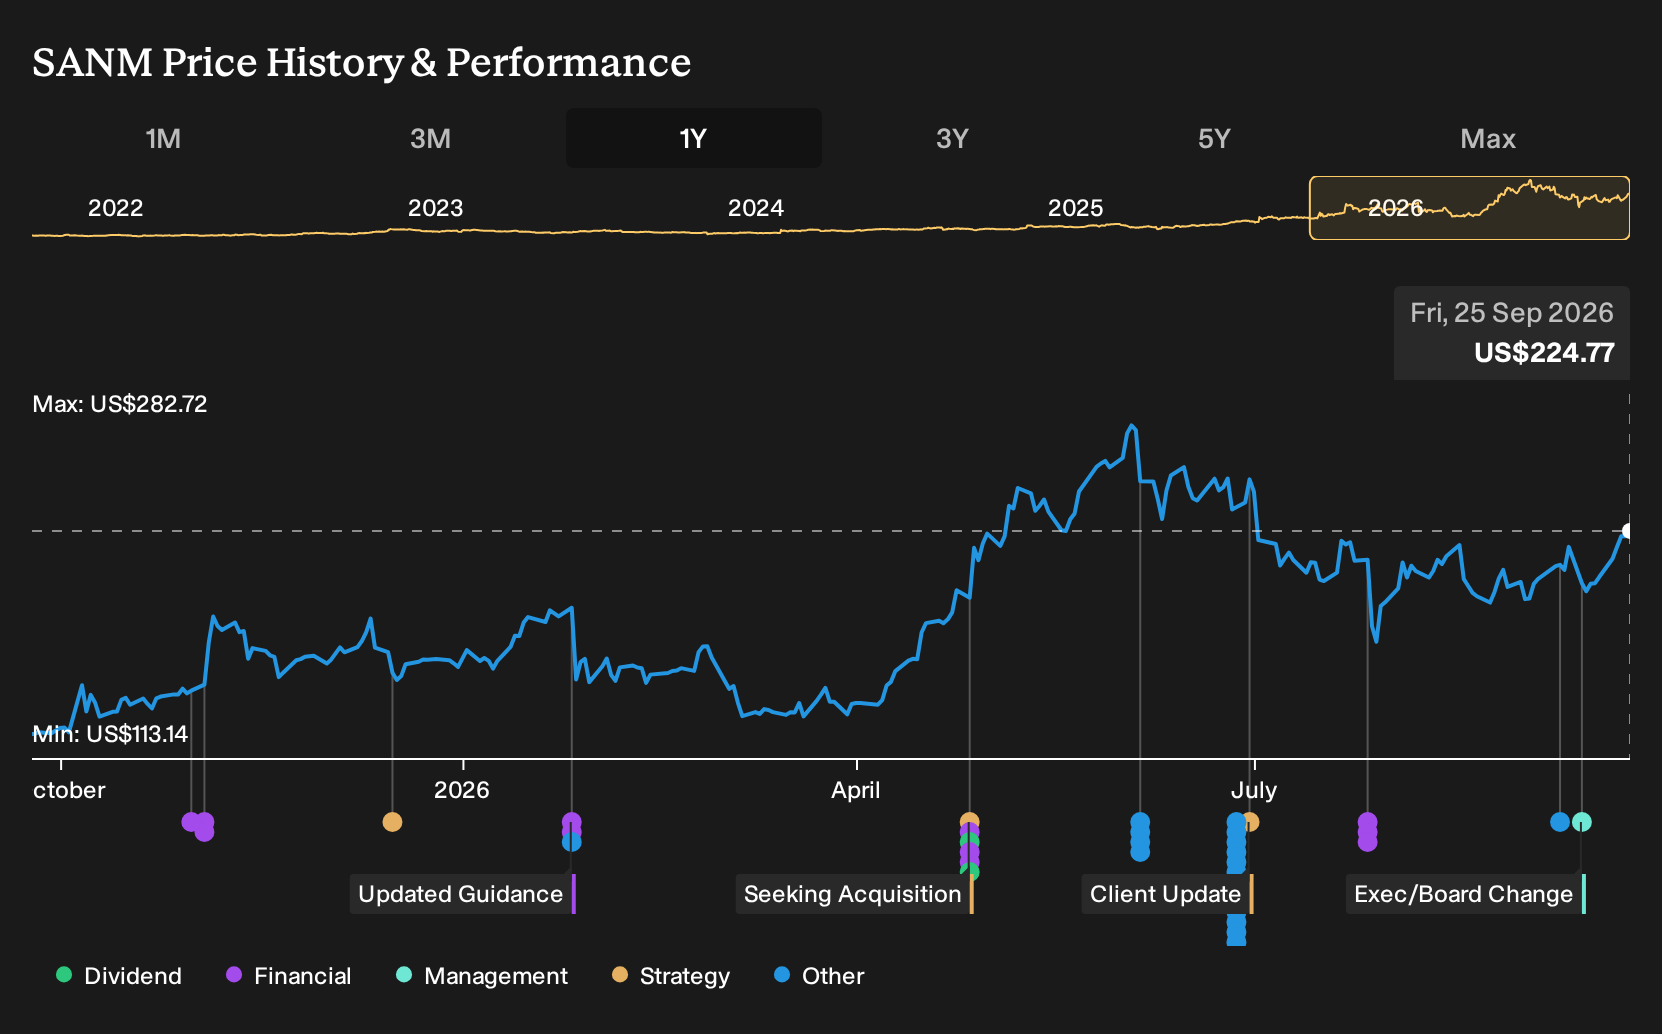
Exploring Other Perspectives
You can look at Sanmina through a very different lens. The most cautious analysts focus on margin pressure rather than AI upside. They were penciling in revenue of about US$19.9b and earnings of US$701.7m by 2029. Those forecasts were set before Trivedi joined the board, so expectations on both sides could shift from here.
Explore 2 other Sanmina fair value estimates, including one that suggests as much as 85% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Sanmina research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sanmina. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Sanmina's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sanmina?
If Sanmina has you thinking about where else the data center, AI, and manufacturing story might show up in your portfolio, the Simply Wall St Screener can help you quickly scan for other stocks that line up with your own risk and return preferences.
- If capital preservation ranks high for you, you might start with a basket of relatively steady businesses by checking out 30 resilient stocks with low risk scores.
- If income is the priority, you can focus on companies with stronger cash returns to shareholders by reviewing a curated set of 8 dividend fortresses.
- If you want to look for under the radar potential, you could cast a wider net across smaller, less followed opportunities through 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com